


EN
Is Viridian Therapeutics (VRDN) Cheap After FDA Approval Of Lumvoa?
FDA approval puts Viridian Therapeutics into commercial spotlight
The recent FDA approval of Lumvoa for Thyroid Eye Disease puts Viridian Therapeutics (VRDN) into the commercial arena, shifting investor focus toward launch execution, early prescribing trends, and the size of its initial market opportunity.
Viridian Therapeutics has seen momentum pick up around the Lumvoa decision, with a 1-month share price return of 17.7% and a 3-month gain of 21.2%. However, the stock is still down 21.5% year to date, while the 3-year total shareholder return of 92.7% points to a much stronger longer-term journey as sentiment has shifted with each regulatory milestone.
Look beyond Viridian Therapeutics and explore other potential breakout biotech stories with the curated 21 high quality undiscovered gems, which features companies that combine strong fundamentals with limited market attention.
Viridian Therapeutics just moved into prime time, yet the share price still trails both analyst targets and some intrinsic value estimates. Where does a fair entry really fall after this FDA approval jump?
Most Popular Narrative: 34% Undervalued
On the narrative view, Viridian Therapeutics screens as materially cheaper than its implied fair value of $36.75, compared with the last close at $24.09. This puts the focus squarely on how much of the thyroid eye disease opportunity is already embedded in expectations.
The key execution swing factor is whether Viridian can convert the current roughly $2b TED IGF-1R opportunity, with 6,000 to 7,000 patients treated annually and single-digit penetration, into broader adoption of its shorter-course IV and planned subcutaneous regimens.
See why 2 investors see Viridian Therapeutics as 34% undervalued.
Result: Fair Value of $36.75 (UNDERVALUED)
Still, Viridian Therapeutics relies on analysts’ steep revenue and margin assumptions, and any reset in those forecasts or the lofty 75x implied P/E could quickly challenge this undervalued story.
Find out about the key risks to this Viridian Therapeutics narrative.
Another View: Viridian Therapeutics Looks Expensive On Sales
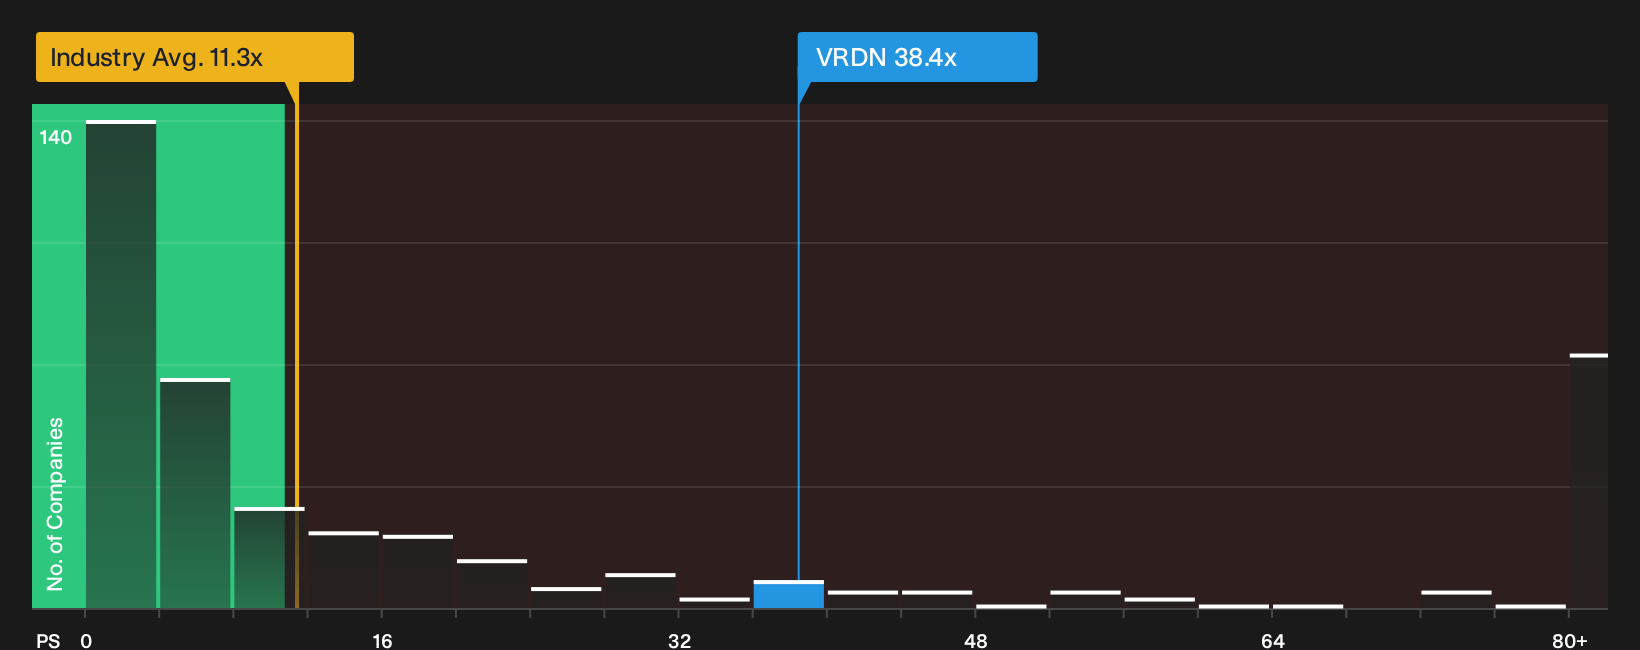
There is a very different picture when you look at Viridian Therapeutics through its P/S ratio instead of fair value models. The shares trade on 38.4x sales, compared with 10.7x for the US Biotechs industry and 8.7x for peers, while the fair ratio sits at just 0.1x. That gap places more of the valuation risk on execution. How comfortable are you paying a premium sales multiple for a business that still reports losses?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split between rich sales multiples and a bullish fair value, it makes sense to move fast and test the numbers yourself. Start by weighing both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Viridian Therapeutics?
Do not stop with Viridian Therapeutics. Use the broader opportunity set to pressure test your thesis, find fresh setups, and keep your watchlist ahead of the crowd.
- Hunt for potential mispricings by reviewing companies that screen well on quality and valuation through the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses in the 5 dividend fortresses that combine higher yields with fundamental support.
- Prioritize resilience by concentrating on companies in the 30 resilient stocks with low risk scores that show lower risk scores and more durable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com