


EN
Is Nomura Holdings (TSE:8604) Undervalued Following Higher Profit And A Dividend Rise?
Nomura Holdings (TSE:8604) reported a 13% rise in net profit for the September quarter, supported by 22% growth in wealth management revenue and a higher interim dividend of ¥35 per share.
Nomura Holdings shares closed at ¥1,441.5, with the stock down 9.62% on a 1 month share price basis yet still showing a 7.02% share price gain year to date. The 1 year total shareholder return of 37.78% and 5 year total shareholder return of 250.41% indicate momentum that has been built over a longer horizon as investors respond to improving profitability and a higher dividend.
See how Nomura Holdings compares with other financials showing strong income growth and rising payouts using our curated list of 16 high quality undervalued stocks.
Nomura Holdings has just raised profit and the interim dividend, yet the share price has eased over the past month. Does that recent pullback offer a reasonable entry, or does patience make more sense before valuing the stock?
Most Popular Narrative: 19% Undervalued
On the most followed view, Nomura Holdings screens as undervalued, with a fair value of ¥1,772.86 against the recent close at ¥1,441.5. That gap puts the focus on how stable fee income, Banking and cost control could influence where the shares go from here.
The main execution priorities are growing global asset management and private markets, improving Wholesale capital efficiency and scaling the new Banking pillar so that group returns stay aligned with the higher 2030 targets.
The current valuation implies the share price does not fully reflect the company’s view that its earnings are becoming more stable, its long term ROE and profit targets are higher and its asset management and banking platforms are intended to support that profile.
See why 1 investors see Nomura Holdings as 19% undervalued.
Result: Fair Value of ¥1,772.86 (UNDERVALUED)
Still, if wholesale trading stays subdued for longer or funding costs rise because of shifts in yen markets, the Nomura Holdings undervaluation story could come under pressure.
Find out about the key risks to this Nomura Holdings narrative.
Another View On Nomura Holdings: P/E Signals A Different Story
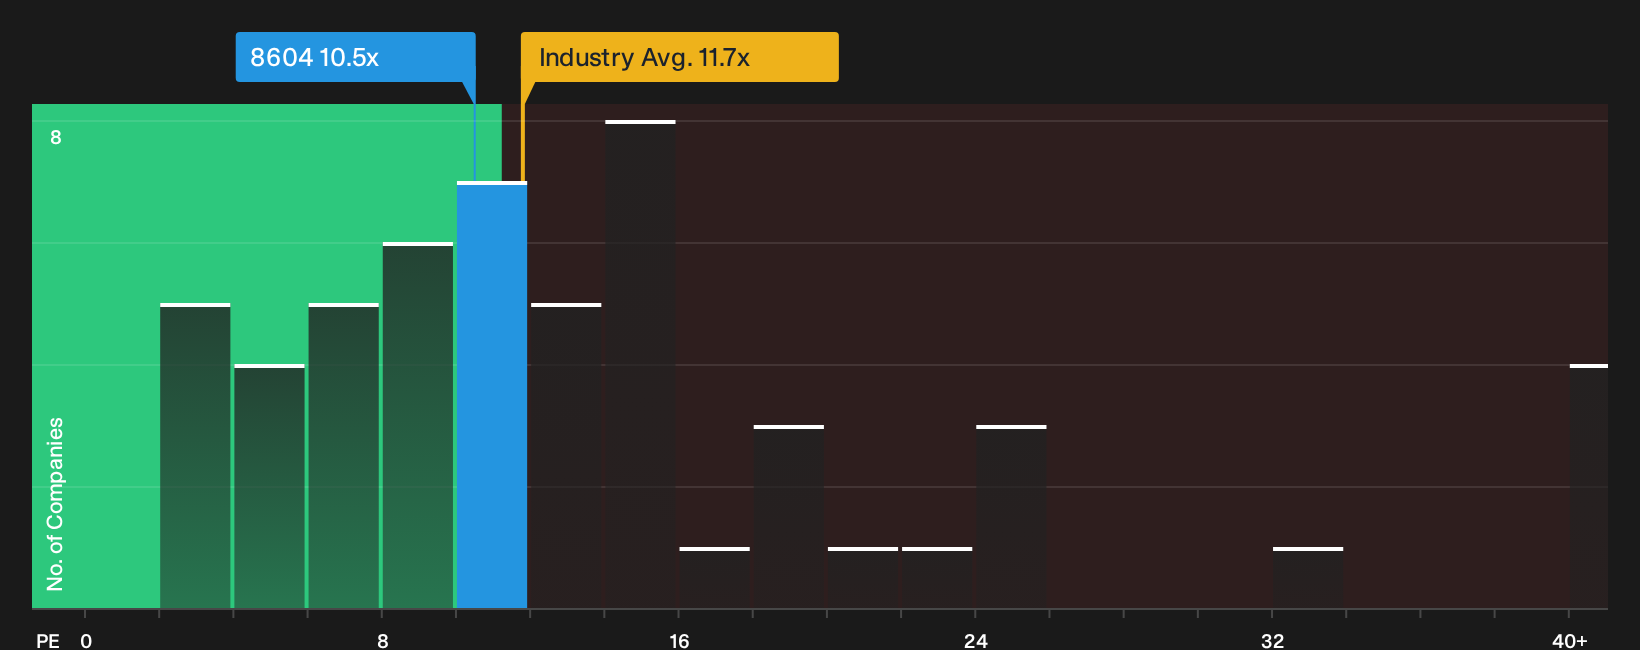
The SWS DCF model points to undervaluation, yet the market is not pricing Nomura Holdings in a simple bargain bucket. The shares trade on a P/E of 10.5x, above the 9.6x peer average, but below both the JP Capital Markets group at 11.7x and an estimated fair ratio of 19.1x. That mix of cheaper than fair and pricier than peers raises a blunt question for investors: Is the gap a cushion or a warning shot if sentiment cools?
See what the numbers say about this price in more detail with the valuation breakdown here, then weigh it against your own expectations before making any move, See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how Nomura Holdings compares against its sector on earnings multiples, check the latest P/E comparison chart,
Next Steps
There are mixed views on Nomura Holdings so far. If you want to move quickly and base your stance on the underlying data, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nomura Holdings?
If Nomura Holdings has sharpened your focus, do not stop there. Broader idea hunting with structured tools can help you spot opportunities you might otherwise miss.
- Target potential step changes in your portfolio by scanning 72 high quality undiscovered gems that many investors may not be watching yet.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle tougher conditions and funding pressures.
- Prioritise consistency in your income plan by reviewing a 29 dividend fortresses that aims to combine higher yields with underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com