


EN
How Raised Guidance At Crane (CR) Has Changed Its Investment Story
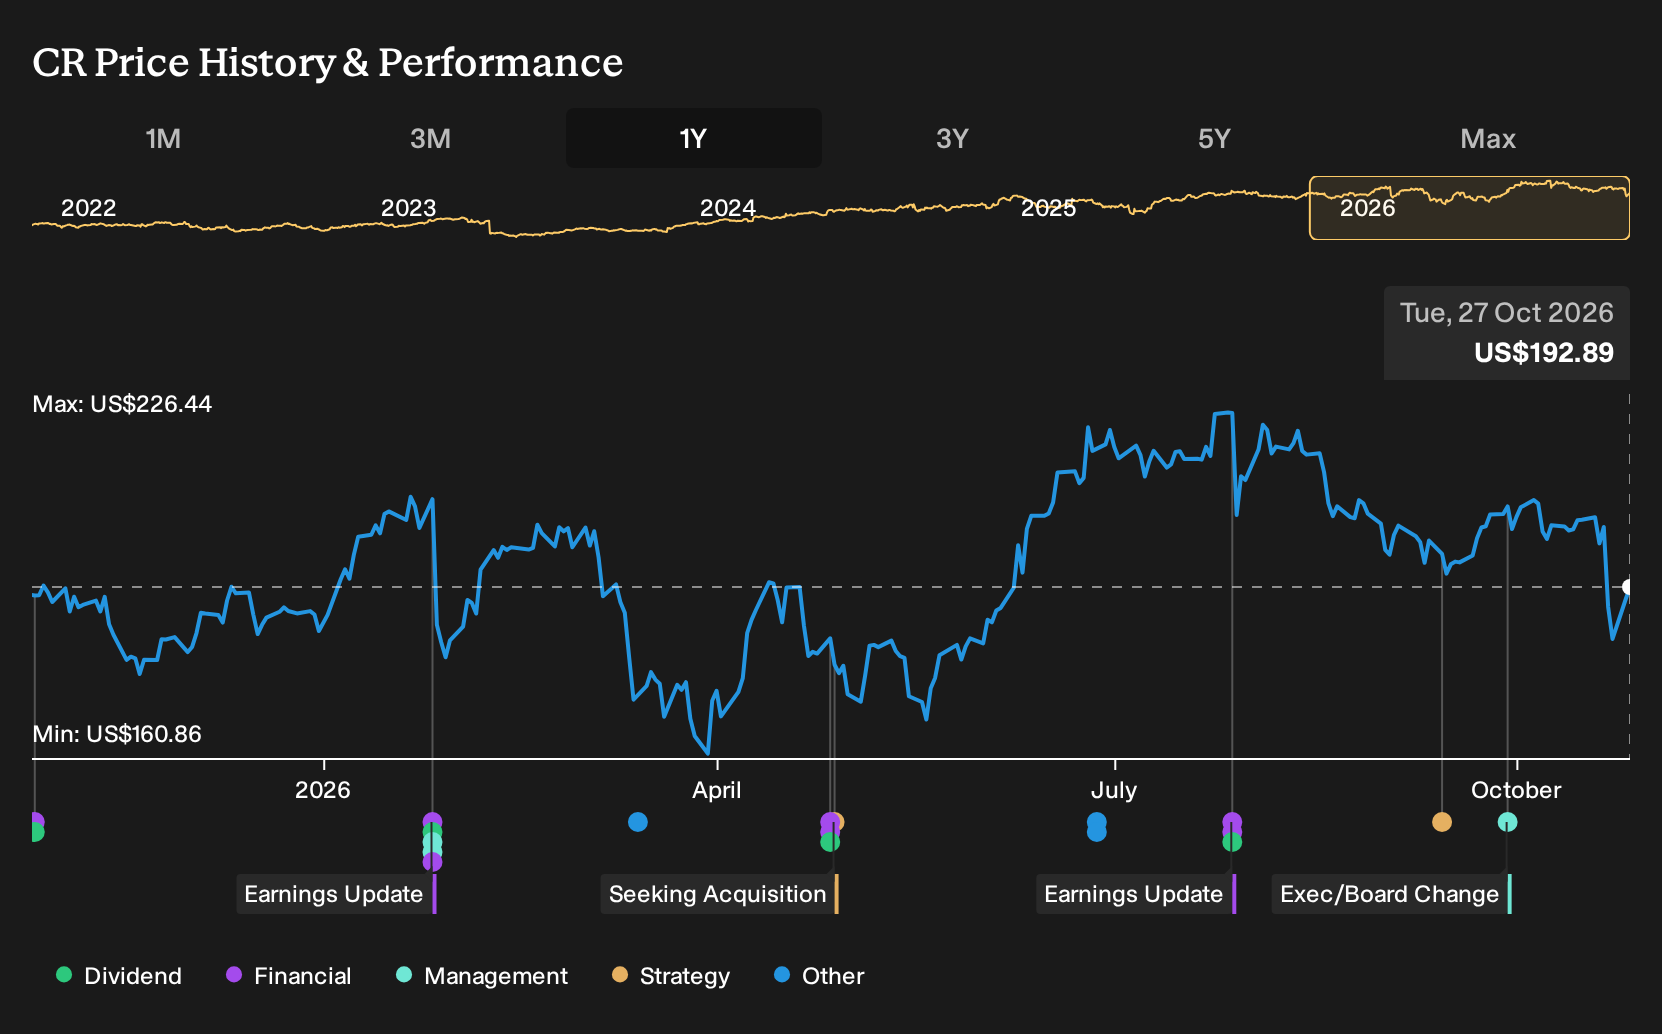
- Crane Company reported third quarter 2026 revenue of US$754.6 million and net income of US$97.3 million, alongside higher full-year earnings guidance and a confirmed quarterly dividend of US$0.255 per share.
- Management now expects total 2026 sales to rise about 26% at the midpoint, with both acquired businesses and core operations tracking toward the top of their prior ranges.
- This development may influence how Crane's raised full-year guidance is viewed in terms of the investment narrative and the way investors frame its earnings power.
Scan how Crane's latest guidance compares with peers by lining it up next to 29 high quality undervalued stocks that also pair strong balance sheets with earnings momentum.
Crane Investment Narrative Recap
To own Crane, you need to believe the business can keep turning its aerospace backlog, higher margin sensing assets and process flow portfolio into consistent earnings, even as end markets stay mixed. The raised 2026 sales outlook, at about 26% growth at the midpoint, supports that earnings power story rather than changing it.
The more immediate swing factor still looks like execution. Integrating PSI, holding margins after recent one off items and avoiding prolonged weakness in chemicals linked orders are what matter most. The key risk is that any slip in pricing or productivity chips away at Crane’s premium P/E and compresses earnings leverage.
The clearest data point tying this all together is Crane’s updated guidance. Management now expects 2026 total sales to increase about 26% at the midpoint, with both acquisition driven and core activity tracking toward the high end of prior 18% to 20% and 5% to 6% ranges.
That outlook frames the catalyst path. PSI, nuclear related exposure and record aerospace backlog already sit in higher margin pockets that can support earnings, as long as chemicals related softness in Process Flow Technologies stays contained and aftermarket aerospace demand does not soften more than Crane’s cautious stance already allows for.
Crane's current analyst narrative points to US$3.3b revenue and US$528.4 million earnings by 2029, based on an assumed 8.7% yearly revenue growth rate and an earnings increase of about US$192.3 million from the US$336.1 million reported today.
Uncover why Crane's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Crane, the bullish twist is acquisition firepower. The most optimistic analysts were already mapping a path to about US$3.4b revenue and US$595.4 million earnings by 2029 before this quarter, leaning on more deals and a higher tech mix. You can now consider whether this guidance raise supports that story, challenges it, or suggests a different trajectory, and compare several viewpoints before deciding what feels reasonable to you.
Explore 4 other Crane fair value estimates, including one that suggests as much as 31% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Crane research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crane's overall financial health at a glance.
Looking for more Crane investment ideas?
If Crane has sharpened your focus on quality and earnings power, it can be helpful to line it up against a wider watchlist using the Simply Wall St Screener and see what else matches your own criteria.
- For investors who want potential upside paired with strong fundamentals, start with a curated group of 21 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation and resilience matter most to you, filter for sturdier businesses by reviewing a focused 30 resilient stocks with low risk scores that scores well on financial risk metrics.
- When balance sheet strength is your starting point, build out a bench of candidates from a list of solid balance sheet and fundamentals (24 results) and then compare them to Crane's profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com