


EN
Caught Out By JD Health International's Fall? Here's What Bears Saw
If you had backed the bullish October 2025 case for JD Health International, the past year would have felt very different from what was sketched on paper. Holding JD Health International over the past year would have meant a 41.4% loss, including dividends. If that decision date were yours, with revenue growth assumptions near 14.8%, a 7.1% margin and a 3-year horizon, which part of that original thesis most clearly failed to anticipate what actually unfolded?
JD Health International has already moved. See which of 195 high quality undervalued stocks still trade below our estimates.
The Two JD Health International Stories Investors Were Choosing Between
The shares cost HK$62.2 at the start of the period, and anyone looking at JD Health International then had to choose between two very different stories.
The bullish view saw a Fair Value of HK$67.22, the rough price implied if revenue grew 14.8% a year and profit margin settled near 7.1% over three years. This camp leaned on rapid AI adoption, an expanding omnichannel network and policy support for digital healthcare.
The bearish narrative pointed to a Fair Value of HK$26.28 based on tighter regulatory pressure and heavier compliance costs. Here, the key worry was that rising competition, data rules and pricing controls in China would strain margins and limit long term profitability.
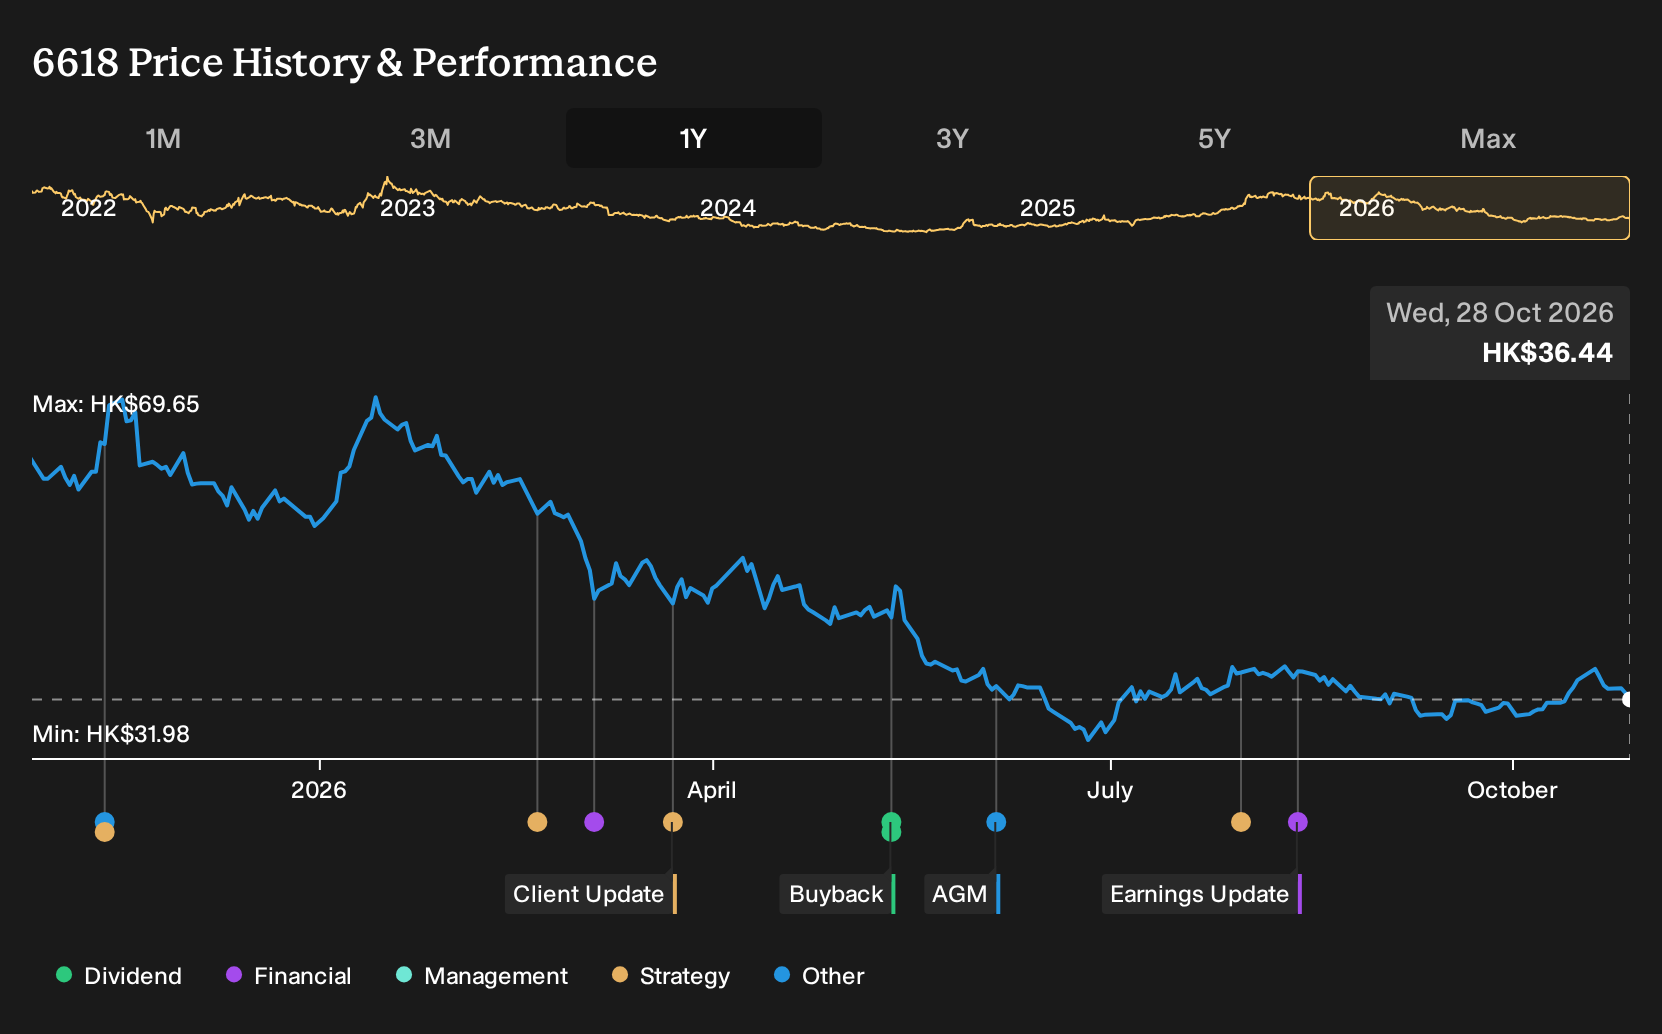
What The Results Changed For JD Health International
The clearest update came from JD Health International reporting H1 2026 revenue of CN¥40,887.884m and net income of CN¥3,436.804m, with net margin at 8.4% versus 7.4% a year earlier. That profitability level sat above the earlier 7.1% margin assumption and therefore leaned toward supporting the optimistic case, even as the share return moved the other way.
The practical takeaway is simple. When a thesis hangs on margin maths, treat the reported net margin as the key checkpoint and track whether it trends toward or away from the original forecast before worrying about the share price reaction.
What You Are Paying For In JD Health International Today
JD Health International trades at HK$36.44, with the selected Narrative arguing that its Fair Value sits above that level based on how AI tools and offline pharmacies may reshape earnings quality over time.
The key assumption a buyer must weigh is that AI driven healthcare services and higher value service revenue can scale enough to support sustained margin strength.
"The main thing that has to go right is that JD Health International successfully scales and monetizes its AI driven healthcare services while integrating its expanding offline pharmacies, at home services and pharmaceutical supply chain into a coherent model."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 20% below our estimate - uses a dispersed partner model and proprietary AI tools to attract senior lawyers.
- Company 2 - 45% below our estimate - pushes a design led lifestyle label into new stores while expanding digital channels.
- Company 3 - 33% below our estimate - leans on omnichannel electronics retail as store openings and online upgrades redirect spending.
Those are three of them. See all 207 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com