


EN
Dear Merck Stock Fans, Mark Your Calendars for October 29
Merck (MRK), known as MSD outside the United States and Canada, has earned a heavyweight spot in the pharmaceutical industry. Its blockbuster cancer immunotherapy Keytruda brought in $31.7 billion in 2025, giving the company a powerful revenue engine alongside its broader portfolio of oncology treatments, vaccines, and cardiometabolic medicines.
Now, the pharmaceutical giant faces another major test as it prepares to report its Q3 FY2026 financial results before the market opens on Thursday, Oct. 29. The results would show whether Keytruda can continue doing the heavy lifting, particularly as Merck expands its subcutaneous formulation, Keytruda Qlex, which delivers the treatment through an injection under the skin.
Newer products, including Winrevair, a drug for pulmonary arterial hypertension; Welireg, a kidney cancer drug; and Capvaxive, a pneumococcal vaccine, could also contribute. The Animal Health segment provides another source of support. However, continued weakness in Gardasil, Merck’s human papillomavirus (HPV) vaccine, and other vaccines could weigh on the company’s growth.
Beyond the next earnings announcement, Merck has a much bigger challenge. Keytruda is nearing the 2028 expiry of its U.S. patent. Management plans to use more than 20 new growth drivers to help bridge the gap, targeting a potential commercial opportunity of over $70 billion annually by the mid-2030s.
With earnings day just around the corner, investors might want to keep an eye on the results, management’s commentary, and the market’s reaction for clues about what’s next for Merck’s growth.
About Merck Stock
Merck develops, manufactures, and commercializes human pharmaceuticals, vaccines, and animal health products. With a market cap of around $346.9 billion, the company treats conditions ranging from cancer and infectious diseases to diabetes while supplying veterinary medicines, vaccines, and livestock management solutions.
Investors have enjoyed a strong run with Merck’s shares, which have advanced 63% over the past 52 weeks, including 35% gains in 2026 and 29% over six months. However, the Rahway, New Jersey-based drugmaker’s stock is down 5% in the last month amid concerns about its growth outlook.
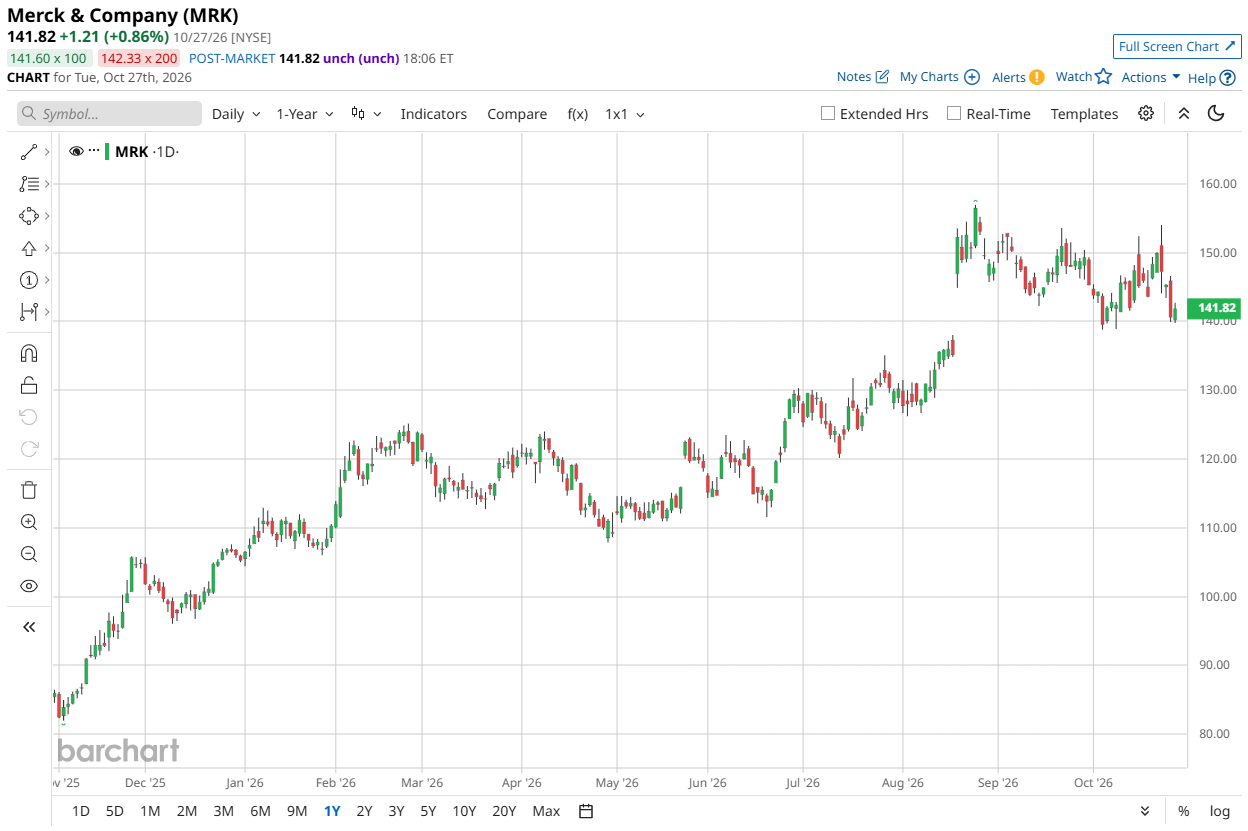
Investors have also paid a premium for Merck’s shares. MRK stock currently trades at 53.02 times forward adjusted earnings and 5.17 times sales. Both multiples exceed their respective industry averages and their own five-year averages, suggesting the market has already priced in considerable optimism.
Merck has also increased its dividend for 15 consecutive years and currently distributes $3.40 per share annually, translating into a yield of 2.42%. Its most recent dividend of $0.85 per share was paid on Wednesday, Oct. 7 to shareholders of record as of Tuesday, Sept. 15.
Merck Surpasses Q2 Earnings
On Aug. 4, Merck released its Q2 FY2026 results, with revenue reaching $16.61 billion, a 5.1% year-over-year (YoY) increase and above analyst expectations of $16.27 billion. KEYTRUDA and KEYTRUDA QLEX generated a combined $8.37 billion, up 5.2% YoY.
Broader use in earlier-stage cancers and sustained demand for treatment of metastatic disease supported the gains. KEYTRUDA QLEX also brought in $463 million as more patients began using the newer formulation. Merck’s newer products added further momentum. WINREVAIR delivered a 75% sales increase to $588 million, thanks to strong U.S. demand and international launches.
WELIREG grew sales by 67% to $271 million. Meanwhile, Animal Health revenue rose 7.8% to $1.78 billion as livestock demand and newer companion animal products boosted performance.
However, Merck faced some pressure on its margins and expenses. Non-GAAP gross margin slipped 1.1 percentage points to 81.1%, reflecting higher inventory-related costs. Non-GAAP SG&A expenses climbed 10% as administrative spending and promotional activity surrounding product launches increased.
Merck reported a bottom-line non-GAAP loss per share of $0.13, compared with analysts’ estimated loss per share of $0.26, comfortably beating expectations. The loss was primarily driven by a $2.31 per-share charge related to the acquisition of Terns Pharmaceuticals.
Looking forward, management has raised its 2026 revenue outlook to a range of $66.3 billion to $67.3 billion, putting the midpoint at $66.8 billion. However, the company lowered its adjusted EPS guidance to a range of $2.66 to $2.76, reflecting $2.43 per share in Terns-related charges.
Meanwhile, analysts expect Merck’s Q3 FY2026 EPS to decline 17.8% YoY to $2.12. For FY2026, they project EPS of $2.64, representing a steep 70.6% drop from the previous year. The outlook improves considerably in FY2027, when analysts expect EPS to rebound 250.8% to $9.26.
What Do Analysts Expect for MRK Stock?
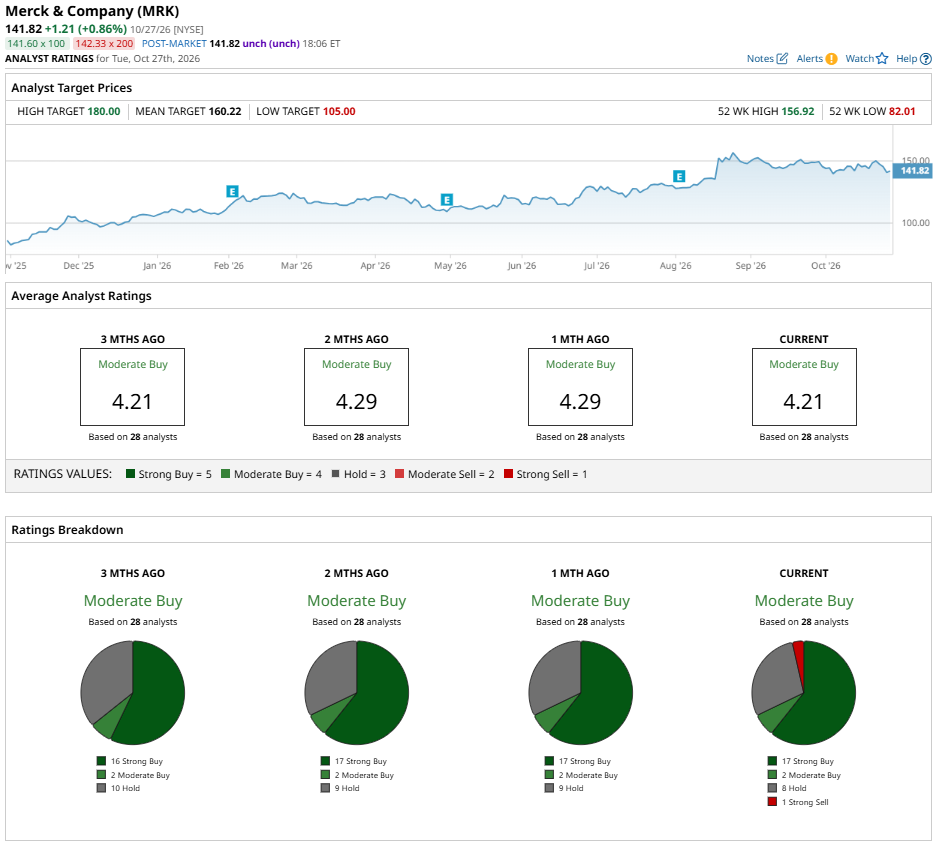
Across Wall Street, the overall consensus rating is a “Moderate Buy.” Among the 28 analysts covering the stock, 17 rate it a “Strong Buy,” two recommend a “Moderate Buy,” eight maintain a “Hold,” and one issues a “Strong Sell.”
To that end, the stock’s average price target of $160.22 represents a potential upside of 13%. Meanwhile, the Street-high target of $180 suggests a gain of 27% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.