


EN
Dear Amazon Stock Fans, Mark Your Calendars for October 29
Amazon.com (AMZN) is set to report its third-quarter results for fiscal 2026 on Oct. 29, after the market closes. Ahead of the results, investors are waiting to see how the company’s aggressive artificial intelligence (AI) spending will show up in its earnings and cash position. In August, Amazon pushed its capital spending estimate from $200 billion to $220 billion, mainly due to higher memory and component costs and continued build-out of AI and cloud infrastructure. This is supported by the continuous growth in its AWS segment.
Ahead of its earnings, let's take a closer look at the tech giant.
About Amazon Stock
Amazon, headquartered in Seattle, Washington, operates global e-commerce, cloud computing, logistics, advertising, streaming, and AI services. The popular tech giant has a massive market capitalization of $2.69 trillion.
Amazon is focusing on expanding its AI and cloud-computing capabilities while strengthening its retail and logistics operations. The company is investing heavily in data centers and AI services to meet growing demand from businesses and consumers. At the same time, it is updating consumer devices and integrating AI across shopping, delivery, entertainment, and business tools. These efforts reflect its broader strategy to deepen its technology ecosystem, improve customer experiences, and support long-term growth across its global operations.
Amazon’s stock is up only 10.5% over the past 52 weeks because strong AWS and AI optimism has been offset by heavy spending and valuation concerns. Investors remain cautious about the company’s large capital expenditures on data centers and AI infrastructure, which have weighed on free cash flow. The stock is down 2.4% over the past six months. It reached a 52-week high of $287.20 on Aug. 3, but is down 12% from that level.
AMZN stock is stretched compared to its peers. Its forward-adjusted price-to-earnings ratio of 19.29x is higher than the industry average of 16.05x.
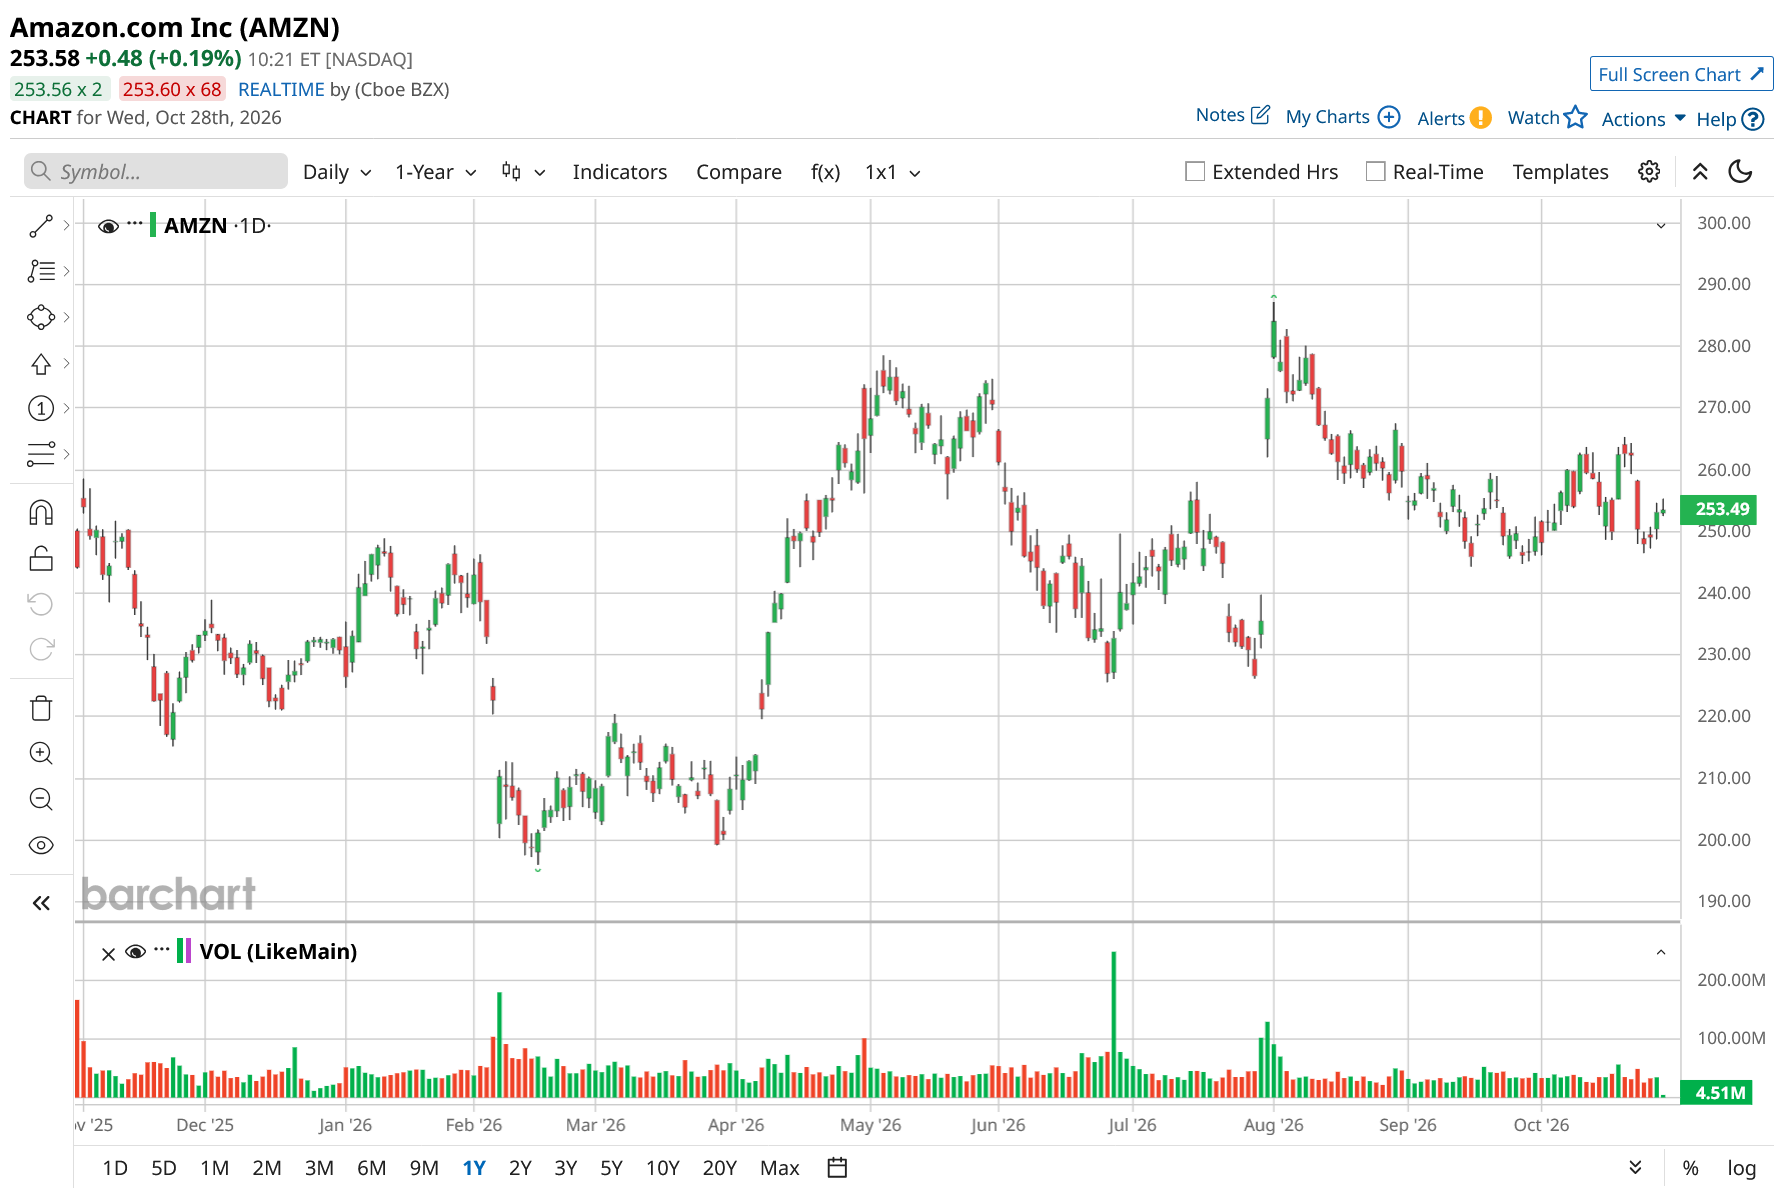
Amazon Delivered Strong First-Half Results on AWS Growth
Amazon reported strong results during the first half of the year. The company’s total net sales increased 18.2% year-over-year (YoY) to $382.13 billion. This was driven by AWS revenue, which rose 32.7% from the prior-year period to $79.82 billion. Management highlighted that this is AWS’ fastest growth in 18 quarters. In Stores, Amazon set record delivery speeds for Prime members in the first half of the year, which reflects its efficiency. Amazon’s EPS grew from $3.27 to $8.53 over the same period.
All eyes were set on Amazon’s cash position to gauge the effect of Amazon’s aggressive AI spending. For the 12 months ended in June 2026, net cash used in investing activities rose to $216.78 billion. Amazon had cash, cash equivalents, and restricted cash of $80.93 billion, with long-term debt of $128.89 billion as of June 30.
Wall Street analysts are modestly optimistic about Amazon’s future earnings. They expect the company’s EPS to climb 3.1% YoY to $2.01 for the about-to-be-reported third quarter. For fiscal 2026, EPS is projected to surge 5.3% to $7.55, followed by a 41.1% growth to $10.65 in fiscal 2027.
What Do Analysts Think About AMZN Stock?
Ahead of Amazon’s earnings, analysts at Morgan Stanley named AMZN stock a top pick and raised its price target from $335 to $350 while maintaining an “Overweight” rating. Analyst Brian Nowak pointed to faster cloud growth, higher profits, and several AI-related opportunities. Morgan Stanley raised its AWS growth forecasts to 47% in 2027 and 42% in 2028, up from prior estimates of 41% and 37%.
UBS analysts raised their price target on AMZN from $318 to $348, while keeping a “Buy” rating. UBS analyst Stephen Ju believes that analysts are underestimating how much profit AWS can generate from its expanding AI infrastructure. The bank forecasts AWS operating margins of 46% in 2027.
Meanwhile, analysts at Cantor Fitzgerald kept a cautious outlook by lowering the price target from $320 to $310, while maintaining a bullish “Overweight” rating. This revision reflects Amazon’s efforts to manage intense competition in the consumer cyclical sector.
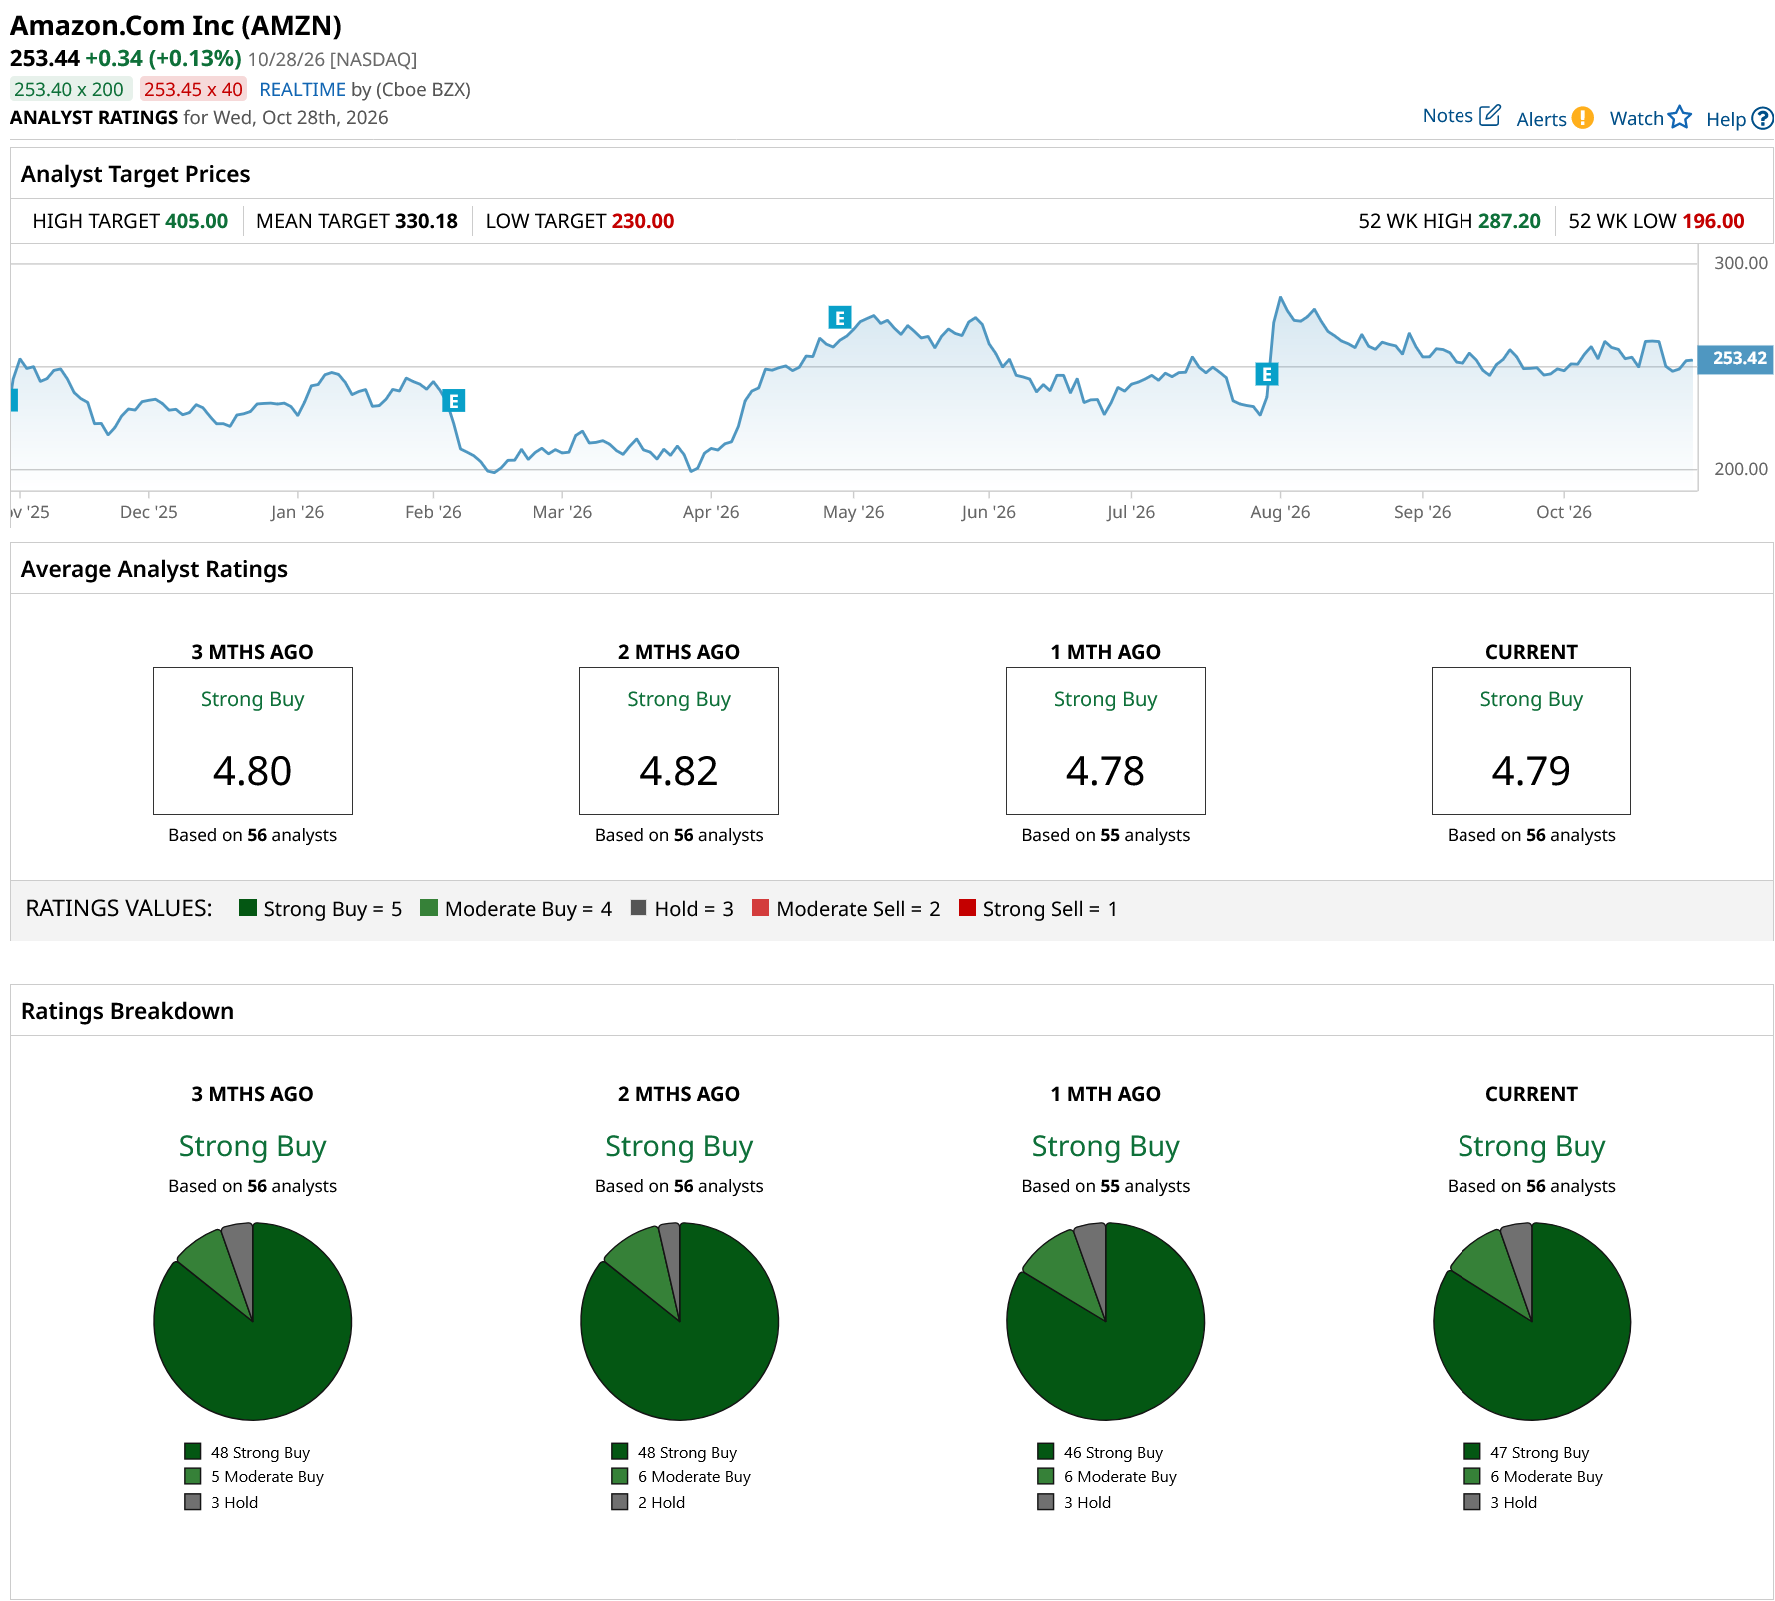
AMZN stock has been in the spotlight on Wall Street for some time now, with analysts awarding it a consensus “Strong Buy” rating overall. Of the 56 analysts rating the stock, a majority of 47 rate it a “Strong Buy,” six rate it a “Moderate Buy,” and three analysts take the middle-of-the-road approach with a “Hold” rating. The consensus price target of $330.18 represents 31% upside from current levels. Moreover, the Street-high price target of $405 indicates a 60% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.