


EN
3 Rate Sensitive Growth Stocks Retail Investors Are Watching After The Fed Pause
Fed officials are set to pause at 3.75% to 4.00% today, and that quiet decision could be loud for high growth tech and communication services stocks that are highly sensitive to discount rates. If policy makers hint that December is back on the table, some interest-rate-sensitive growth stories may gain fresh attention while others fade from focus. This article walks through three stocks from the screener that appear especially exposed to this news and explains why that may matter for your portfolio watchlist right now.
Those three tickers are only a starting sample from this rate-sensitive growth theme, and the full screen surfaced 20 more large-cap tech and communication services companies with equally compelling stories that are not covered below. To see the complete universe and identify which interest-rate plays match your own risk and growth preferences, head straight to the U.S. Interest-Rate-Sensitive Growth Stocks (Large-Cap Tech & Communication Services) screener.
Snowflake (SNOW)
Snowflake is a pure-play AI-ready cloud data platform that fits this rate-sensitive growth screen, because investors treat its long-term revenue potential and high volatility as closely tied to where Fed policy and discount rates settle over the next few years.
Snowflake provides a cloud-based AI Data Cloud that lets enterprises consolidate information, run data applications and share data products. It currently reports all revenue from Internet Software & Services, around US$5.4b, and carries a market value of roughly US$118.1b.
For investors tracking interest-rate-sensitive tech, Snowflake offers a concentrated way to gain exposure to long-term AI and data demand. The story becomes clearer once recent product moves are factored in.
"Snowflake just made a significant move by partnering with Anthropic to bring Claude AI models directly into their platform."
The key question is how one shift in AI-driven customer usage ultimately feeds through to margins and contract growth.
That margin puzzle is exactly what the full narrative for Snowflake unpacks, separating short-term hype from where Snowflake’s AI usage, pricing power and cash generation could realistically be heading next.

Amphenol (APH)
Amphenol plugs directly into the screener theme through its role in high speed connectors and cables for tech and communications hardware, giving investors exposure to interest-rate-sensitive capex cycles while still looking and feeling like an industrial supplier rather than a pure software play.
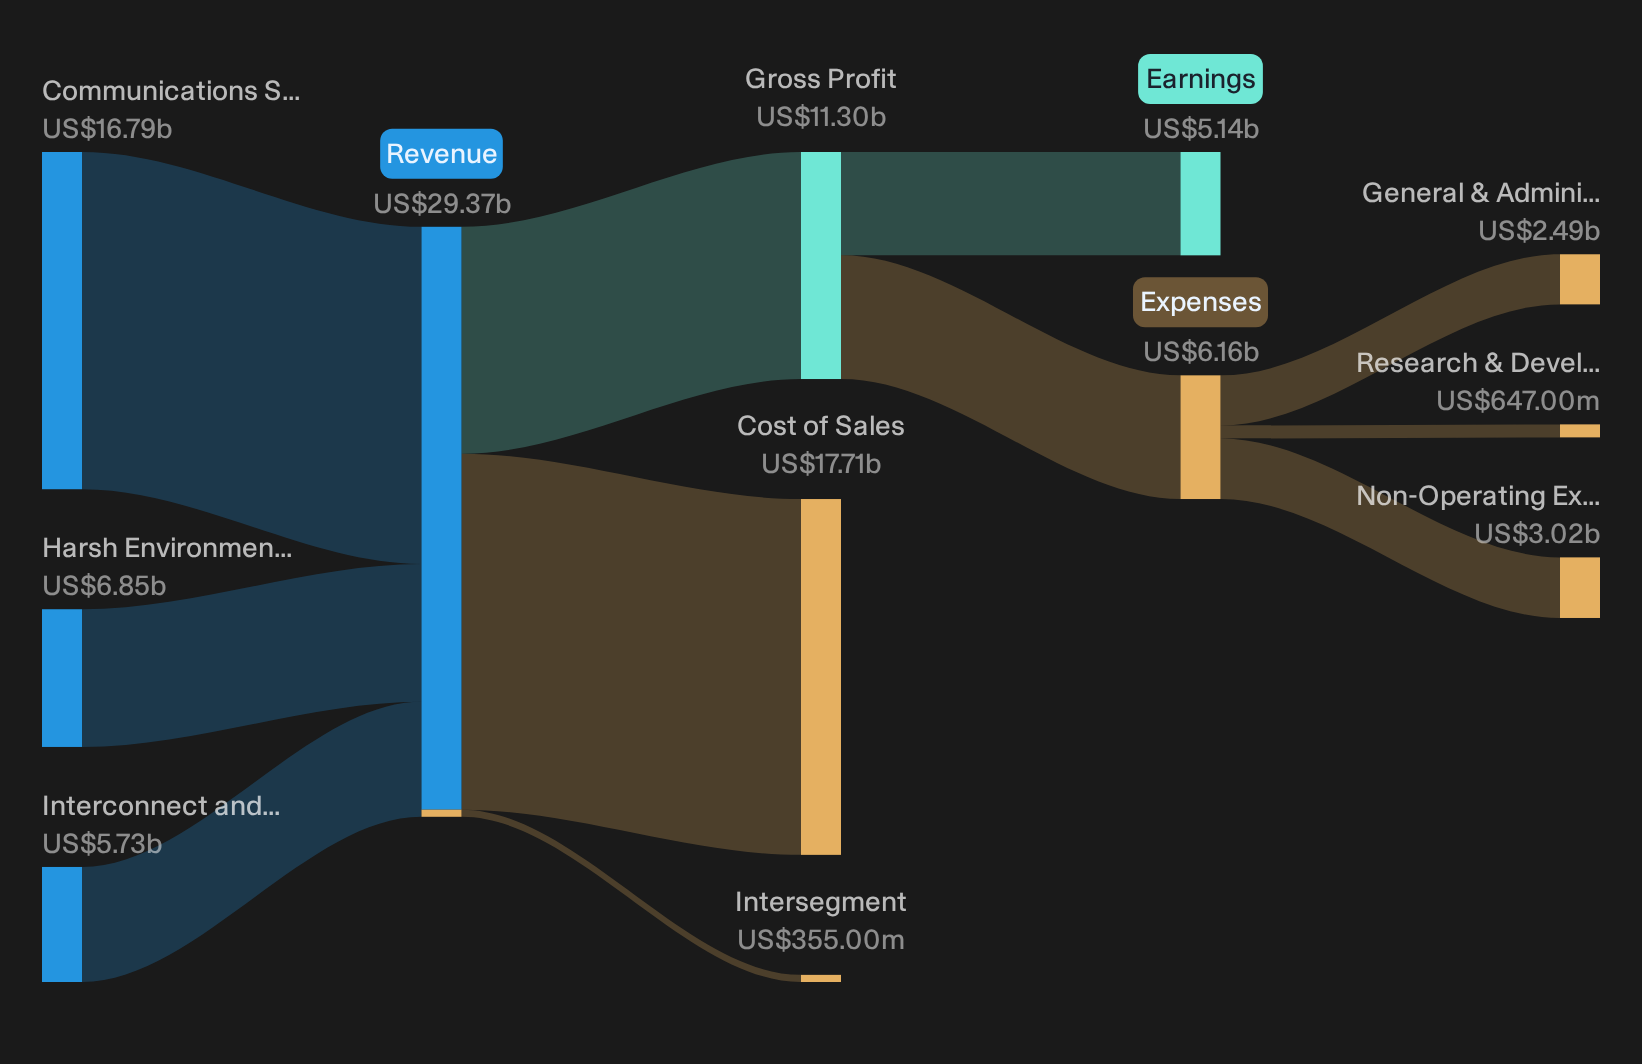
Amphenol generates most of its sales from Communications Solutions at about US$16.8b, with Harsh Environment Solutions adding roughly US$6.9b and Interconnect and Sensor Systems around US$5.7b, supporting a US$185.6b market value that firmly places the group in large-cap territory.
"With data centers facing much more demand than supply, it appears that Amphenol's technology has a bright future ahead of it."
What really moves the needle from here is how one pressure point in its biggest connectivity market shapes pricing power and long-term earnings quality.
That hinge point is exactly what the full narrative for Amphenol unpacks, separating cyclical noise from where Amphenol’s earnings power and valuation story could be quietly accelerating next.
Shopify (SHOP)
Shopify fits this rate-sensitive growth screen as a large-cap commerce software platform, generating about US$13.3b from Internet Software & Services and a market value near US$216.4b, so future cash-flow expectations matter when you weigh shifts in Fed policy and discount rates.
Shopify powers merchants across online, in-store, and social channels, helping them manage inventory, payments, shipping, and customer relationships, which ties its long-duration growth story closely to the kind of higher-volatility, interest-rate-aware profile this screener targets.
"By expanding its role behind the scenes, Shopify increases switching costs. Merchants are less likely to leave a platform that handles payments, inventory, analytics, and customer identity."
What happens to that grip on merchant economics if a single assumption about how quickly those services scale into stronger profitability breaks?
If that assumption matters to you, read the full narrative for Shopify to see where Shopify’s pricing power, risk and long-term cash flows could be decoupling from rate moves.

Seeking Fresh Alternatives Before Others?
Fresh ideas move first, and slower money often gets caught chasing momentum once prices are already flying. Scan for potential breakouts while it matters, before the crowd, and act now.
- Spot potential turnarounds early by scanning 29 high quality undervalued stocks that combine solid financial footing with room for sentiment to shift before prices start breaking away from current levels.
- Target future-facing themes by reviewing 25 quantum computing stocks that sit at the intersection of cutting-edge computing and real commercial use cases while they are still under the radar for now.
- Lean into long-term income potential by reviewing 5 dividend fortresses that aim to keep payouts flowing even when conditions turn tougher, so you are not chasing yield after it drops.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com