


EN
Is Ryohin Keikaku (TSE:7453) Expensive On Its Dividend Reset And New Earnings Outlook?
Ryohin Keikaku (TSE:7453) drew fresh attention after the board proposed a year-end dividend of ¥22 per share for FY26/8, along with new dividend and earnings guidance for the coming year.
Investors have already been reacting to this clearer payout and earnings roadmap from Ryohin Keikaku, with the share price at ¥4,730 after a 17.28% one-month share price return and a year-to-date share price gain of 65.96%. The three-year total shareholder return of very roughly 4x suggests that the longer-term trend has been much stronger than recent short-term moves might imply.
Scan how Ryohin Keikaku’s dividend reset compares with other companies that combine shareholder payouts with growth potential using our hand picked 16 high quality undervalued stocks.
After a share price move of this size and a richer dividend profile, the real issue for Ryohin Keikaku now is whether the current valuation still compensates buyers for the risks they are taking.
Preferred P/E of 32.9x: Is it justified?
Ryohin Keikaku now trades on a P/E of 32.9x, which sits against a last close of ¥4,730 and a forecast earnings growth rate of 8.44% per year.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors are paying for current profit. For a retailer like Ryohin Keikaku, it is a blunt but useful way to see how much of the recent earnings momentum and dividend reset is already reflected in the valuation.
On the quality side of the ledger, earnings grew 50.3% over the past year and have grown 23.9% per year over the past five years, with margins moving from 6.5% to 8.3%. That is a solid profit profile. The business is expected to keep growing earnings at 8.44% per year, while revenue is projected to rise 8.3% per year, which is faster than the 6.5% revenue growth forecast for the broader JP market. Even so, the current 32.9x P/E is described as expensive versus an estimated fair P/E of 21.8x. This is a level the market could eventually gravitate toward if expectations cool.
The comparison with peers is even starker. The same 32.9x P/E is flagged as expensive versus both the peer average of 19.1x and the JP Multiline Retail industry average of 16.5x. That means investors are paying a much richer entry price for Ryohin Keikaku than for similar retailers in Japan, despite earnings growth that is forecast to be slower than the wider JP market at 9.5% per year.
Explore the SWS fair ratio for Ryohin Keikaku.
Result: Price-to-earnings of 32.9x (OVERVALUED)
Still, Ryohin Keikaku carries two clear pressure points for this richer valuation: any stumble in earnings delivery and a shift in investor sentiment toward lower growth retailers.
Find out about the key risks to this Ryohin Keikaku narrative.
Another view on Ryohin Keikaku’s value
There is a second lens on Ryohin Keikaku that does not rely on the current 32.9x P/E. The SWS DCF model values future cash flows at ¥2,695.78 per share, which is below the ¥4,730 market price and points to an overvalued picture instead. Which signal do you treat as the primary anchor?
Look into how the SWS DCF model arrives at its fair value.
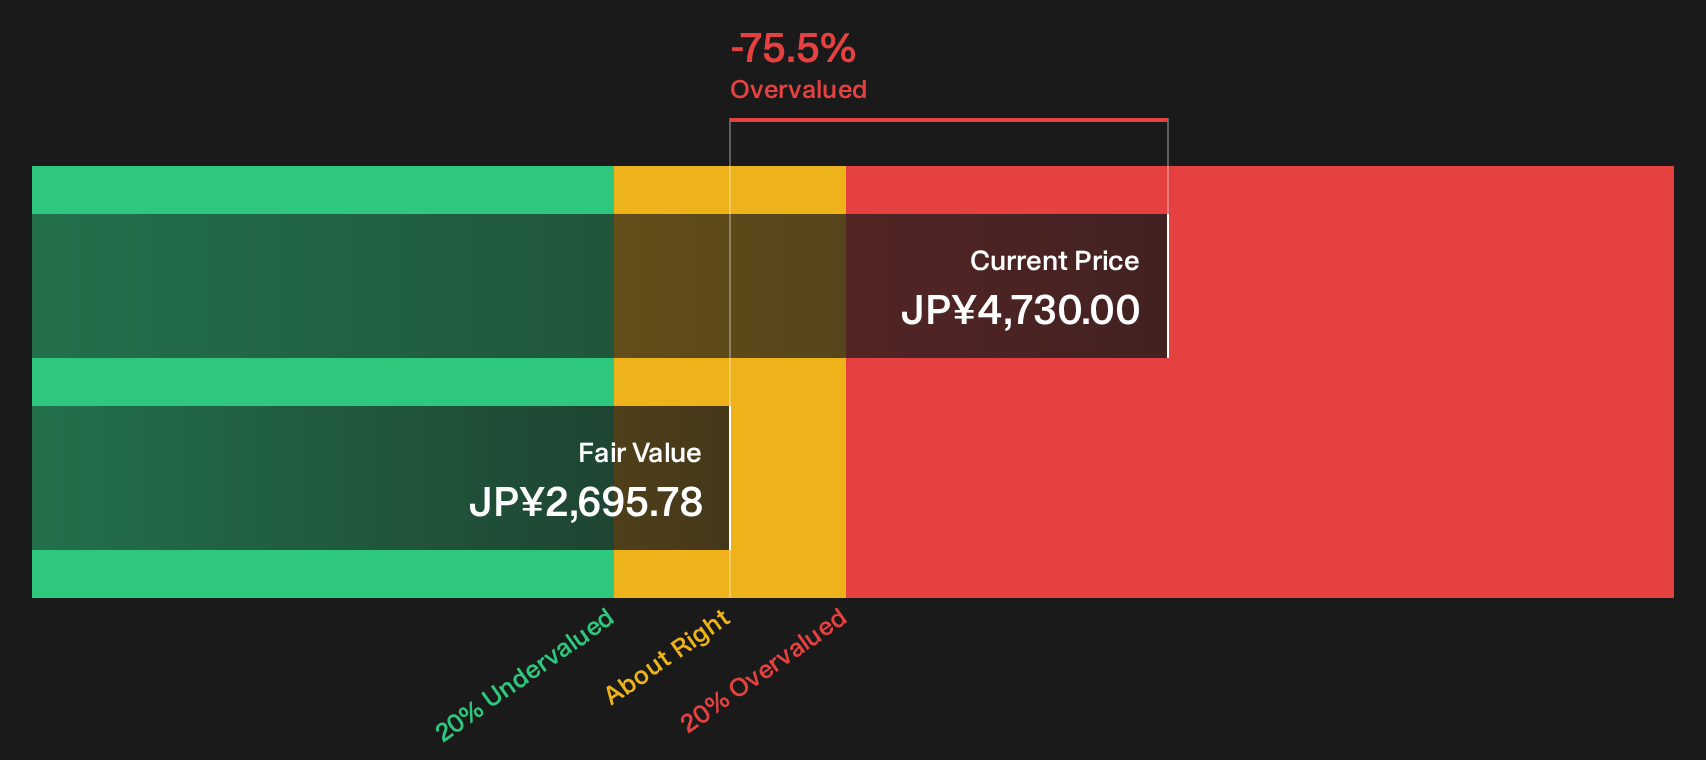
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ryohin Keikaku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the cautious tone on valuation match your own read on Ryohin Keikaku? Act quickly and stress test the upside case against the 2 key rewards
Looking for more investment ideas beyond Ryohin Keikaku?
If Ryohin Keikaku has sharpened your focus on quality and price, you may want to broaden your watchlist. Other opportunities can move before headlines catch up.
- Explore potential upside in smaller names by scanning a focused universe of 1 elite penny stocks with strong financials that already show stronger balance sheets and cash profiles than many expect.
- Prioritise resilience and build a shortlist from a 22 resilient stocks with low risk scores that filters for businesses with steadier fundamentals and lower overall risk scores.
- Look for tomorrow’s potential leaders early by working through a 72 high quality undiscovered gems that highlights quality fundamentals before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com