


EN
Is Ryman Hospitality Properties (RHP) Undervalued On New Solar Efficiency And Cash Flow Optimism?
The new rooftop solar installation at Gaylord National Resort puts energy efficiency and resiliency in focus for Ryman Hospitality Properties (RHP), giving investors fresh context for weighing cash flow and long term valuation expectations.
Recent price action backs up that story. Ryman Hospitality Properties has logged a 30 day share price return of 8.9%, while the year to date share price return of 38.53% and 1 year total shareholder return of 59.96% suggest that momentum has been building rather than fading.
Scan other hospitality and real estate operators that show similar cash flow momentum and asset intensity by reviewing our curated list of 29 high quality undervalued stocks.
Ryman Hospitality Properties now pairs sizable convention assets with fresh energy investments and a strong recent share run. The business looks robust. The open question is whether the current price fairly reflects that strength.
Most Popular Narrative: 5% Undervalued
Against the last close of $132.27, the most followed valuation story for Ryman Hospitality Properties points to a fair value of $139.79, which frames recent share gains as only part of a larger rerating debate.
Recent acquisitions and ongoing capital investments, now including the approximately US$1.38b Grande Lakes Orlando transaction alongside projects like meeting space upgrades at Gaylord properties and resort enhancements, extend the earlier thesis that Ryman Hospitality Properties can benefit from renewed appetite for large scale experiential travel and gatherings by adding more room, meeting and amenity capacity that can support revenue growth and future cash flow.
See why 7 investors see Ryman Hospitality Properties as 5% undervalued.
Result: Fair Value of $139.79 (UNDERVALUED)
Still, the bullish Ryman Hospitality Properties narrative only holds if heavy spending at Grande Lakes Orlando and higher 2026 capex do not squeeze cash generation or dividend flexibility.
Find out about the key risks to this Ryman Hospitality Properties narrative.
Another View: What Ryman Hospitality Properties’ P/E Is Telling You
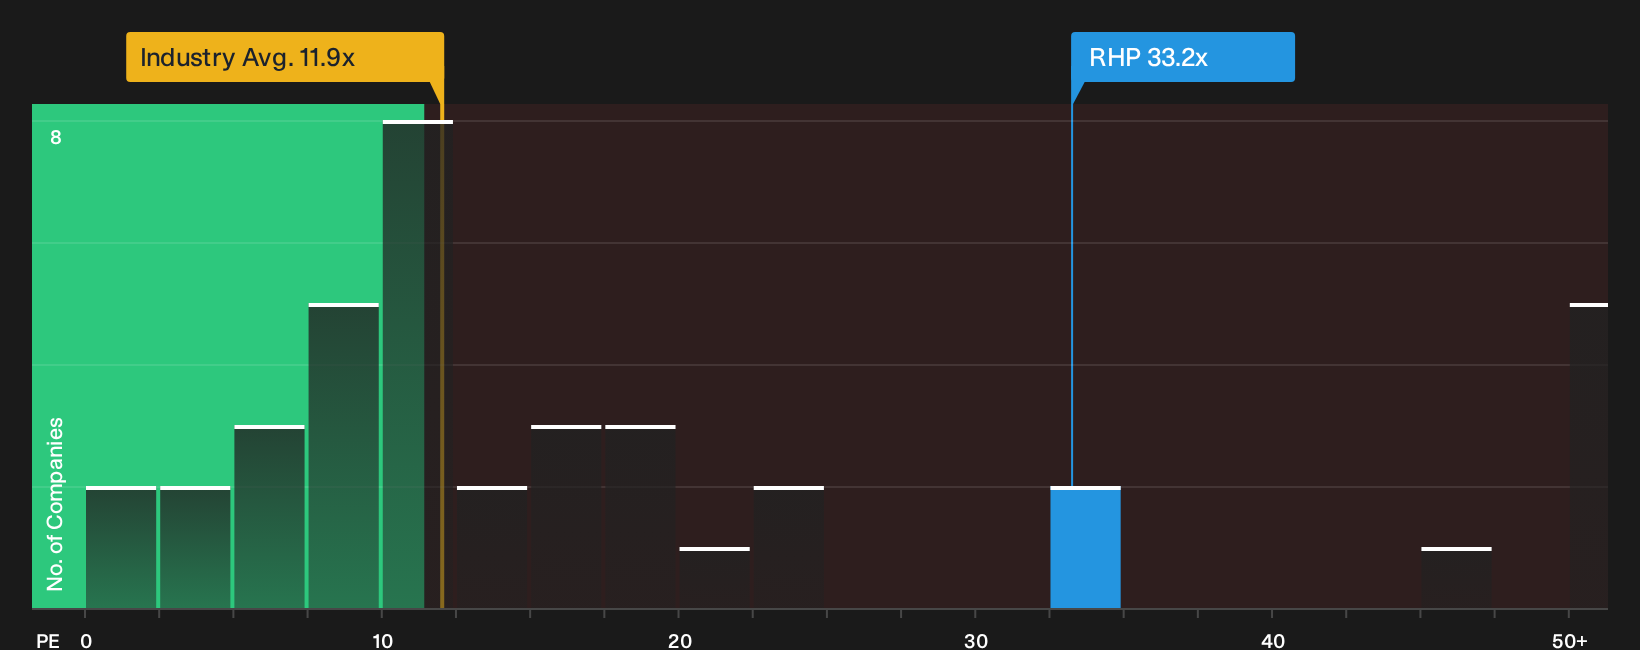
The story looks different when the focus shifts to the P/E ratio. Ryman Hospitality Properties trades on 33.2x earnings, compared with 12.1x for the global Hotel and Resort REITs group and 29.5x for its peers. The fair ratio is 39.7x, which leaves some room but also raises the question of how much optimism is already in the price.
To pressure test that earnings multiple against detailed valuation work, investors can review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or early conviction? If Ryman Hospitality Properties has both worries and bright spots, move quickly and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ryman Hospitality Properties?
If Ryman Hospitality Properties has sharpened your focus, do not stop here. Use Simply Wall Street screeners to uncover fresh opportunities that match your investing style.
- Focus on stability by reviewing companies with stronger balance sheets and fundamentals through our list of solid balance sheet and fundamentals (24 results).
- Look for potential mispricings by scanning a curated set of businesses screened as 29 high quality undervalued stocks.
- Explore cash-focused opportunities by assessing companies screened as 5 dividend fortresses that prioritize income potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com