


EN
Credicorp (BAP) Nears Earnings As Its Digital Story Meets An Undervalued View
Why Credicorp’s Upcoming Earnings Matter Now
Credicorp (NYSE:BAP) has put a firm date on its next checkpoint. Third quarter 2026 results are due after the close on November 9, with management hosting a webcast the following day.
The scheduled release and call give you a near term look at how this Peru focused financial group is running its banking, insurance, and microfinance operations across the region.
Recent trading has cooled after a strong run, with Credicorp’s share price slipping 2.34% over the last session and 6.47% over the week. However, the year-to-date share price return of 27.54% and a 1-year total shareholder return of 47.12% indicate that longer-term momentum remains intact.
Scan beyond Credicorp and see how it compares with other regional financial stocks showing solid fundamentals in our hand picked list of solid balance sheet and fundamentals (24 results).
After a 47.12% total return over the past year and a recent pullback, Credicorp now forces a simple question: Is meaningful upside still ahead, or has most of the easy gain already passed?
Most Popular Narrative: 15% Undervalued
At a last close of $365.28 against a narrative fair value of $427.48, Credicorp is framed as materially undervalued, with that gap hinging on how far its digital and lending engines can run.
Expansion of Credicorp’s digital financial services like Yape is now tied to a much larger base of more than 16 million monthly active users who transact frequently and already contribute close to 10% of risk adjusted revenues. Further product roll out and higher revenue per user could potentially lift fee income and earnings.
See why 14 investors see Credicorp as 15% undervalued.
Result: Fair Value of $427.48 (UNDERVALUED)
Still, Credicorp’s heavy Peru exposure and the flagged El Niño risk, which affects around 9% of its loan book, could quickly challenge this 15% undervalued narrative.
Find out about the key risks to this Credicorp narrative.
Another View: What Credicorp’s P/E Is Telling You
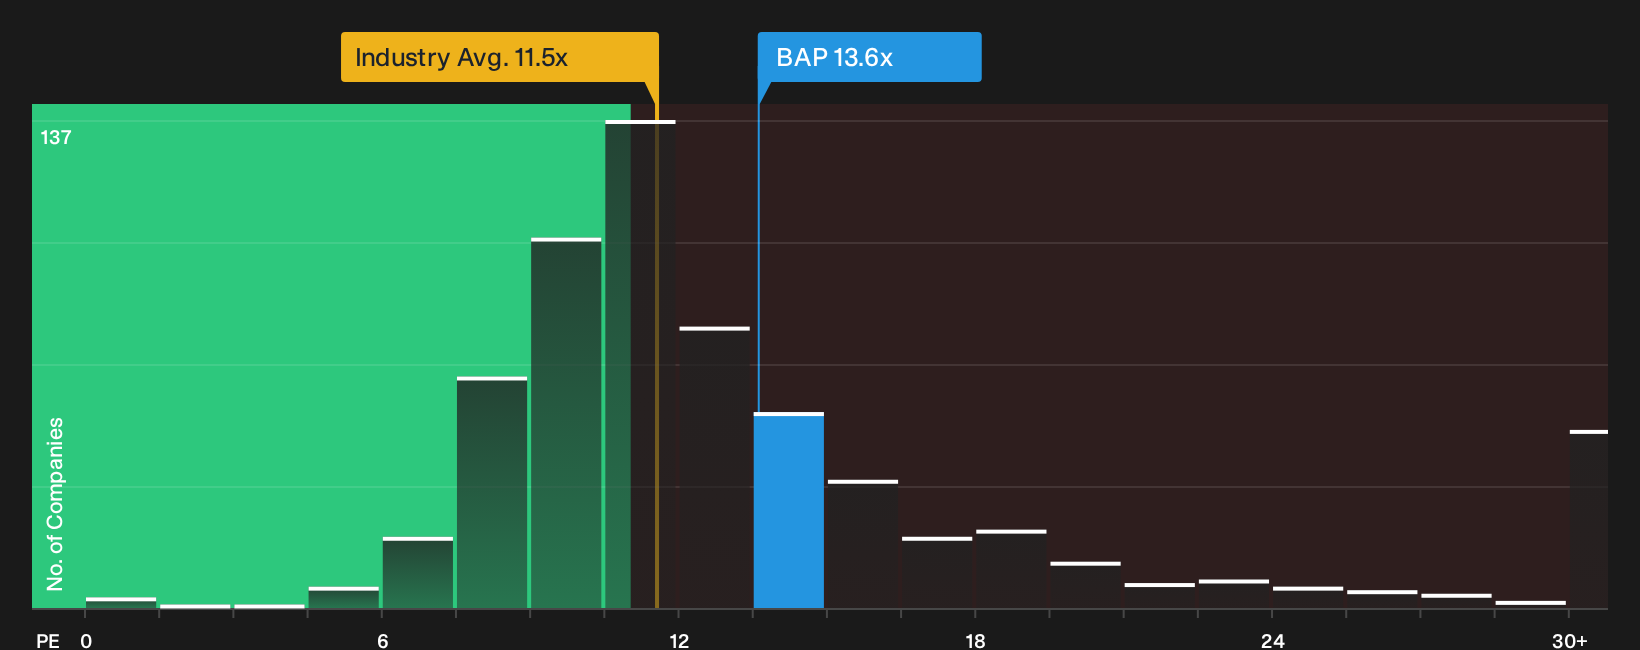
The SWS DCF model suggests Credicorp is trading below an estimated future cash flow value of $485, yet the P/E story points in a different direction. At 13.6x earnings versus 11.5x for US banks and a 14.9x fair ratio, this raises the question: is there a cushion for new buyers, or a potential trap?
To see how this earnings multiple could adjust over time and what that might mean in practice for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Credicorp’s risk and reward balance can create noise, so review the same numbers analysts are watching and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Credicorp?
If Credicorp has your attention, do not stop here. The same tools that surface its opportunity can spotlight other ideas that might suit your portfolio.
- Target cash generative opportunities with healthier valuations by scanning our curated pool of 29 high quality undervalued stocks that already screen well on fundamentals.
- Strengthen your income stream by reviewing 5 dividend fortresses built around higher yielding payers with support from their financial profiles.
- Dial down portfolio risk by filtering for 30 resilient stocks with low risk scores that combine sturdier balance sheets with more resilient business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com