


EN
Dear Chipotle Stock Fans, Mark Your Calendars for October 28
Upcoming quarterly reports in the fast-casual dining industry serve as a crucial barometer for broader consumer spending habits and margin resilience amid persistent labor and input inflation. Investors closely monitor transaction volume trends, menu pricing power, and store-expansion efficiency to evaluate if operational growth can sustain elevated market valuations.
Highlighting these key industry metrics, Chipotle Mexican Grill (CMG) is set to report its third-quarter financial results on Oct. 28 at 4:30 p.m. ET.
About Chipotle Mexican Grill
Chipotle Mexican Grill is a leading fast-casual restaurant chain specializing in Mexican-inspired food, including burritos, tacos, bowls, and salads. The company emphasizes responsibly sourced ingredients, customizable meals, and digital ordering. With more than 4,200 restaurants, Chipotle is focused on restaurant expansion, operational efficiency, and customer experience to strengthen its position in the competitive fast-casual dining market.
CMG Shares Slide Ahead of Q3 Earnings
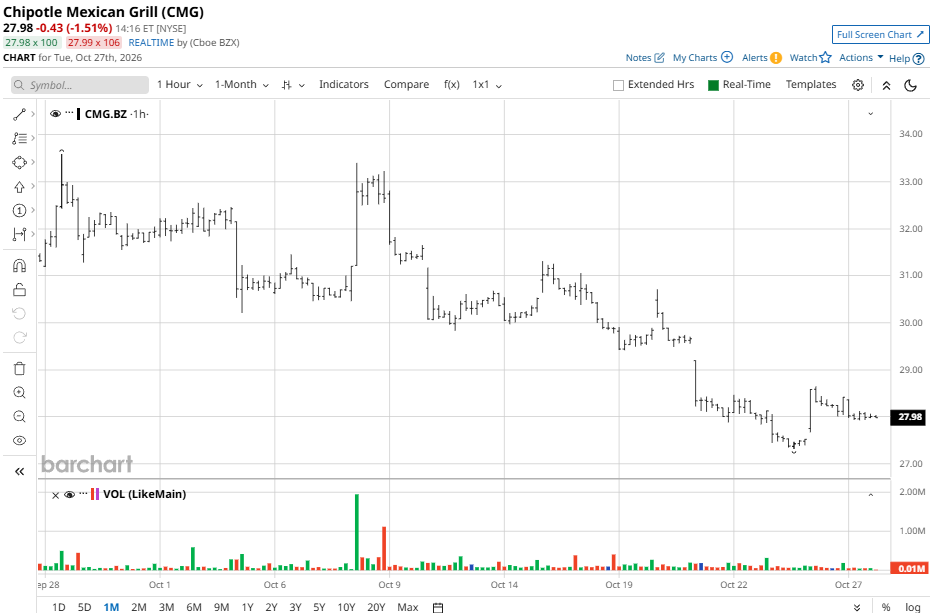
Chipotle's stock has faced mounting pressure in 2026 as investors assess slowing restaurant traffic, rising operating expenses and uncertainty surrounding consumer spending. CMG shares have fallen approximately 23% year-to-date (YTD), underperforming the broader stock market. The decline intensified in October, with shares approaching a new 52-week low ahead of the company's fiscal third-quarter earnings announcement scheduled for Oct. 28.
Looking at Chipotle’s Previous Quarterly Result
Chipotle Mexican Grill’s second-quarter 2026 revenue of $3.35 billion, up 9.3% year-over-year (YoY), surpassing analyst expectations of approximately $3.33 billion. Adjusted earnings per share (EPS) came in at $0.33, slightly above the consensus estimate of $0.32, while reported diluted EPS remained at $0.32. The results reflected continued restaurant expansion and improving comparable sales, although profitability remained under pressure from higher operating expenses.
Chipotle's comparable restaurant sales increased 2.2%, supported by a 1.2% improvement in average check and a 1.0% increase in transactions. Digital sales accounted for 38.3% of food and beverage revenue, compared with 35.5% a year earlier. However, the operating margin contracted to 15.7% from 18.2%, while the restaurant-level operating margin fell to 25.2% from 27.4%. Higher beef, freight, labor, and produce costs contributed to the margin pressure. Chipotle opened 100 company-operated restaurants during the quarter, including 80 locations featuring its Chipotlane drive-through pickup format, reinforcing its expansion strategy despite rising expenses.
Looking ahead, Chipotle management raised its full-year 2026 comparable restaurant sales outlook to growth in the low-single-digit range, reflecting improving sales momentum. The company expects to open between 350 and 370 restaurants during the year, including 10 to 15 international partner-operated locations, with approximately 80% of new company-operated restaurants featuring Chipotlanes.
Q3 Earnings Preview
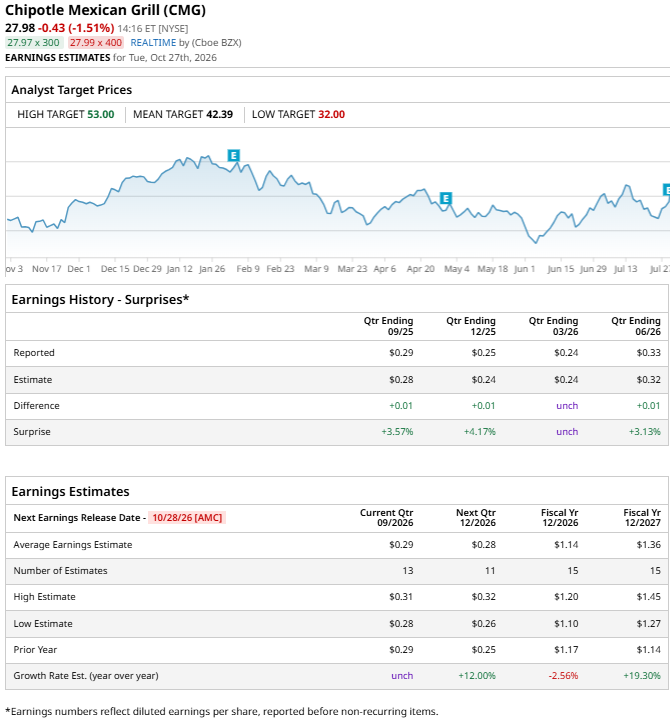
Chipotle Mexican Grill is expected to report earnings per share EPS of $0.29, according to estimates from 13 analysts. Forecasts range from a low of $0.28 to a high of $0.31, matching the prior-year EPS of $0.29. Investors will closely monitor the company's earnings performance for signs of improving profitability amid persistent food, labor, and operating cost pressures.
For fiscal 2026, analysts project average EPS of $1.14, based on estimates from 15 analysts, with forecasts ranging between $1.10 and $1.20. The annual estimate compares with prior-year earnings of $1.17, suggesting a modest decline in expected profitability. Chipotle's ability to sustain comparable restaurant sales growth, manage expenses, and maintain customer traffic will remain key factors influencing its earnings outlook.
Should You Buy CMG Stock Ahead of Earnings?
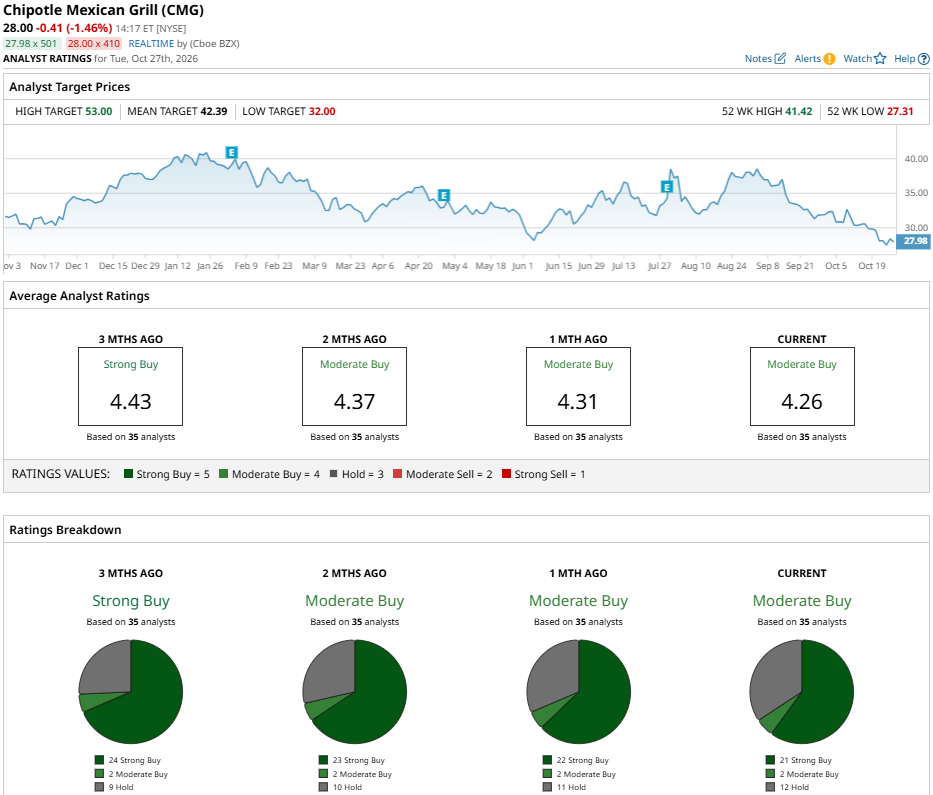
Chipotle Mexican Grill presents a mixed investment outlook, with analysts expecting fiscal 2026 EPS of $1.14, below the prior year's $1.17. However, Wall Street maintains a “Moderate Buy” consensus rating, with a mean price target of $42.39, implying approximately 51% upside from the current market price. Across 35 analyst ratings, 21 are “Strong Buy,” two are “Moderate Buy,” and 12 are “Hold.” Investors should weigh this potential upside against food and labor cost pressures, sales growth, and Chipotle's ability to protect margins before making an investment decision.
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.