


EN
Medtronic's Q2 2027 Earnings: What to Expect
Galway, Ireland-based Medtronic plc (MDT) develops, manufactures, and sells device-based medical therapies to healthcare systems, physicians, clinicians, and patients. Valued at $121.2 billion by market cap, the company's principal products include those for bradycardia pacing, tachyarrhythmia management, atrial fibrillation management, heart failure management, heart valve replacement, malignant and non-malignant pain, and movement disorders. The medical devices giant is expected to announce its fiscal second-quarter earnings for 2027 in the near term.
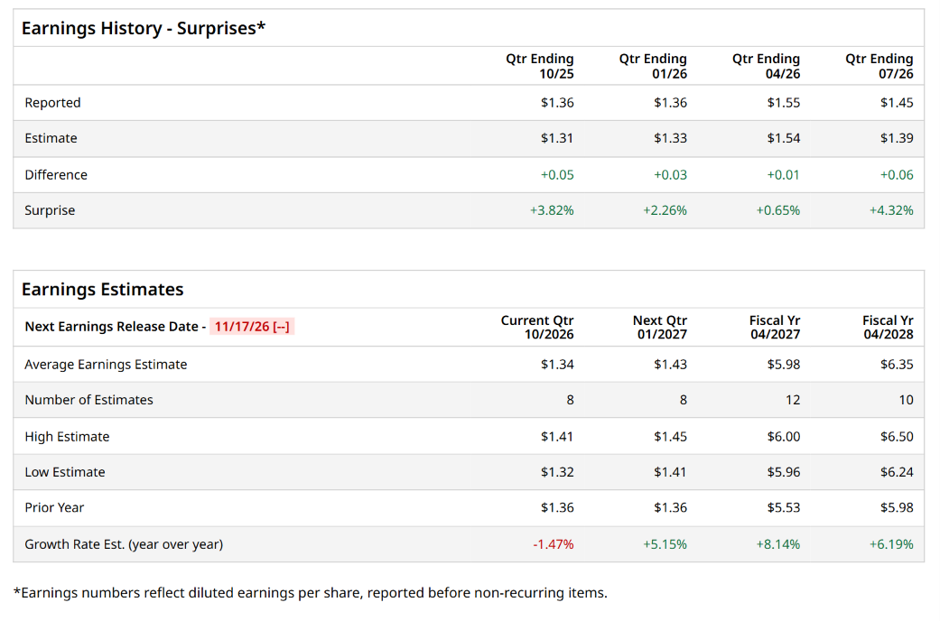
Ahead of the event, analysts expect Medtronic to report a profit of $1.34 per share on a diluted basis, down 1.5% from $1.36 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Medtronic to report EPS of $5.98, up 8.1% from $5.53 in fiscal 2026. Its EPS is expected to rise 6.2% year over year to $6.35 in fiscal 2028.
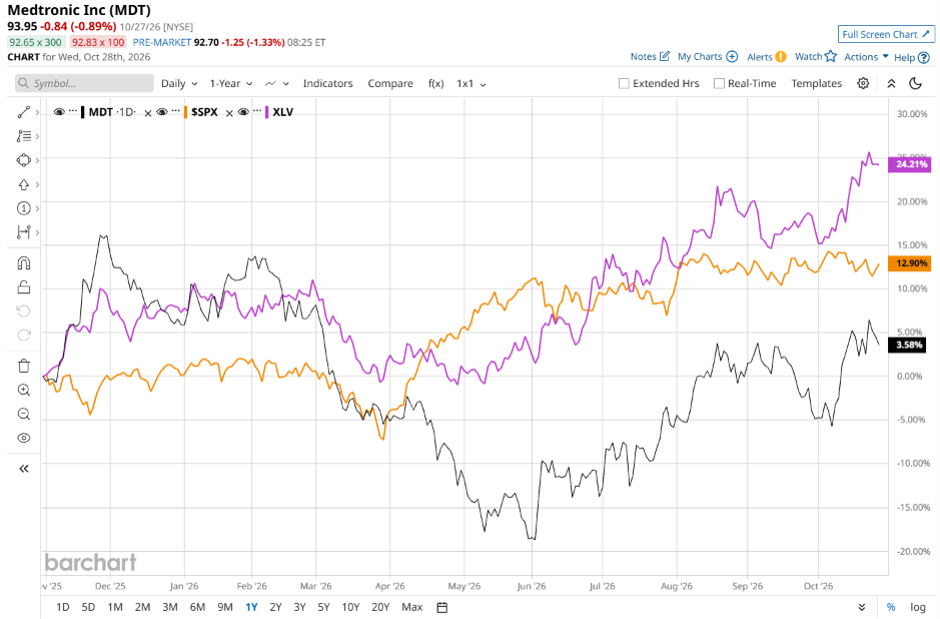
MDT stock has underperformed the S&P 500 Index’s ($SPX) 12.3% gains over the past 52 weeks, with shares down marginally during this period. Similarly, it underperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 22.4% returns over the same time frame.
Medtronic’s relative underperformance has been driven by sluggish organic growth acceleration compared to high-flying sectors, alongside ongoing pressures from supply chain bottlenecks, higher operational costs, and intense competitive headwinds in areas like surgical robotics and diabetes. Additionally, investor sentiment has been weighed down by margin compression concerns, structural portfolio changes, such as its diabetes unit spin-off preparations, and a broader rotation of capital away from traditional medtech toward high-growth technology and AI themes.
On Sep. 1, MDT shares closed up by 1.5% after reporting its Q1 results. Its adjusted EPS of $1.45 beat Wall Street expectations of $1.39. The company’s revenue was $9.8 billion, topping Wall Street forecasts of $9.5 billion. Medtronic expects full-year adjusted EPS in the range of $5.94 to $6.
Analysts’ consensus opinion on MDT stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 29 analysts covering the stock, 14 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” and 13 give a “Hold.” MDT’s average analyst price target is $102.65, indicating a potential upside of 9.3% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.