


EN
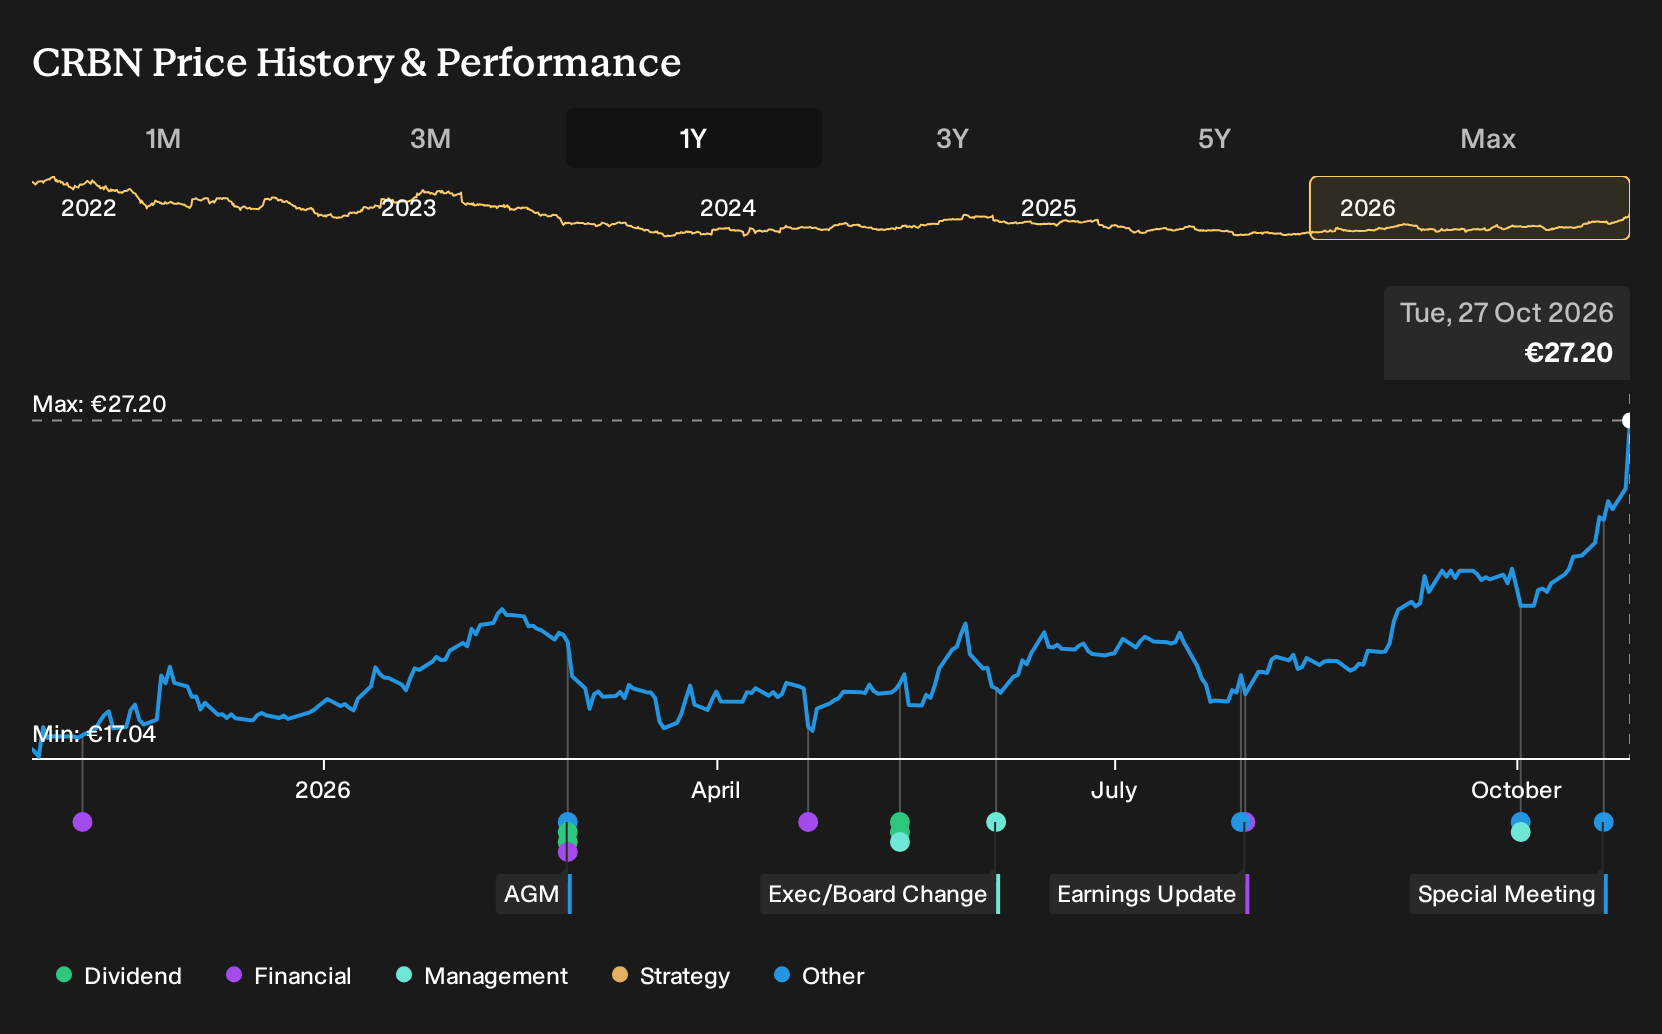
Corbion Stock Sales Growth Keeps PLA Business In Focus
- Corbion reported strong organic sales growth in Q3 2026, with positive volume and mix in both Functional Ingredients & Solutions and Health & Nutrition, and chose to retain its PLA business after divestment proposals fell short of management’s view of its value.
- The decision to keep and further develop the PLA unit keeps Corbion’s exposure to biomaterials intact, while reaffirmed 2026 guidance signals confidence in current demand and the existing order book.
- We will look at how Corbion’s strong organic sales and decision to retain its PLA business could reshape the investment narrative.
Scan how Corbion’s Q3 momentum and biomaterials exposure compare with other potential opportunities by reviewing our hand picked 610 high quality undiscovered gems in similar niches.
Corbion Investment Narrative Recap
To own Corbion, you need to trust the long term shift toward lactic acid based ingredients, algae omega 3 and biomaterials, and that higher value specialties can support earnings despite cost noise. The Q3 update, with strong organic sales and maintained 2026 guidance, points to a steady operating backdrop rather than a step change.
The key short term swing factor remains execution on mix and pricing while sulfuric acid, energy and freight costs stay unpredictable. The main risk still comes from end markets like semiconductors, agrochemicals and animal feed, where extended weak demand or tighter regulation could blunt volume momentum in both reporting segments.
The most relevant piece of news around this earnings call is Corbion’s decision to keep the PLA unit after receiving offers that did not match management’s view of its value. That choice links directly to the existing biomaterials thesis, where PLA and the Thai lactic acid plant are part of the same broader capacity and cost story.
Retaining PLA keeps exposure to pricing in that market, including the earlier concern about low PLA prices and Asian demand concentration. It also means more execution risk and capital tied to a segment where margins were 7.5% in the first half of 2026. Investors now have a clearer, more committed biomaterials profile to factor into their catalyst and risk map.
Corbion's current analyst narrative points to €1.4b in revenue and €112.7 million in earnings by 2029, based on assumed yearly revenue growth of 4.9% and an earnings increase of about €50.5 million from €62.2 million today.
Uncover why Corbion's fair value indicates a 14% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
Some of the lowest Corbion forecasts focus on a very different catalyst: the hoped for PLA exit. Those analysts were working with revenue expectations of about €1.3b and earnings of roughly €99.4 million by 2029, and saw limited upside at a 13.7x P/E. The Q3 decision to keep PLA could push that story to evolve.
Explore 4 other Corbion fair value estimates, including one that suggests as much as 28% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Corbion research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Corbion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Corbion's overall financial position at a glance.
Looking for more Corbion style investment ideas?
If Corbion’s mix of specialty ingredients and biomaterials appeals to you, it can help to broaden your watchlist with other businesses that share similar qualities in resilience, pricing power, or balance sheet strength.
The Simply Wall St Screener lets you filter for these traits directly so you are not just reacting to headlines but comparing Corbion with a wider set of potential candidates.
- If you care most about quality at a reasonable price, scan for companies that combine solid fundamentals with room for re rating using our 195 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, shortlist businesses that carry lower financial risk with the help of the list of solid balance sheet and fundamentals (207 results).
- If you prefer to focus on resilience and lower volatility, build a watchlist of steadier performers by running the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com