


EN
Copa Holdings (CPA) Stock May Be Undervalued On Earnings Power
Copa Holdings has delivered a long run of strong share returns, and that track record naturally raises a question about what investors are paying for its earnings today. With the stock most recently closing at US$132.18, the issue for you is whether that price still lines up with the profits the airline group is generating.
- Over the past 5 years, Copa Holdings has returned 118.0%, which puts a lot of weight on whether its current earnings power can support that kind of journey so far.
- The business model is tightly focused on Latin American air travel and relies heavily on filling planes efficiently. That can influence margins, cash generation and how much of its profit ultimately supports the equity value.
- There is a second opinion on Copa Holdings worth weighing. See what analysts think Copa Holdings's shares could be worth.
The issue now is whether Copa Holdings' recent share price, including an 8.5% gain year to date and 12.3% over the past year alongside shorter term declines of 2.2% over the last week and 1.2% over the past month, is adequately backed by the earnings that investors are paying for.
If you are weighing whether Copa Holdings' current P/E is reasonable for its earnings profile, it can help to set it alongside a wider field using 29 high quality undervalued stocks.
Does Copa Holdings Look Undervalued on Earnings?
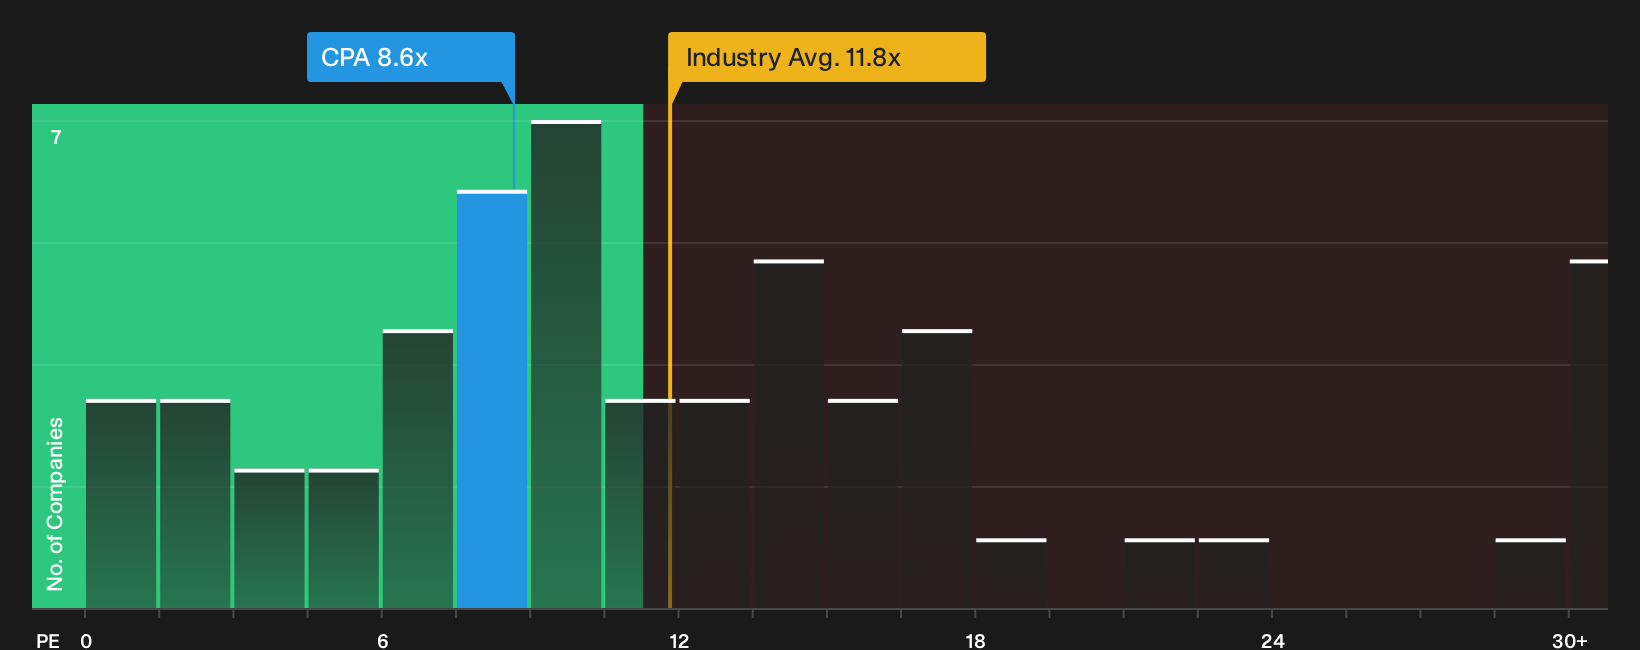
The P/E ratio fits Copa Holdings well because earnings are a key lens for an airline that already reports positive profits. On this measure, the stock trades at about 8.6x earnings, which is below both the airlines sector average of roughly 11.8x and a peer group closer to 13.0x. That places Copa in the cheaper half of its industry on this single metric, despite its focus on Latin American routes.
The fair P/E that would be expected once Copa Holdings' growth outlook, profitability profile, size and risk are plugged into the model comes out higher than where the shares change hands today. As a result, the current 8.6x screens as undervalued against that yardstick. For a holder, the key question is whether the business can keep generating the level of earnings that this discount implies the market is sceptical about, or whether that gap closes in the other direction over time. Explore the numbers behind Copa Holdings's P/E valuation.
The Copa Holdings Narrative: What Would Justify Today's Price?
Narratives for Copa Holdings pick up where the P/E puzzle leaves off, by spelling out what kind of future for growth, profit margins and earnings would need to play out for the stock to be worth materially more or less than today. Rather than lean on a single multiple or model point estimate, each narrative lays out the set of assumptions behind its view of fair value so you can compare those expectations with the actual results as they are reported.
One of the top community narratives on Copa Holdings: 26% undervalued
"Expansion of Copa Holdings' Hub of the Americas through high teens capacity growth, new destinations and the planned move from 6 to 8 daily connecting banks..."
Discover why this Narrative puts Copa Holdings at 26% undervalued.
One more piece of the Copa Holdings puzzle worth checking
Everything covered so far looks at where Copa Holdings trades today. At the same time, professional coverage also maps out where earnings and profits are expected to land a few years from now. Explore where analysts expect Copa Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com