


EN
3 China Renewable Energy Stocks Trading Below Electrical Sector P E
China’s push to build out both giant renewable projects and old school oil and gas fields is reshaping where capital flows. You now have equipment makers, grid players, and upstream producers all touched by the same policy wave, yet in very different ways. This article walks through 3 stocks exposed to that news so you can identify where the risks and potential rewards are concentrating right now.
The three stocks below are only a first pass through China’s renewable equipment and infrastructure universe, and the full screen surfaced another 55 listed companies with equally detailed narratives that are not covered here.
If you want to identify patterns across the broader opportunity set and analyze which themes fit your own risk profile, head straight into the China Renewable Energy Equipment & Infrastructure screener.
Jinlei Technology (SZSE:300443)
Jinlei Technology is a CN¥5.35b wind equipment manufacturer that forges turbine main shafts and related castings and forgings for China’s large scale wind build out, while also supplying other power and heavy industry customers.
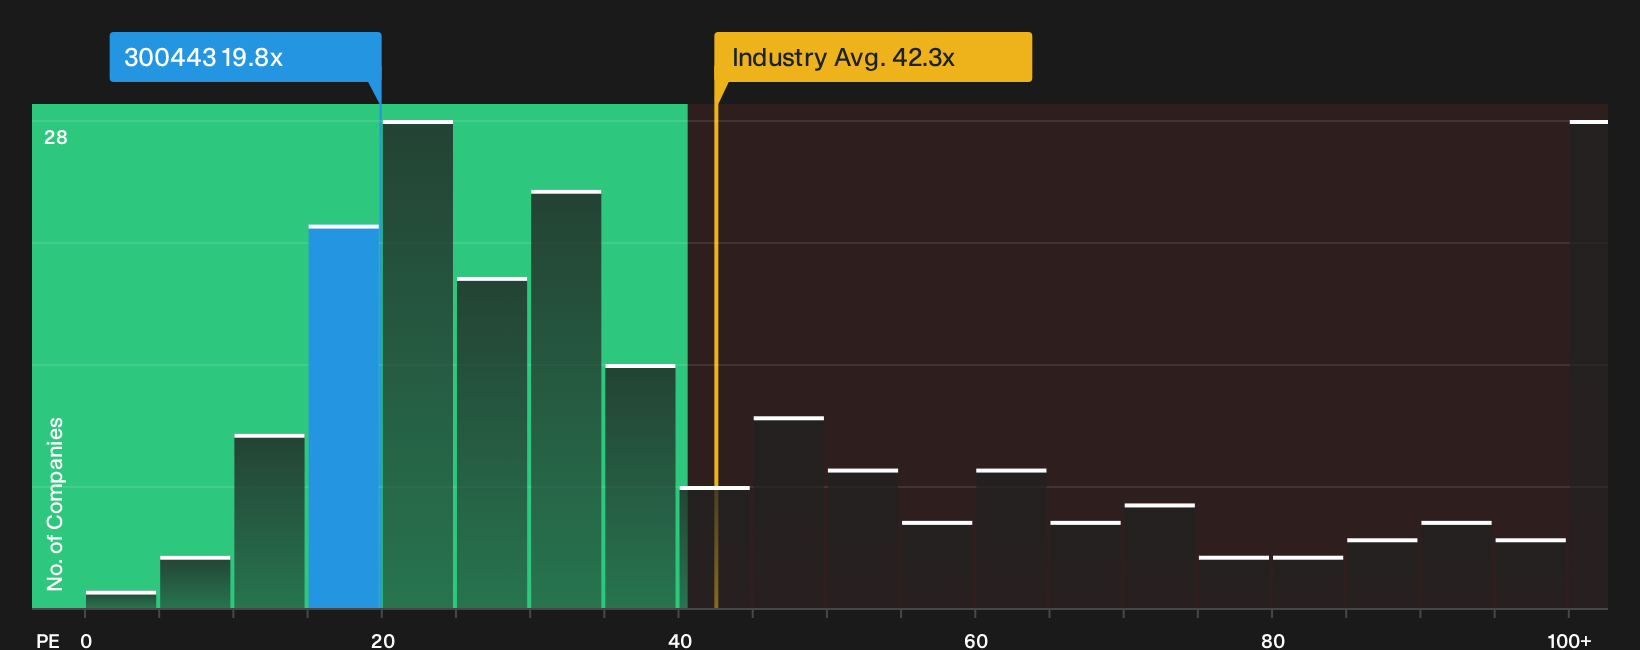
Jinlei Technology provides more focused equipment exposure to China’s wind capacity initiatives, since its forged main shafts sit inside the turbines required by this policy trend. The stock trades on a lower P/E than the broader electrical sector. Investor interest therefore largely hinges on how one unseen pressure inside the wind supply chain may influence future pricing power.
If that pressure point has your attention, view the 3 key rewards and 1 important warning sign to see whether pricing power risk is already baked into Jinlei Technology’s story.
Ginlong Technologies (SZSE:300763)
Ginlong Technologies is a pure-play solar PV string inverter supplier under the Solis brand, providing residential, commercial, utility scale and storage solutions that fit directly into China’s renewable equipment buildout. It generates about CN¥4.02b from overseas markets and roughly CN¥3.02b from mainland China, and the stock is valued around CN¥18.33b.
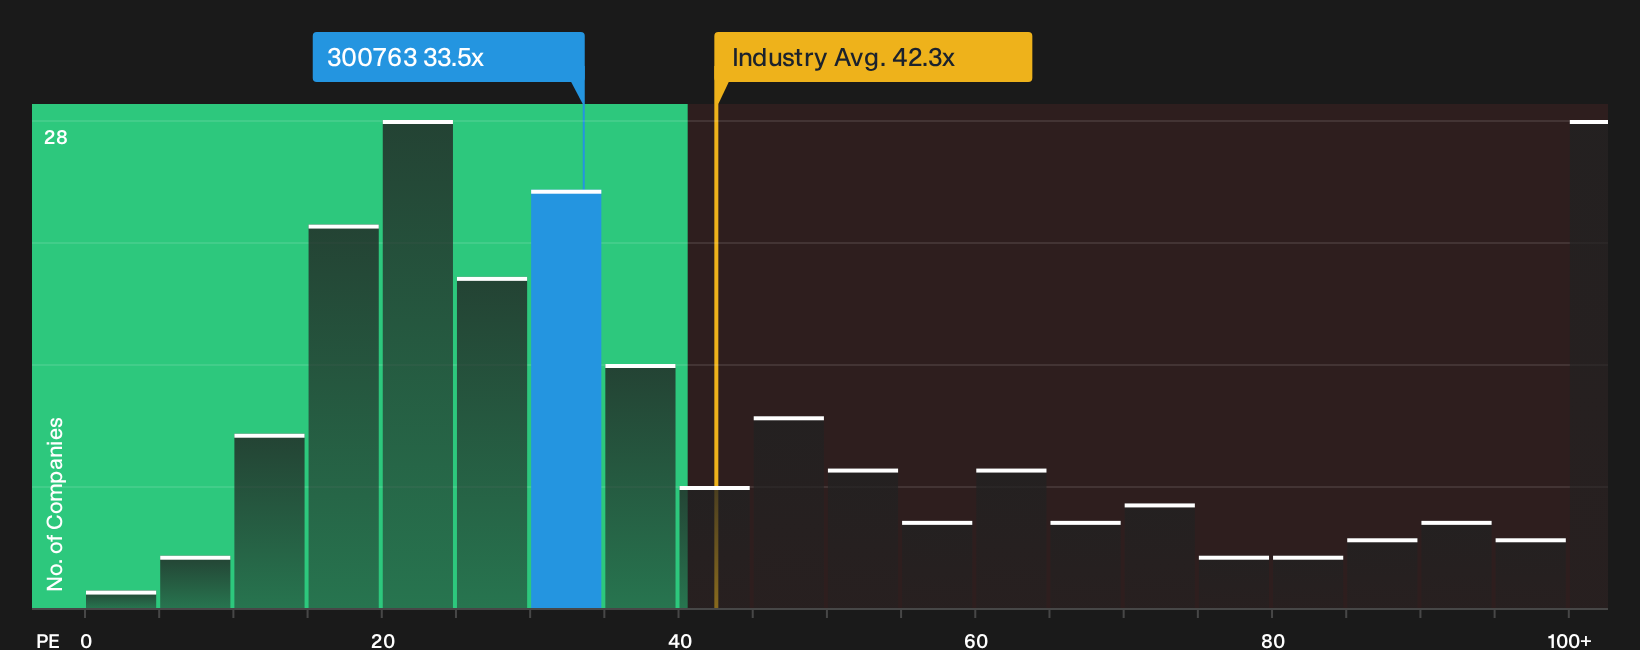
Ginlong Technologies provides exposure to the hardware that turns China’s large-scale solar rollout into usable power, from rooftops to utility fields. The P/E of 33.5x is below both the China market and domestic electrical peers, which keeps investor attention on what may happen if one pressure point in inverter profitability shifts again.
If inverter profitability is your swing factor here, review the 3 key rewards and 2 important warning signs to see what the current valuation might be masking.
Ningbo Deye Technology Group (SHSE:605117)
Ningbo Deye Technology Group is a CN¥86.61b solar equipment specialist that builds inverter systems, energy storage solutions, solar air conditioners and related power electronics, making it highly geared to China’s grid-connected PV buildout and broader push to plug more renewables into the power system.
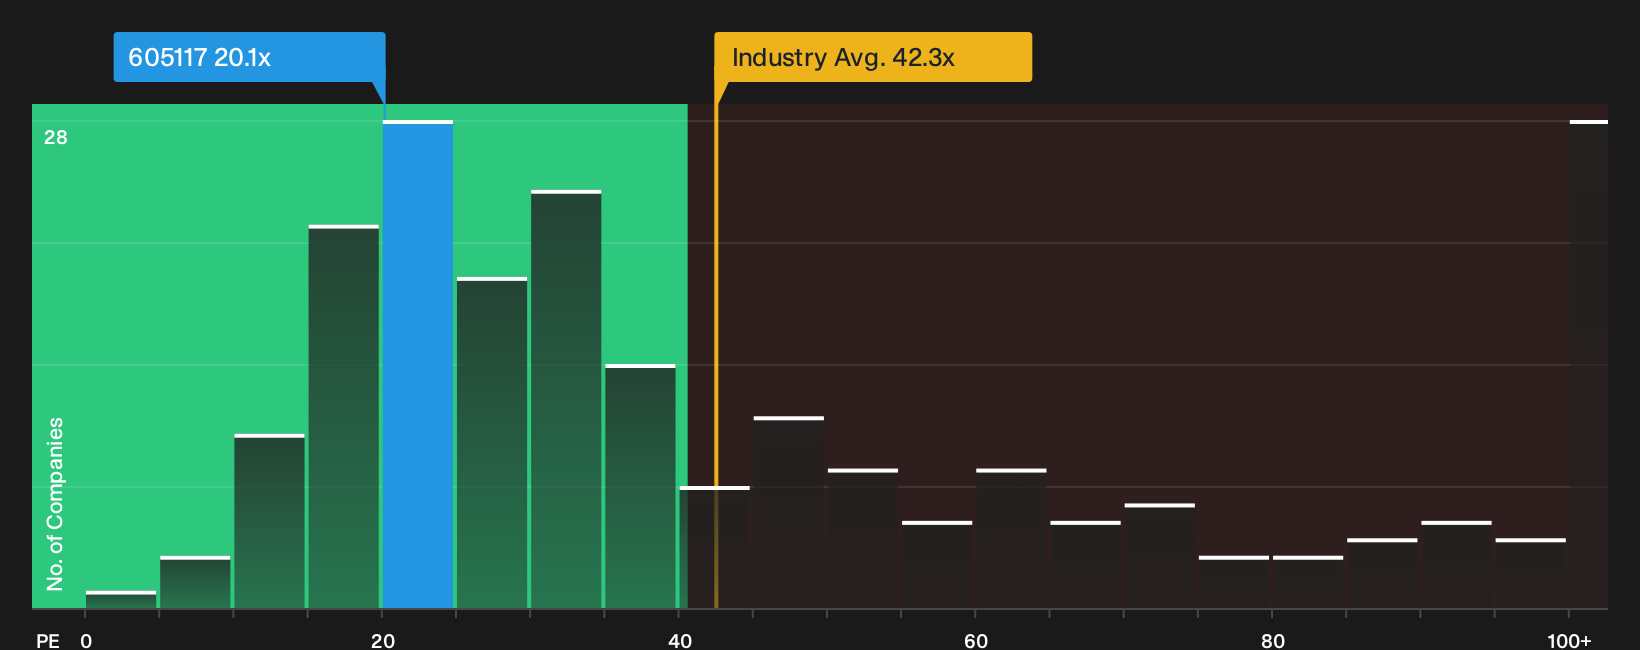
Ningbo Deye Technology Group ties directly into China’s renewable push because its inverters and storage units sit between fast growing solar capacity and the grid, helping turn that extra generation into usable power. Strong earnings momentum and high forecast returns make it one of the purer plays on that buildout, depending on how one unresolved pressure in inverter economics plays out.
That inverter economics question is exactly why it is worth reading the 3 key rewards and 1 important warning sign for Ningbo Deye Technology Group before deciding how its story could evolve.
Seeking Alternatives Before Everyone Else
Fresh opportunities move fast. Some ideas are building quiet breakout momentum while others are dropping off radars and staying under the radar for now. Scan them before the crowd and act now.
- Identify income workhorses early and use the 224 dividend fortresses to see which payers currently offer relatively higher yields alongside balance sheets that can support those distributions.
- Track where AI profits are already emerging and use the 39 profitable AI stocks that aren't just burning cash to filter for companies that generate cash rather than those primarily consuming capital.
- Consider potential positioning around metals cycles and review the 16 top copper producer stocks for producers that are currently operating in markets with tighter supply conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com