


EN
Icahn Enterprises (IEP) Trades At A Steep P S Discount, Is It Undervalued?
Icahn Enterprises (IEP) has drawn investor attention after recent trading left the unit price at US$5.56, with the partnership reporting US$10.39b in revenue and a net loss of US$515m across its diversified operations.
The recent stretch has been rough for Icahn Enterprises unitholders, with the 30 day share price return down 20.11% and the year to date move weaker. The 1 year total shareholder return decline of 12.16% hints at fading momentum after a much steeper 5 year pullback of 73.95%.
Scan opportunities beyond Icahn Enterprises by reviewing our hand picked 29 high quality undervalued stocks, which combine solid cash flows with balance sheets built to handle pressure.
Icahn Enterprises now trades at a much lower unit price after a long slide and a recent net loss. Does that reset the odds in favour of new buyers, or does it still leave too much downside risk on the table as valuation is weighed next?
Preferred Price-to-Sales Multiple of 0.4x: Is It Justified?
On current figures, Icahn Enterprises trades on a P/S of 0.4x against last close at $5.56, while peers cluster far higher. This points to a market that is pricing in considerable caution about the partnership's US$10.39b revenue base and recent US$515m loss.
The P/S ratio compares the market value of the partnership to its annual sales and, for a diversified group like Icahn Enterprises, it acts as a quick check on how much investors are willing to pay for each dollar of revenue across energy, automotive, real estate, and other units. A lower P/S can reflect concern around profitability, balance sheet risk, or earnings quality even when top line scale looks sizeable.
Against that backdrop, the current 0.4x P/S sits well below the 2.4x peer average and the 0.7x Global Industrials benchmark. This suggests that the market is assigning a steep discount to Icahn Enterprises relative to similar businesses. The partnership is unprofitable, has a return on equity running at a negative 23.11%, uses higher risk funding sources, and has a dividend yield of 35.97% that is not covered by earnings or free cash flow, so the low multiple appears tied to clear business concerns rather than a simple pricing anomaly.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 0.4x (UNDERVALUED)
Still, the partnership’s recent loss and heavy reliance on higher risk funding mean that any further pressure on cash flows could quickly challenge the current Icahn Enterprises narrative.
Find out about the key risks to this Icahn Enterprises narrative.
Another View on Icahn Enterprises: DCF Signals Even Deeper Discount
The low 0.4x P/S ratio paints Icahn Enterprises as cheap, but the SWS DCF model goes further. At a unit price of $5.56 versus an estimated future cash flow value of $9.12, IEP trades about 39% below that calculation. Does that gap point to mispricing or to cash flow risk that the model cannot capture?
Look into how the SWS DCF model arrives at its fair value.
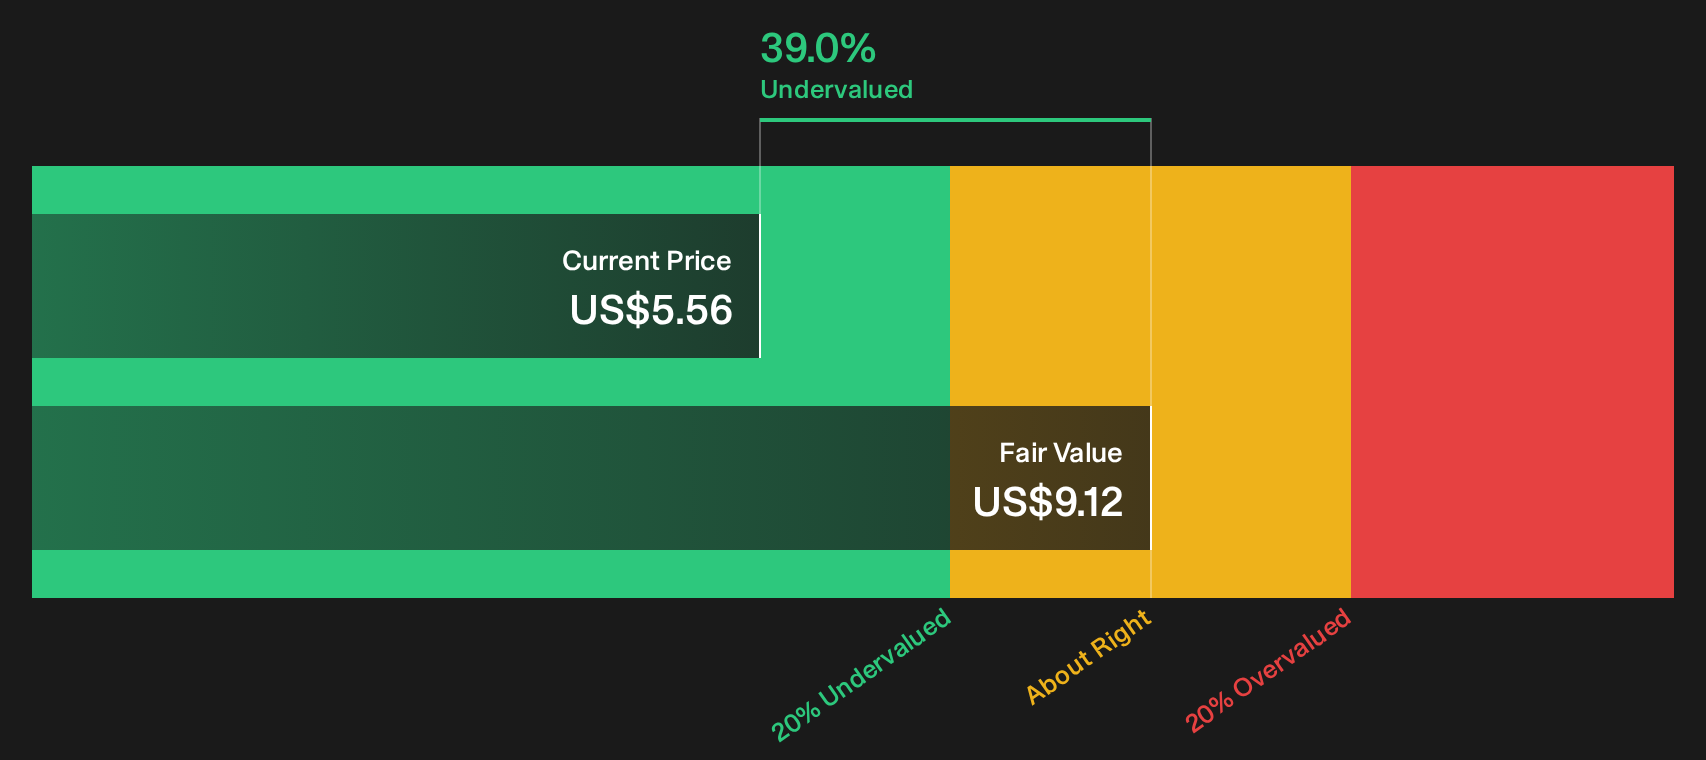
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Icahn Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Icahn Enterprises can make the picture feel murky, so move fast on your own homework and pressure test both sides of the story using the 1 key reward and 3 important warning signs
Looking for more ideas beyond Icahn Enterprises?
If you stop with Icahn Enterprises, you risk missing other setups that better match your goals, so broaden the search before you commit fresh capital.
- Target potential upside in beaten down opportunities by scanning the 7 elite penny stocks with strong financials that still pair compelling stories with underlying business traction.
- Prioritise resilience first by reviewing the list of solid balance sheet and fundamentals (24 results) so you focus on companies with funding and fundamentals built to absorb shocks.
- Hunt for mispriced quality by running through the 21 high quality undiscovered gems that combine solid fundamentals with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com