


EN
Rush Street Interactive Stock Draws Attention Ahead Of Earnings Report
- Rush Street Interactive is set to report quarterly earnings after the close, with the market expecting 39.8% year-on-year revenue growth and stronger performance than the same period last year.
- The business has drawn attention for record user growth alongside historic lows in customer acquisition spend as a share of revenue, pointing to a material shift in marketing efficiency and operating leverage.
- We will look at how expectations of strong earnings and improving marketing efficiency affect Rush Street Interactive's investment narrative.
Scan past Rush Street Interactive to see how other potential high growth stories with improving efficiency screen today with the curated 21 high quality undiscovered gems.
Rush Street Interactive Investment Narrative Recap
For Rush Street Interactive, the big-picture belief is that online casino and betting can keep gaining share as more play moves online and user engagement holds up across the United States, Canada and Latin America. The near term story hinges on whether earnings and cash generation can keep pace with that expansion while marketing spend remains disciplined.
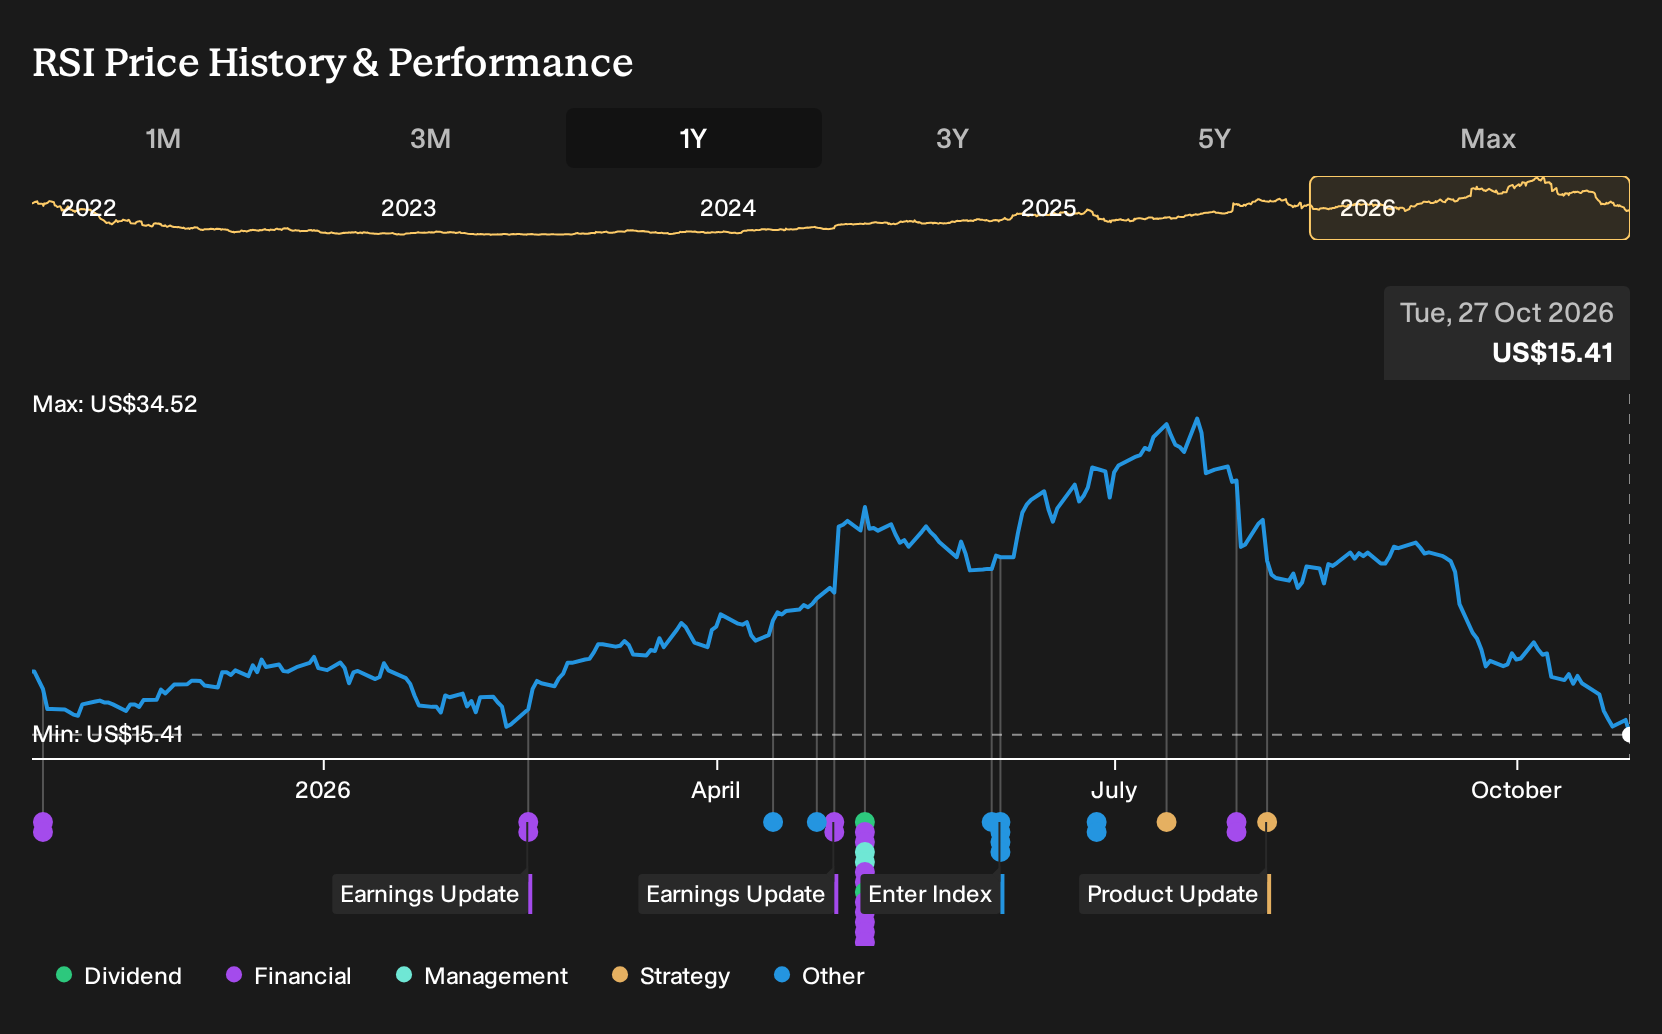
The upcoming earnings release is the clearest short term catalyst. It will show if recent marketing efficiency and user trends are still intact after a 20% share price decline over four weeks. The largest risk remains regulatory and tax changes in key markets that could pressure margins even if demand looks healthy.
The most relevant recent data point is the expectation for roughly 39.8% year on year revenue growth this quarter alongside record user growth and historically low customer acquisition spend as a share of revenue. If reported numbers line up with those expectations, that would reinforce the idea that Rush Street Interactive can add players without letting marketing outlays run away again.
Investors also have an eye on the 3.7x share price move over three years and a P/E level above the broader hospitality group but closer to online gaming peers. That combination increases execution risk around each quarterly update, because any sign of slower user additions, higher marketing intensity, or fresh tax headwinds in regions like Colombia and Mexico could quickly reset the growth narrative.
Rush Street Interactive's consensus narrative points to 2029 revenue of US$2.3b and earnings of US$112.2 million. That profile lines up with analysts assuming 18.7% yearly revenue growth and an earnings step up of roughly US$80.3 million from the current US$31.9 million base.
Uncover why Rush Street Interactive's fair value indicates a 120% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take on Rush Street Interactive focuses on slower online casino legalization as the key risk, rather than marketing trends. The most cautious analysts were penciling in revenue of about US$2.1b and earnings of US$71.7 million by 2029. That more muted path could shift again once this earnings report lands.
Explore 2 other Rush Street Interactive fair value estimates, including one that suggests it could be worth just $22.00!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rush Street Interactive research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rush Street Interactive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rush Street Interactive's overall financial health at a glance.
Looking for more Rush Street Interactive style investment ideas?
If Rush Street Interactive has sharpened your focus on growth potential and execution risk, it can be useful to scan a broader set of companies that fit different risk profiles and financial characteristics using the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, review a curated 29 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If resilience and balance sheet strength sit at the top of your checklist, start with a list of solid balance sheet and fundamentals (24 results) that already filters for financial sturdiness.
- When you want early stage potential with tighter criteria around fundamentals, narrow your search to a focused 7 elite penny stocks with strong financials and see which smaller companies fit your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com