


EN
Ultra Clean Holdings Stock Gains Attention After Earnings Beat and Strong Outlook
- Ultra Clean Holdings reported third quarter 2026 revenue of US$759 million and net income of US$39.1 million, alongside positive nine-month earnings after a prior year loss, and issued fourth quarter guidance calling for US$800 million to US$860 million of revenue and GAAP diluted EPS of US$1.02 to US$1.26.
- The business linked this earnings strength and outlook to strong semiconductor demand tied to AI infrastructure and advanced packaging, while ramping manufacturing capacity across Malaysia, the Philippines, Singapore and the Czech Republic to support customer programs and address supply chain constraints.
- We will now look at how Ultra Clean Holdings' investment narrative could be affected by the strong third quarter earnings beat and guidance.
Scan beyond Ultra Clean Holdings and see how other AI infrastructure suppliers are setting up for their own inflection points with our hand picked 55 AI infrastructure stocks.
Ultra Clean Holdings Investment Narrative Recap
To own Ultra Clean Holdings, you need to believe the build out of AI heavy semiconductor capacity and wafer fab equipment eventually turns into sustained orders across its products and services. The third quarter jump from a prior year loss to US$39.1 million of profit supports that thesis in the near term, as the business shows it can handle higher volumes.
The key near term swing factor is whether recent strength and fourth quarter guidance translate into cleaner working capital and better cash generation, not just revenue. The biggest current risk is that inventory and capacity investments stay out in front of actual demand for too long, which would keep pressure on cash flow and interest coverage.
The most relevant update here is management’s fourth quarter 2026 outlook, calling for US$800 million to US$860 million of sales and GAAP diluted EPS of US$1.02 to US$1.26. That range, coming off US$759 million of third quarter revenue, signals expectations for continued busy factories as AI and advanced packaging programs progress.
For you, the focus is how this guidance lines up against the existing catalysts. The plan to scale capacity toward a higher revenue run rate, lean into UCT 3.0 and grow services all depend on volumes staying robust enough to absorb working capital and interest costs. Any shortfall against guidance would quickly refocus attention on cash use and balance sheet flexibility.
Ultra Clean Holdings' current analyst narrative points to US$4.4b of revenue and US$289.4 million of earnings by 2029, based on an assumed 26.0% yearly revenue growth rate and a shift from today’s earnings loss of US$23.4 million to that 2029 consensus profit. This implies roughly a 13x increase in earnings in dollar terms.
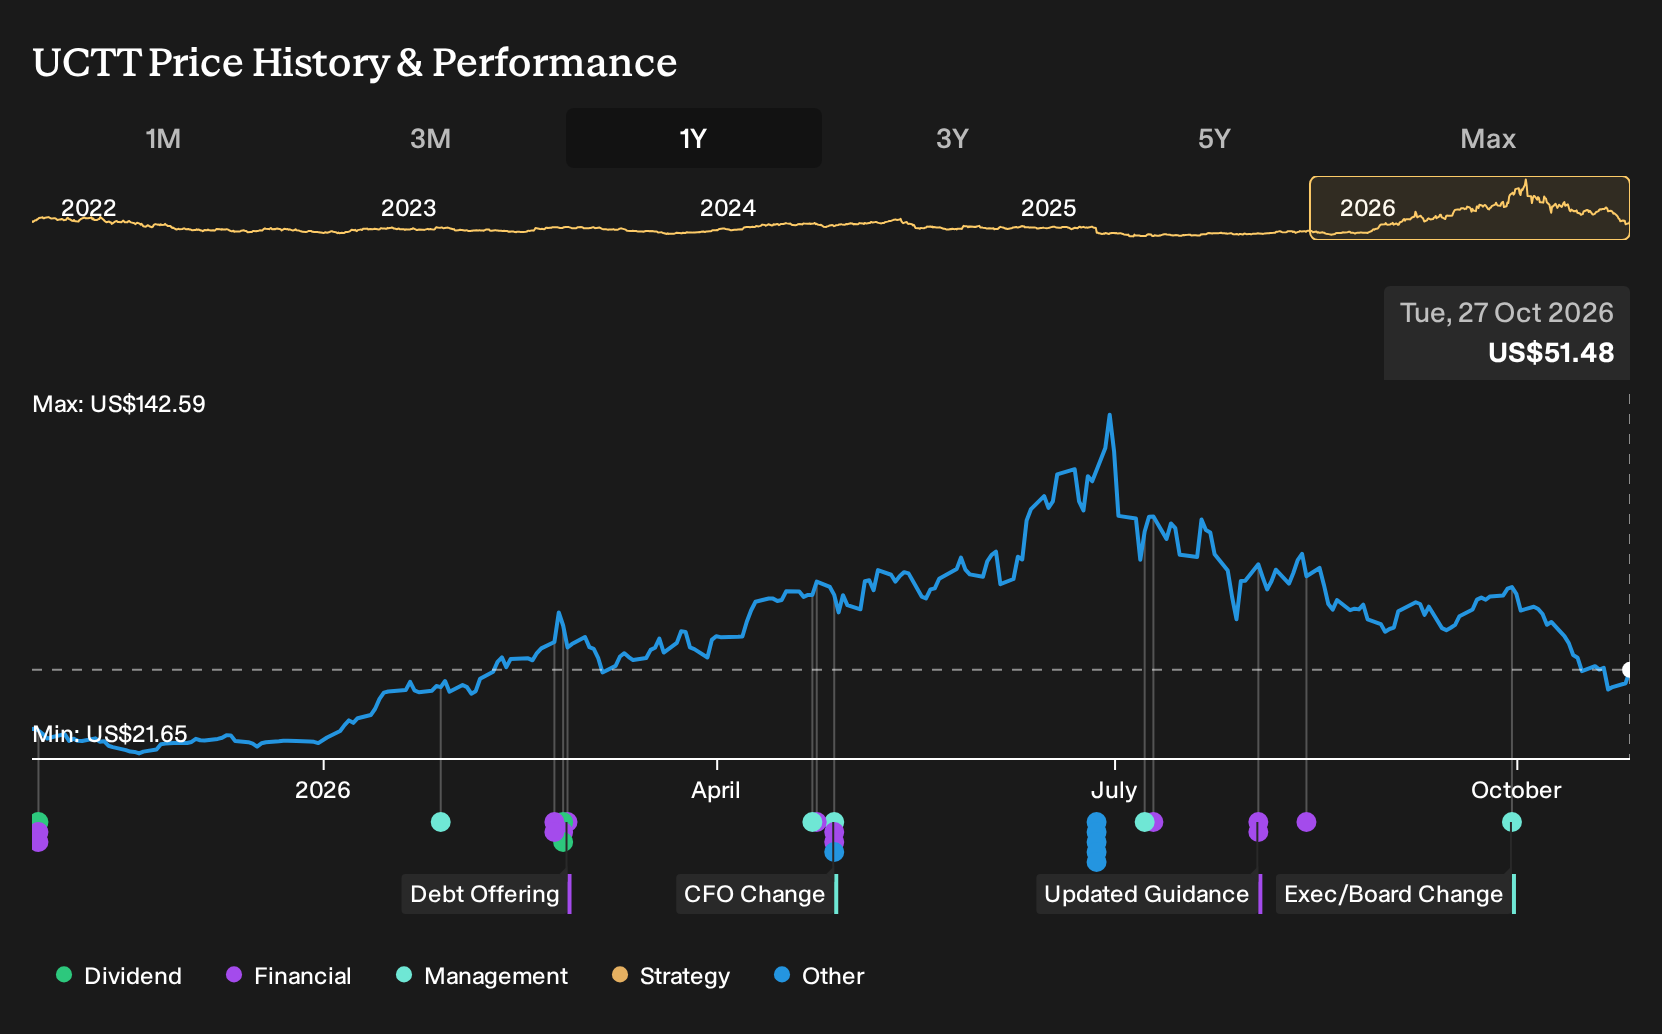
Uncover why Ultra Clean Holdings' fair value indicates a 158% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the lowest Ultra Clean Holdings forecasts leaned hard into the risk that long customer qualification cycles could slow subsystem orders, with bearish analysts only pencilling in about US$4.1b of revenue and US$207.1 million of earnings by 2029. You are now seeing fresh quarterly numbers that those cautious views have not yet absorbed, so it makes sense to compare both stories before deciding which you find more convincing.
Explore 3 other Ultra Clean Holdings fair value estimates, including one that suggests as much as 76% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ultra Clean Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ultra Clean Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ultra Clean Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ultra Clean Holdings?
If you want to pressure test your thesis on Ultra Clean Holdings against other opportunities, the Simply Wall St Screener can help you quickly sort through companies with different risk and return profiles.
- If you are hunting for potential mispricings with strong fundamentals, start by scanning a curated 29 high quality undervalued stocks that may warrant a closer look.
- For readers who care most about capital strength and resilience, filter for companies via a list of solid balance sheet and fundamentals (24 results) so you can focus on businesses that might better handle tougher conditions.
- Income oriented investors can focus on reliability first and yield second by reviewing a hand picked set of 5 dividend fortresses that combine higher payouts with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com