


EN
Revenue And Margin Update Has The Maravai Stock Case Changed?
- Maravai LifeSciences Holdings recently reported revenue and adjusted gross margin figures that investors are using to reassess the company’s core sales strength and operational footing.
- The fresh data on margins and sales mix is sharpening focus on how nucleic acid production and mRNA therapy services might support more durable demand across Maravai’s portfolio.
- We will now look at how the latest margin improvement and revenue update may reshape the investment narrative for Maravai LifeSciences Holdings.
Scan how Maravai LifeSciences Holdings stacks up against other fast-moving life sciences players by checking a curated set of 21 high quality undiscovered gems that are riding similar momentum in sales and margin stories.
Maravai LifeSciences Holdings Investment Narrative Recap
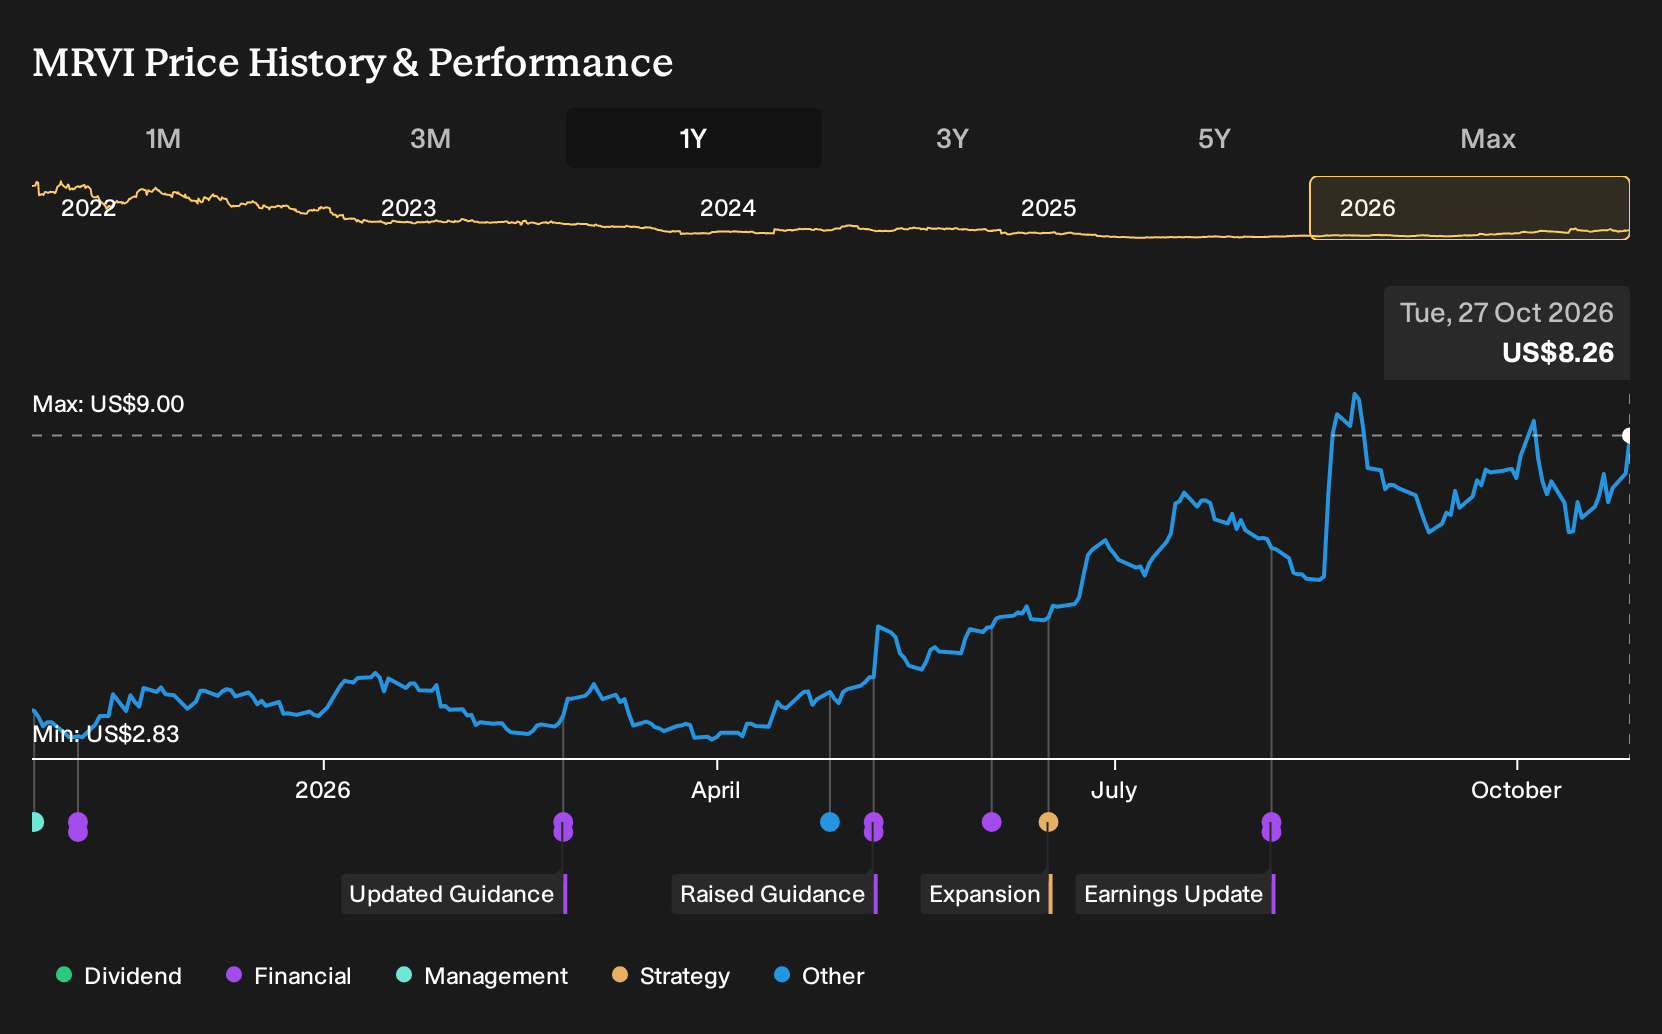
To own Maravai LifeSciences Holdings you need to be comfortable with a story built on nucleic acid production, mRNA tools and biologics testing gradually scaling into a more stable business. The recent revenue and adjusted gross margin update helps that case in the near term, since healthier unit economics can support the restructuring and cost reduction plan already in motion.
The flip side is still real. Revenue has been lumpy, the group remains loss making, and customer concentration around products like CleanCap keeps execution risk high. In the short run, order visibility and follow through on cost savings look like the main catalysts, while any renewed order softness is the key operational risk.
Recent commentary around higher revenue and improved adjusted gross margins is the announcement that feels most relevant here. It speaks directly to whether Maravai LifeSciences Holdings can turn its nucleic acid and biologics testing toolkit into something closer to a repeatable, higher quality earnings stream rather than a one off COVID skewed spike.
If those healthier margins hold while the restructuring plan targets more than US$50m in annualized savings, investors will likely keep focusing on cash burn, adjusted EBITDA and how much of the growth is coming from mRNA therapies beyond COVID. Any sign that order lumpiness is easing would support that thesis, while renewed weakness would put the spotlight back on concentration risk.
Maravai LifeSciences Holdings is currently modeled on analyst assumptions that yearly revenue grows by 7.0%, with the top line reaching US$255.7 million and earnings of US$40.8 million by 2029, compared with earnings today of a US$77.4 million loss. This implies an earnings swing of roughly US$118 million over that period.
Uncover why Maravai LifeSciences Holdings' fair value indicates a 3% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
For Maravai LifeSciences Holdings, the alternate storyline leans hard on revenue volatility risk. The most cautious analysts were penciling in yearly sales of about US$248.9 million and earnings of roughly US$39.7 million by 2029, which is slightly below consensus. Those pre news assumptions may shift, so treat them as one viewpoint rather than a definitive conclusion.
Explore another Maravai LifeSciences Holdings fair value estimate, including one that suggests it could be worth just $8.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Maravai LifeSciences Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Maravai LifeSciences Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Maravai LifeSciences Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Maravai LifeSciences Holdings?
If you want to stress test the Maravai LifeSciences Holdings thesis against other opportunities, it helps to scan a wider field of stocks that share similar qualities in value, resilience, or upside potential.
- For investors who prize a margin of safety and robust fundamentals, review a 29 high quality undervalued stocks that screens for quality businesses trading below their assessed worth.
- If capital preservation and steadier risk profiles matter most to you, consider a 30 resilient stocks with low risk scores that highlights companies with stronger balance sheets and cleaner risk scores.
- When you want a shortlist of businesses with financial strength and room to compound, check a list of solid balance sheet and fundamentals (24 results) to surface stocks with sturdier gearing and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com