


EN
Did Singapore Control Center Deal Just Shift Siemens (XTRA:SIE) Investment Narrative?
- Siemens partnered with semiconductor manufacturer GlobalFoundries to build an Advanced Facilities Control Centre at the latter's Singapore campus, centralizing multiple fab control rooms using real time data and predictive maintenance tools.
- The project gives Siemens another live reference for integrated industrial software and automation, directly aligned with its push into higher value digital manufacturing solutions.
- The next consideration is how Siemens' investment narrative could be influenced by this centralized facilities control initiative with GlobalFoundries.
Scan other factory automation plays that are moving on similar themes by reviewing our hand picked list of 94 robotics and automation stocks aligned with Siemens' push into digital manufacturing control.
Siemens Investment Narrative Recap
To own Siemens, you need to believe the shift toward software heavy automation, data center infrastructure and electrification keeps drawing customer budgets, and that the €132b order backlog supports that direction. The GlobalFoundries control center fits this story, but the key short term swing factor is still execution in Digital Industries and Smart Infrastructure, not this single project.
The biggest near term worry remains that high expectations around margins and earnings, alongside a relatively rich P/E versus the wider European industrials group, leave little room for operational missteps or slower customer spending. If macro or tariff pressure hits large projects, order intake and pricing power could come under pressure.
The upcoming appearance at the Third Annual Manufacturing Excellence Summit in Austin puts Siemens’ automation and scheduling know how in front of exactly the sort of industrial buyers that care about the GlobalFoundries project. This gives investors a clearer read on how management talks about real time data, predictive maintenance and integrated control in front of peers and customers.
For catalysts, this matters less as a headline event and more as an execution checkpoint. Investors can watch how Siemens links live references like the Singapore control center to its broader digital automation portfolio, then assess whether that aligns with the existing backlog, software ARR growth and the push toward higher margin, recurring revenue streams.
What The Current Siemens Forecasts Assume
Siemens' narrative projects €88.5b revenue and €11.3b earnings by 2029. This implies 2.9% yearly revenue growth and an earnings increase of about €3.4b from €7.9b today.
Those analyst numbers effectively ask you to underwrite two big pillars. First, that the move toward higher software content and integrated control, highlighted by projects like the GlobalFoundries facilities center, can support earnings rising from €7.9b to €11.3b by 2029 while profit margins move from 9.7% to 12.7%. Second, that investors will still be comfortable paying a P/E of 24.4x on those future earnings, even though that multiple sits well above the 15.2x level quoted for the wider GB Industrials group.
The revenue line embedded in this story is not extreme on paper. A 2.9% annual growth rate points to gradual expansion of the overall business, rather than a high octane acceleration narrative. For a reader tracking Siemens against other factory automation and control peers, that pace frames the GlobalFoundries control center more as evidence of steady execution in digital manufacturing, not as a single project that needs to transform the top line on its own.
What matters more is how that relatively modest revenue trajectory pairs with margin assumptions. Analysts are effectively saying that better software mix, tighter capacity utilization and projects like centralized control rooms can lift profitability enough to take earnings to €11.3b even on low single digit top line growth. If you think predictively maintained fabs and automated facilities management become standard across more campuses, the GlobalFoundries set up may look like a proof point that supports that margin story, rather than a one off headline.
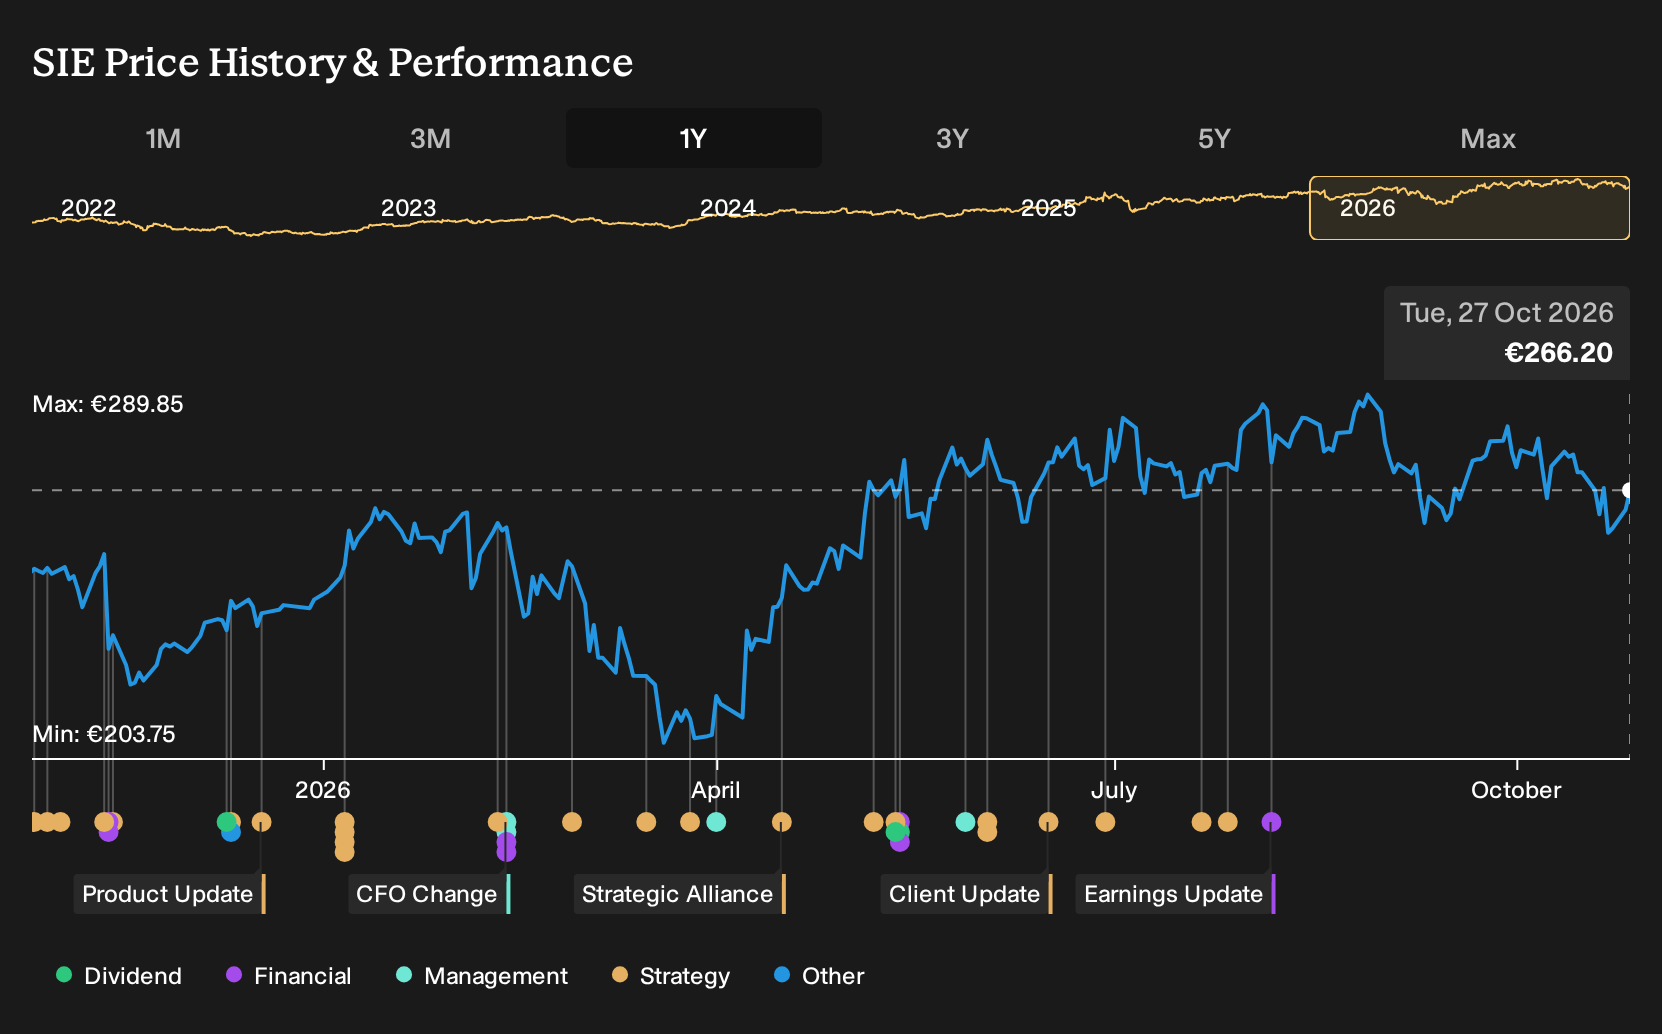
Uncover why Siemens' fair value indicates a 15% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic Siemens analysts already modeled a stronger digital automation payoff, with revenue projections of €111.1b and earnings of €13.2b by 2029, before this GlobalFoundries control center news. You might see that as a catalyst for even higher expectations or as a stretch that could be revised once the Austin summit commentary lands.
Explore 4 other Siemens fair value estimates, including one that suggests as much as 39% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Siemens research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siemens. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siemens' overall financial health at a glance.
Looking For More Investment Ideas Beyond Siemens?
If the Siemens story has you thinking about where automation, quality balance sheets and income resilience intersect, it can help to line it up against a broader watchlist built with the Simply Wall St Screener.
- For potential turnarounds with disciplined finances, review a curated 124 elite penny stocks with strong financials that meet tighter fundamental criteria than the usual speculative small caps.
- If you want candidates where quality and pricing look more conservative, scan a 195 high quality undervalued stocks filtered for stronger cash generation and balance sheets.
- For readers focused on income, use the screener to surface 224 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com