


EN
Want Income for Life? This Dividend Stock Has Funded Investment Portfolios With Growing Passive Income for 57 Straight Years.
Key Points
Brand loyalty and nicotine's addictiveness give Marlboro cigarettes remarkable pricing power, which Altria has been capitalizing on for decades.
Altria's formula of steadily raising prices per pack to compensate for falling unit sales won't work forever, but it's probably a safe bet for the foreseeable future.
Growth investors typically buy stocks based not on what a business is today, but on what it could become in the future. For dividend investors, it's frequently the opposite idea. Take, for example, the investment thesis for Altria Group (NYSE: MO), the giant tobacco company behind Marlboro.
Although cigarette smoking is a slowly dying trend in the United States, and has been for decades, investors have continued to buy Altria stock for its steadily growing dividend. The company is a Dividend King, with a streak of 57 consecutive annual payout hikes. (To earn the title of Dividend King, a company must boost its payouts for at least 50 straight years -- a rare accomplishment.)
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
That history, combined with the business's financial staying power, gives shareholders the confidence that those dividends will continue rolling in.
How Altria makes and pays shareholders more each year
Altria only sells cigarettes in the United States, and smoking rates domestically have been in decline for decades. (It split off its international business as Phillip Morris International back in 2008.) Marlboro is the nation's top cigarette brand by a wide margin, so it will come as little surprise that Altria has been selling fewer and fewer cigarettes every year for quite some time. But cigarettes are infamously addictive and smokers demonstrate remarkable brand loyalty -- a combination of factors that has given Altria strong pricing power. It has used that to regularly boost its prices per pack, offsetting its shrinking sales volumes with higher cigarette prices.
Image source: The Motley Fool.
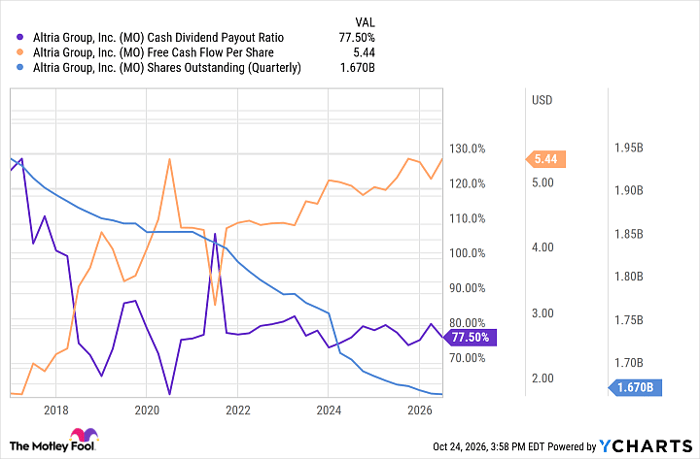
From there, the formula is pretty simple. Altria distributes about 80% of its cash flow via dividends and uses most of the rest to buy back its stock. With fewer shares to pay dividends to, Altria has been able to raise its dividend year in and year out while keeping its payout ratio in check.
MO Cash Dividend Payout Ratio data by YCharts.
In fact, Altria's free cash flow per share is up by a whopping 194.8% over the past decade alone. But even if something were to happen to Altria's business, its strong balance sheet could still support the dividend.
Among other assets, Altria owns roughly 150 million shares of Anheuser-Busch InBev, worth approximately $12.6 billion at today's prices. That's a nice stack of financial chips that management can cash in on whenever it feels the need to.
Eventually, change will probably come
Altria has been following the same playbook of raising cigarette prices to great success for decades now, so there's no glaring reason to fear for its dividend -- at least, not while the company has billions of dollars in cash and equity backing the payout ratio. Who knows? Depending on your age, an investment in Altria could provide you with a growing income stream for the rest of your life.
But the further out you look, the more the risks to the business model and the dividend increase. There could come a point where Altria struggles to offset the impact of its declining sales volumes with price hikes imposed on the smokers who remain. There could come a point when a critical mass of smokers are left struggling to afford the habit, and sales volume losses accelerate.
Either way, Altria may need to diversify its business more than it has. It hasn't been for lack of trying. Altria has some high-profile failures on its record; just look up the Juul debacle. The company is building some solid sales momentum with smoke-free products such as its On! nicotine salt pouches. But smokeable products still carry most of the business.
Investors should keep an eye on the company's long-term progress with brands other than Marlboro cigarettes. In the meantime, you can buy Altria stock for its 6% dividend and feel reasonably sure that the income stream it provides is secure.
Justin Pope has positions in Philip Morris International. The Motley Fool recommends Philip Morris International. The Motley Fool has a disclosure policy.