


EN
Missed Merck KGaA's Run? What Holders Had To Believe
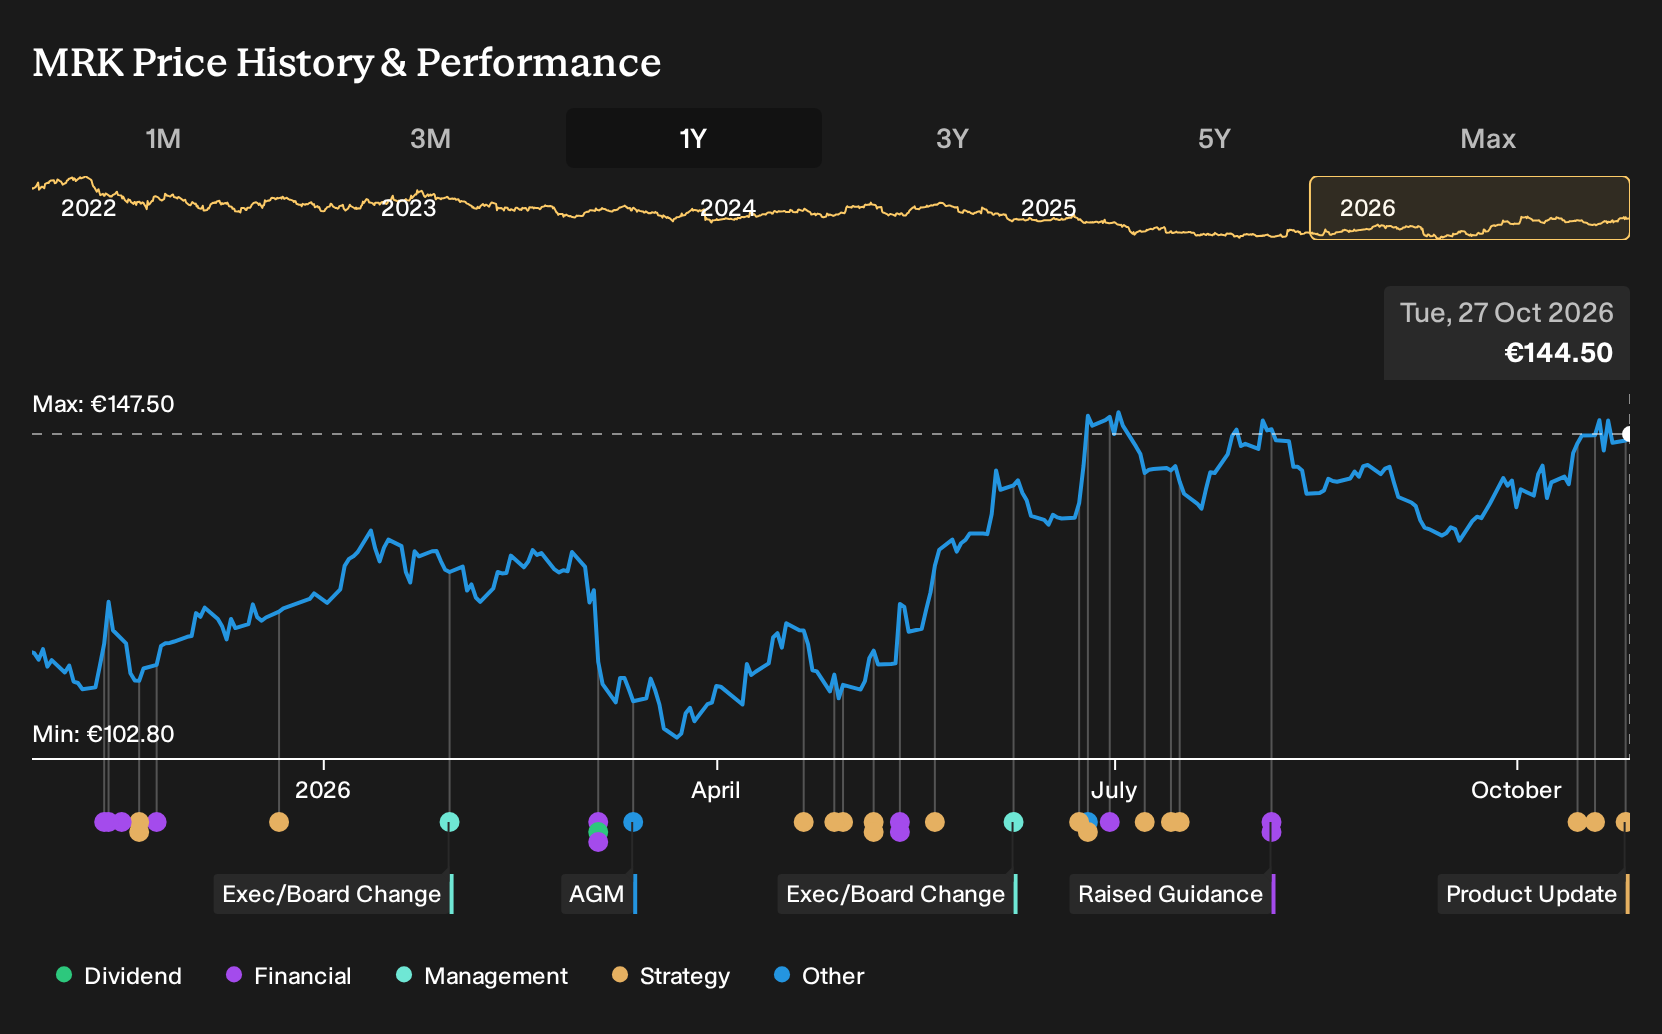
If you had put money into Merck KGaA on 27 October 2025 and simply left it alone, the outcome over the next twelve months would have looked very different from the debate at the time about legacy drugs and new biotech bets. Investors who held Merck KGaA over the past year are up 29.9%, including dividends. The real question is what early buyers were weighing more heavily: the life science build out or the patent and margin risks in healthcare?
Merck KGaA has already moved. Pinpoint other ways to investigate the theme among 123 healthcare AI stocks.
The Two Merck KGaA Stories Investors Were Arguing About
The shares cost €114 at the start of the period, so anyone looking at Merck KGaA had to decide which future felt more realistic.
The bullish story pointed to a Fair Value of €148, essentially the price implied if Life Science expansion, a move to higher margin segments and a future P/E assumption of 20.8x played out as expected.
The bearish view put Fair Value at €100, treating tighter regulation and reliance on blockbuster drugs such as Mavenclad, with looming patent expiry risk, as the central problems.
What The Evidence Around Merck KGaA Actually Tested
Merck KGaA’s later period was packed with expansion moves that leaned toward the bullish story of life science and higher margin specialties. Revenue reached €5,434m in Q2 2026 compared with €5,255m a year earlier, yet net income slipped to €490m from €652m and net margin moved from 12.4% to 9.0%. The evidence cut both ways.
The key assumption investors can recycle elsewhere is simple. When a thesis leans on margin expansion, do not just track sales. Instead, watch whether net income and the reported net margin move in the same direction as the growth story.
What Merck KGaA's Price Already Presumes
With Merck KGaA now at €144 after a 29.9% gain over the past year, this selected Narrative’s Fair Value sits below the current price. It frames today’s level as already baking in a confident outcome on several moving parts.
Execution on the Bio-Techne acquisition, semiconductor demand and the rare disease pivot are central to that story. A buyer today is effectively assuming these bets keep margins resilient. How does the Narrative’s focus on higher R&D intensity and deal complexity test that comfort?
"A key requirement for the strategy to succeed is that Merck KGaA converts its shift toward integrated Life Science workflows, AI-backed Semiconductor Solutions demand, and a rare disease pipeline into durable, high-margin growth that supports ongoing capital and R&D spending."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 25% below our estimate - targets higher average fees and billing ratios while integrating acquired design and engineering teams.
- Company 2 - 42% below our estimate - pushes larger LED installs as software, services and streamlined plants reshape display orders.
- Company 3 - 46% below our estimate - works through mega-project backlog while trying to contain legacy construction dispute liabilities.
That is three of the list. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com