


EN
Is Delta Air Lines (DAL) Fully Priced Following TD Cowen's Bullish Call?
Delta Air Lines (DAL) is back on investors’ radar after TD Cowen reaffirmed the carrier as one of its preferred U.S. airline stocks, even as rising fuel costs pressure sector earnings expectations.
That call from TD Cowen comes as Delta Air Lines trades at $81.45, with a 1-day share price return of 2.89% and a 7-day share price return of 6.25% following sector-wide enthusiasm around airline earnings and network tweaks such as shifting the Reykjavik service to a Boston seasonal route. The 30-day and 90-day share price returns, down 4.11% and 5.57% respectively, contrast with a 17.94% year-to-date share price gain and a 1-year total shareholder return of 42.27%, which together reflect stronger performance over the longer term alongside recent volatility.
Scan 29 high quality undervalued stocks was selected for balance-sheet strength and cash flow resilience, which align with the Delta Air Lines story unfolding after TD Cowen's call and recent route changes.
After the latest jump in Delta Air Lines, the gap between its US$81.45 share price, analyst targets near US$100.78, and deeper intrinsic estimates is hard to ignore. Where does fair value actually sit in that spread?
Most Popular Narrative: 28.9% Overvalued
Against Delta Air Lines at $81.45, the most followed narrative pegs fair value nearer $63.21, so the gap to recent trading is clear and worth understanding.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That's why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop, and Delta would have to increase its current profit margins considerably to justify these multiples, which is a well nigh impossible order. If you seek exposure to the airline industry, Delta is a mandatory buy without doubt, but not at these levels. Once the froth is out of the price, however, I'm certain to increase my holding.
See why 23 investors see Delta Air Lines as 29% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, this script can flip fast if fuel prices spike again or if another demand shock hits already thin airline margins, and Delta Air Lines is not immune.
Find out about the key risks to this Delta Air Lines narrative.
Another View: SWS DCF Signals Deep Undervaluation
That narrative calling Delta Air Lines overvalued reaches a very different conclusion than our DCF work. The SWS DCF model, based on projected future cash flows, points to a fair value near $244.06 per share. Compared with the current $81.45 quote, this framework presents Delta as heavily undervalued. Which story appears more realistic right now: sentiment-driven concerns about margins, or a cash flow curve that extends well beyond the next few quarters?
To see how that number is built from the ground up and where the biggest swing factors sit in the forecast, Look into how the SWS DCF model arrives at its fair value.
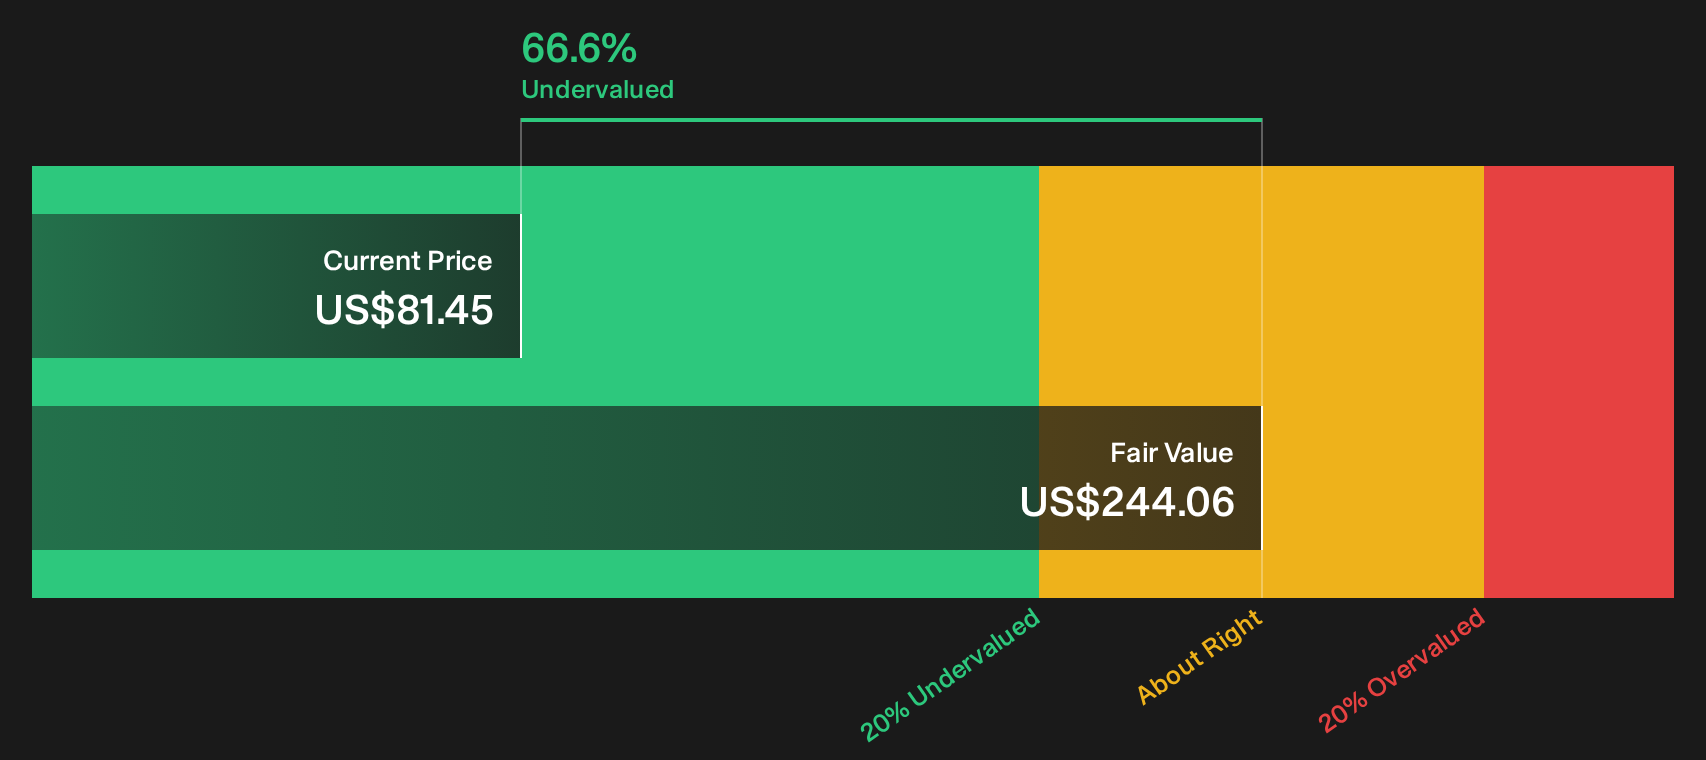
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Delta Air Lines can be useful if they push you to test the assumptions yourself and move before sentiment swings again. To weigh both the concerns and the optimism around the stock in one place, check the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Delta Air Lines?
Delta Air Lines gives plenty to think about, yet your next strong opportunity could come from a very different corner of the market if you widen your search.
- Target resilient cash generators by scanning companies on the 29 high quality undervalued stocks that pair discounted prices with solid underlying fundamentals.
- Prioritise staying power and capital protection by reviewing the 30 resilient stocks with low risk scores that focuses on businesses with comparatively steadier risk profiles.
- Spot under-the-radar potential by checking the 21 high quality undiscovered gems that highlight quality enterprises many investors are still overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com