


EN
Missed ASUSTeK Computer's Run? What Holders Had To Believe
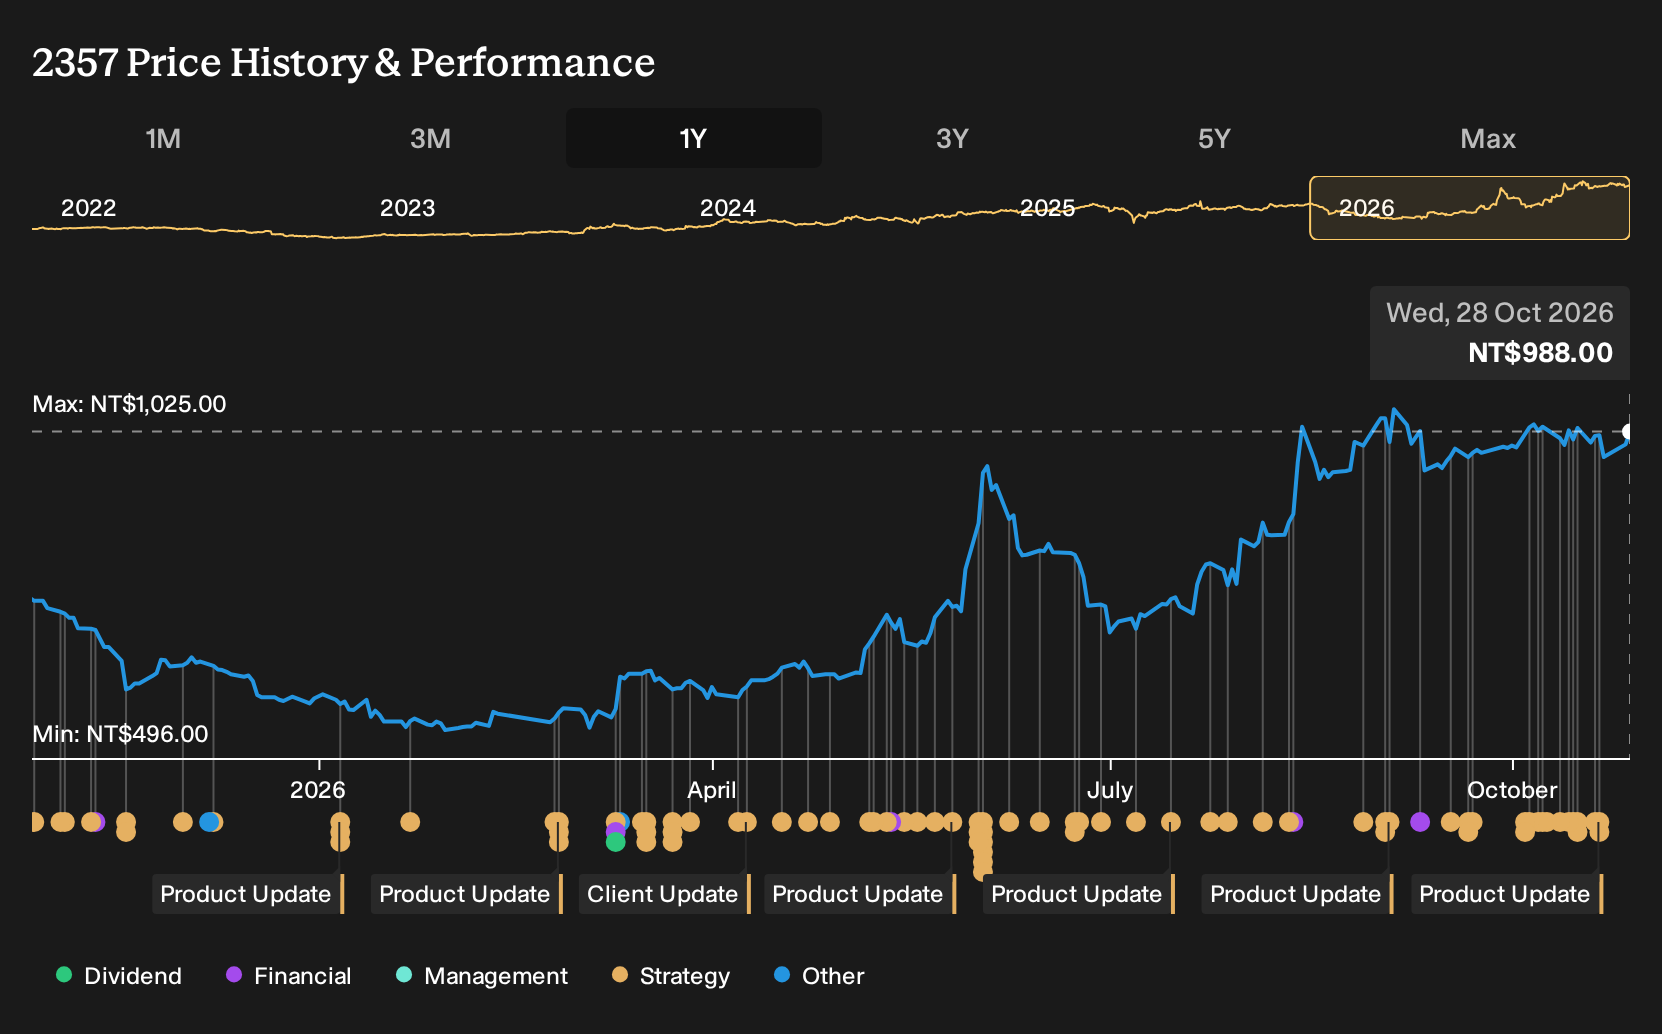
ASUSTeK Computer spent this year talking up AI PCs, RTX 50 Series gaming gear and fresh AI server platforms, then quietly booked higher second quarter revenue and net income with a wider net margin. For ASUSTeK Computer shareholders, the return over the past year was 48.2%, including dividends. If you had been deciding back on 28 October 2025, what would have needed to be true about future AI demand and gaming spend to justify buying in before any of that was confirmed?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond ASUSTeK Computer. See which of 55 AI infrastructure stocks may still merit a closer look.
The Argument ASUSTeK Computer Investors Faced Back Then
The shares cost NT$708 at the start of the period, so anyone circling ASUSTeK Computer had to decide which story about AI PCs and gaming felt more convincing.
The bullish narrative pinned Fair Value at NT$856, leaning on the idea that AI PCs could reach around 30% penetration with ASUS keeping a leading share, while tight RTX 50 Series supply might support premium pricing.
The bearish view put Fair Value at NT$615, stressing risks from declining PC demand, tougher Chinese competition, and big tech ecosystems that could squeeze ASUSTeK Computer's margins.
What The Results Changed For ASUSTeK Computer
ASUSTeK Computer rolled out the ROG G1000 desktop with RTX 5080 and showcased new HGX Rubin NVL8 and MGX AI servers, which lined up with the AI and gaming hardware story. During the same window, total revenue moved from NT$188,006.262m in Q2 2025 to NT$257,731.987m in Q2 2026 and net income and net margin also rose, so the evidence leaned toward the optimistic case.
The takeaway is simple. When a thesis leans on new AI and gaming cycles, you can test it by tracking segment heavy launches, then checking if reported net margin and profit move in the same direction.
What ASUSTeK Computer's Price Now Asks You To Believe
ASUSTeK Computer trades at NT$988 today, after a 48.2% gain over the past year from NT$708. The selected Narrative places Fair Value below that level, framing the current quote as already assuming successful AI infrastructure scaling and a richer mix of higher margin gaming and premium PCs.
The concern it raises is simple. For today's price to make sense, a buyer would need to assume ASUSTeK Computer can keep a higher margin product mix intact even if component shortages, memory inflation and supply constraints persist.
"The main requirement is that ASUSTeK Computer maintains its higher margin mix in gaming, AI infrastructure and commercial PCs while component costs and supply constraints persist. The current valuation suggests the market is already pricing ASUSTeK Computer for successful scaling of AI infrastructure, a premium PC mix and commercial expansion, despite memory inflation risks and consumer PC headwinds."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 37% below our estimate - builds an animal and human health platform using integrated manufacturing and CDMO partnerships.
- Company 2 - 25% below our estimate - shifts toward higher margin photonic solutions as semiconductor and biophotonics orders recover.
- Company 3 - 39% below our estimate - refocuses content and merchandise on core Asian fanbase after scaling back English expansion.
Those are three of them. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com