


EN
Is InvenTrust Properties (IVT) Undervalued Following Its Q3 Beat And Raised Guidance?
What the latest earnings signal for InvenTrust Properties stock
InvenTrust Properties (IVT) just paired a Q3 earnings beat with higher full year net income guidance, putting fresh attention on how its essential retail portfolio is performing for shareholders.
Investors have started to respond to the Q3 beat and upgraded outlook, with InvenTrust Properties’ share price edging up 0.8% over the last day and 1.2% over the past week. However, the 90 day share price return is down 15.2% and the 1 year total shareholder return sits at 10.9%, pointing to longer term holders still being in positive territory while short term momentum has only just begun to improve.
Scan how InvenTrust Properties stacks up against other income-focused real estate plays by comparing it with our hand picked 5 dividend fortresses in a single view.
The Q3 beat, raised guidance, and modest recent share move at InvenTrust Properties leave you weighing two paths: lock in exposure now at this reset level, or wait for a deeper pullback before stepping in.
Most Popular Narrative: 17% Undervalued
On the most followed view of InvenTrust Properties, a fair value of $36.63 sits well above the last close at $30.33, which puts the recent earnings beat into a wider valuation context.
The key thing that has to go right is that management continues to convert migration driven demand and necessity based tenant mix in Sun Belt and emerging secondary markets into sustained leasing spreads and same property NOI performance while maintaining balance sheet discipline.
The current valuation implies the share price does not fully reflect this combination of Sun Belt oriented NOI trends, earnings progression and measured use of leverage, which keeps the InvenTrust Properties equity story tilted toward an undervalued setup.
See why 0 investors see InvenTrust Properties as 17% undervalued.
Result: Fair Value of $36.63 (UNDERVALUED)
Still, the InvenTrust Properties story can shift quickly if acquisition yields fail to clear that 5.4% debt cost, or if open air retail competition squeezes returns.
Find out about the key risks to this InvenTrust Properties narrative.
Another angle on InvenTrust Properties’ valuation
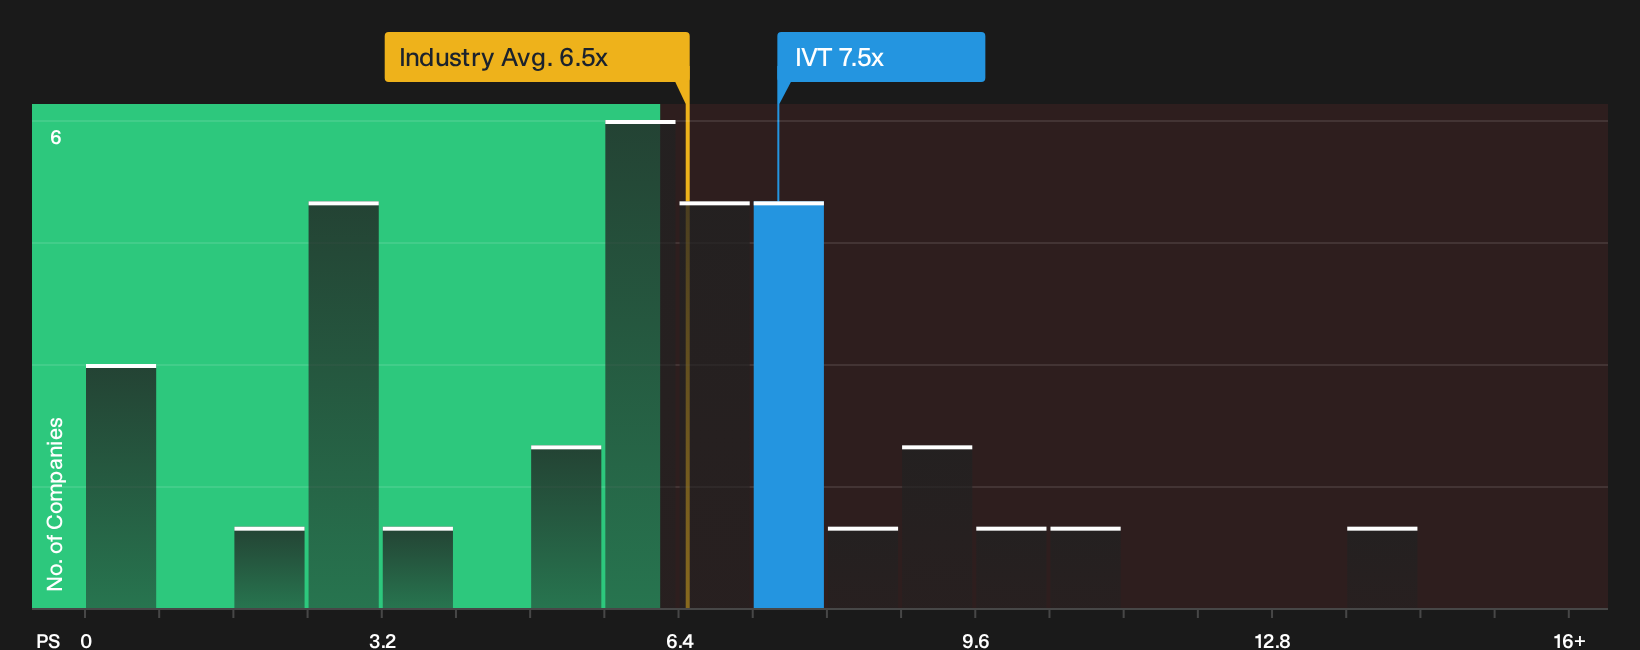
The story looks different when you shift from fair value estimates to the actual P/S multiple. InvenTrust Properties trades at 7.5x sales, above both the US Retail REITs industry on 6.6x and peers at 7.1x, while the fair ratio for IVT is 5.1x. That gap points to meaningful valuation risk if sentiment or pricing power cools.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on valuation and multiples can pull you in both directions, so move quickly and review the full picture for yourself with the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond InvenTrust Properties?
If you like how InvenTrust Properties lines up but want options, consider casting the net wider now so you do not miss out on tomorrow's opportunities.
- Identify potential mispricing early and scan a curated set of 21 high quality undiscovered gems before they attract broader attention.
- Prioritise resilience in your portfolio and review a list of solid balance sheet and fundamentals (24 results) that can help handle shocks more effectively than fragile businesses.
- Dial down risk while staying invested and check out 30 resilient stocks with low risk scores that may suit a steadier, sleep-at-night approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com