


EN
Select Water Solutions (WTTR) Stock Looks Rich Ahead Of November Earnings
Select Water Solutions has delivered a long run of strong share returns, which puts fresh attention on a simple question for you as an investor: Is the current price supported by what the business is earning today and may earn in the future.
- Over the past 5 years, Select Water Solutions has returned 260.7%, which makes it important to check whether that kind of gain is aligned with the underlying earnings power of the business.
- The upcoming earnings release and conference call scheduled for 9 November 2026 can update the market on profitability, which may reshape expectations for how much of today's share price is being driven by current earnings versus hoped for future cash flows.
- The analysts covering Select Water Solutions have run their own numbers. See what analysts think Select Water Solutions's shares could be worth.
The issue now is whether Select Water Solutions' current share price around US$19.48 is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether Select Water Solutions at US$19.48 lines up with its earnings, it can help to compare that question across a wider set of 29 high quality undervalued stocks
Is Select Water Solutions Getting Expensive on Earnings?
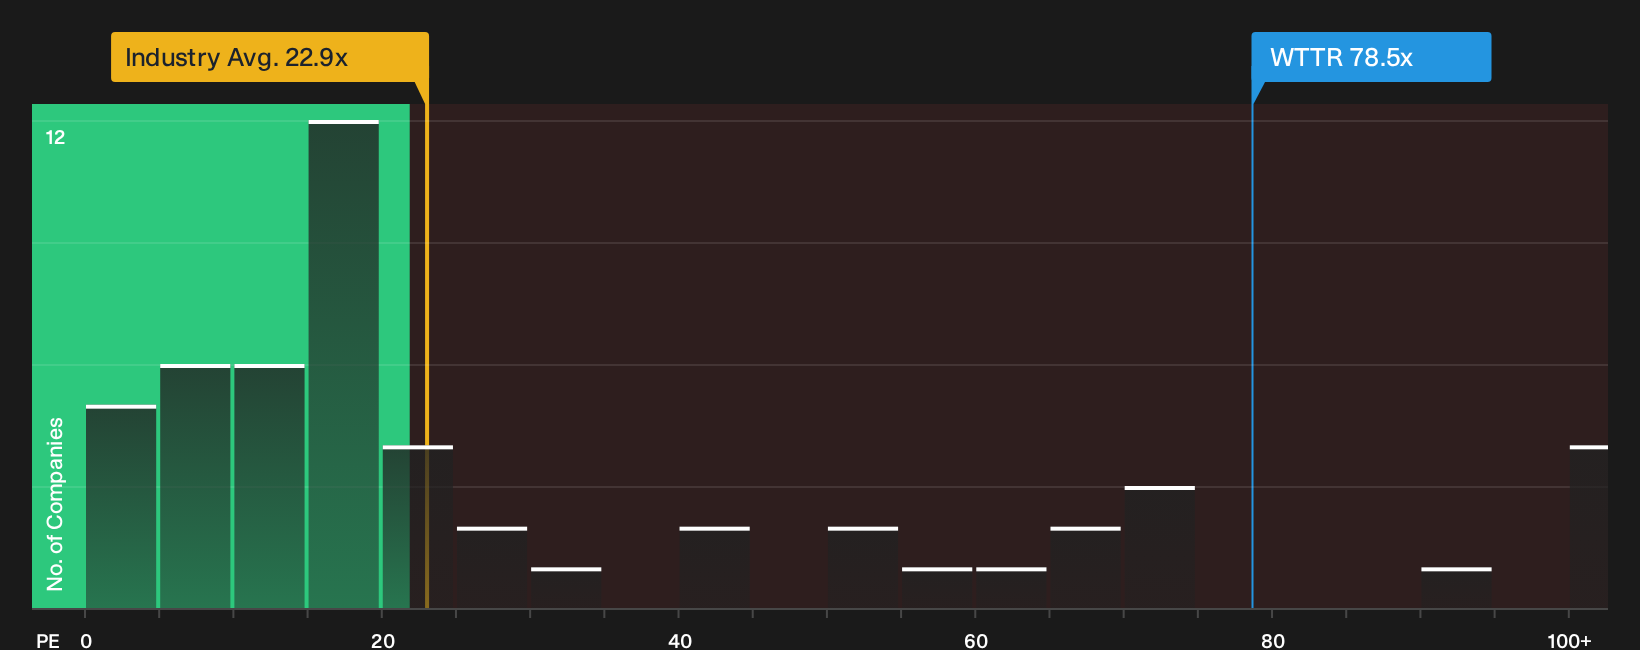
The P/E ratio suits Select Water Solutions because earnings are a central driver for how investors assess Energy Services businesses. At a P/E of 78.5x, the stock is priced well above the Energy Services industry average of 22.9x and ahead of the peer group at 50.9x. That points to a rich earnings multiple where buyers are paying a materially higher price for each dollar of profit than is typical across the sector.
The Fair Ratio framework, which links the appropriate P/E to factors like growth profile, profitability and risk, also sits well below the current 78.5x level, so the shares screen as overvalued on this yardstick. Because the upcoming 9 November 2026 results may update the earnings picture, the current premium P/E already bakes in a lot of optimism before that new information arrives. For anyone tracking valuation, the size of the gap between today’s P/E and the Fair Ratio benchmark is worth checking in detail. Explore the numbers behind Select Water Solutions's P/E valuation.
The Select Water Solutions Narrative: What Would Justify Today's Price?
Narratives for Select Water Solutions pick up where the P/E puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each storyline on Simply Wall St's Community page ties a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of Select Water Solutions' future appears to be taking shape.
One of the top community narratives on Select Water Solutions: 21% undervalued
"The current valuation implies the share price does not fully reflect the company’s mix of long-term, contract-backed water midstream cash flows…"
Discover why this Narrative puts Select Water Solutions at 21% undervalued.
An open question for Select Water Solutions: what are professionals pencilling in next
Valuation only shows what the market is willing to pay today, while analyst projections sketch where they currently expect Select Water Solutions to be a few years from now. Explore where analysts expect Select Water Solutions to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com