


EN
Novavax (NVAX) Stock May Be Above Fair Value On Current Sales
Novavax has been through a brutal stretch over the past few years, yet the share price still reflects fresh expectations around its future revenue base. With the stock now trading at US$10.02, the key issue for you is how that price lines up with the sales the company is actually generating and what investors expect it to deliver.
- The share price has fallen 94.9% over the past 5 years, which puts the focus squarely on whether the remaining valuation is now mostly about current sales or still heavily about hoped for future revenue.
- The business model is highly dependent on turning its vaccine portfolio into a steadier stream of product sales, which can shape how much investors are prepared to pay for every dollar of revenue today.
- The analysts covering Novavax have run their own numbers. See what analysts think Novavax's shares could be worth.
The issue now is whether the current Novavax share price is justified by its sales base and the revenue profile investors are implicitly paying for.
If you are weighing whether Novavax at US$10.02 still makes sense on its sales profile, it can help to compare it with a focused list of 29 high quality undervalued stocks.
Is Novavax Getting Expensive on Sales?
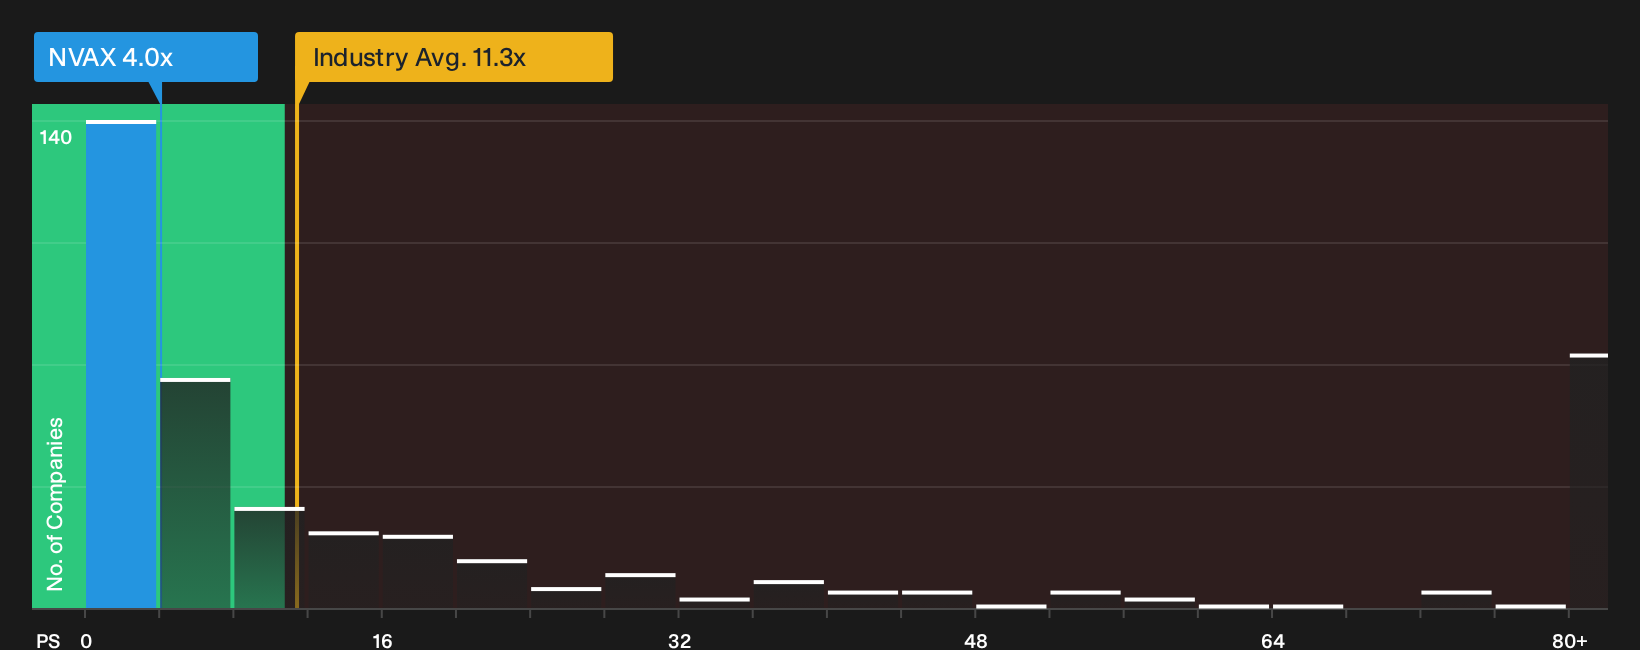
P/S is a cleaner yardstick for Novavax because earnings are distorted by recent losses, while sales give you a more direct read on what the market is paying for its vaccine revenue stream. On this measure, the stock trades on a P/S of 4.0x, which is well below the Biotechs industry average of 11.3x and also below the peer group on about 28.9x. Those raw gaps indicate that the market is paying less for each dollar of Novavax revenue than it does for many other drug developers.
The fair multiple that emerges from the valuation model, after weighing Novavax specific growth assumptions, margins, size and risk profile, is lower than the current 4.0x. That puts the P/S ratio on the overvalued side of that tailored benchmark, even though it still appears cheaper than many industry comparisons. For you as a shareholder or potential buyer, the key question is whether the revenue outlook and risk level you see in Novavax justify paying a higher P/S than that model suggests is comfortable. Explore the numbers behind Novavax's P/S valuation.
The Novavax Narrative: What Would Justify Today's Price?
Novavax's valuation puzzle only really comes into focus when you line up the current P/S tag against explicit stories about what happens to its future growth, profitability and risk profile. Narratives on Simply Wall St's Community page do exactly that by tying each implied number to a clear view on how Novavax's revenue trajectory, margins and uncertainty could evolve. This gives you a reference point you can revisit as fresh information comes through.
Community views on Novavax split between those who see a lean royalty engine forming and those who focus on a fragile revenue base.
Bull case: 60% undervalued
"Planned reduction of combined non GAAP R&D and SG&A to a range of US$150 million to US$200 million by 2028, alongside paying down pandemic era APA liabilities by early 2029, means that incremental royalties and milestones from existing and new Matrix M programs drop into a much leaner cost structure than in prior years…"
Discover why this Narrative puts Novavax at 60% undervalued.
Bear case: 43% overvalued
"While Novavax is broadening Matrix M collaborations with several large pharmaceutical partners, the sharp fall in reported quarterly revenue to US$57 million, with heavy reliance on irregular milestone payments, suggests that any delay or downsizing of these partnered programs could leave royalty and milestone income insufficient to stabilize revenue or support earnings…"
Explore why this Narrative puts Novavax at 43% overvalued.
Novavax's valuation story is only half complete without one more piece
You have a snapshot of what the market pays for Novavax today, but professional projections a few years out offer a different lens on how that pricing stacks up against expected business performance. Explore where analysts expect Novavax to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com