


EN
What You Need to Know Ahead of Applied Materials’ Earnings Release
With a market cap of $307.6 billion, California-based Applied Materials, Inc. (AMAT) is a leading semiconductor equipment and materials engineering company that develops, manufactures, and services the advanced machinery used to produce computer chips and electronic displays. Its technologies support critical chipmaking processes, including material deposition, etching, inspection, and wafer packaging.
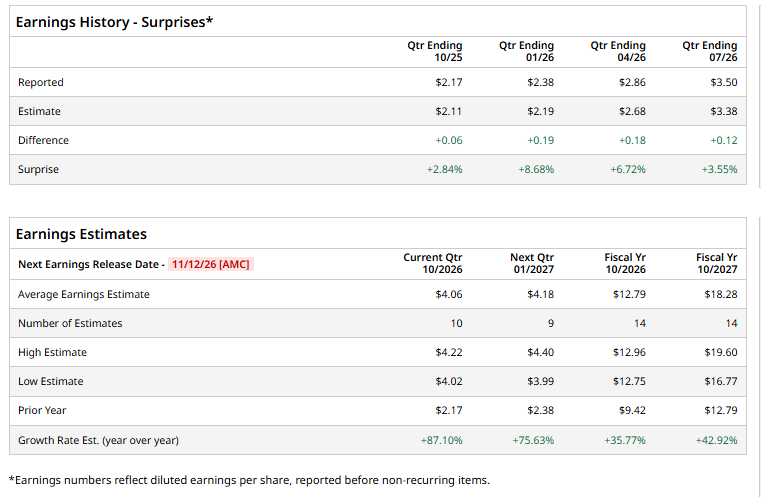
The chip giant is slated to announce its fiscal Q4 2026 results after the market closes on Thursday, Nov. 12. Ahead of this event, analysts expect AMAT to report an adjusted EPS of $4.06, an 87.1% growth from $2.17 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in each of the past four quarters.
For fiscal 2026, analysts predict the semiconductor equipment maker to post adjusted EPS of $12.79, a rise of 35.8% from $9.42 in fiscal 2025. In addition, adjusted EPS is expected to increase 42.9% year over year to $18.28 in fiscal 2027.
Shares of Applied Materials have climbed 71.2% over the past 52 weeks, outpacing the broader S&P 500 Index's ($SPX) 12.3% gain and the State Street Technology Select Sector SPDR ETF's (XLK) 26.8% return over the same period.
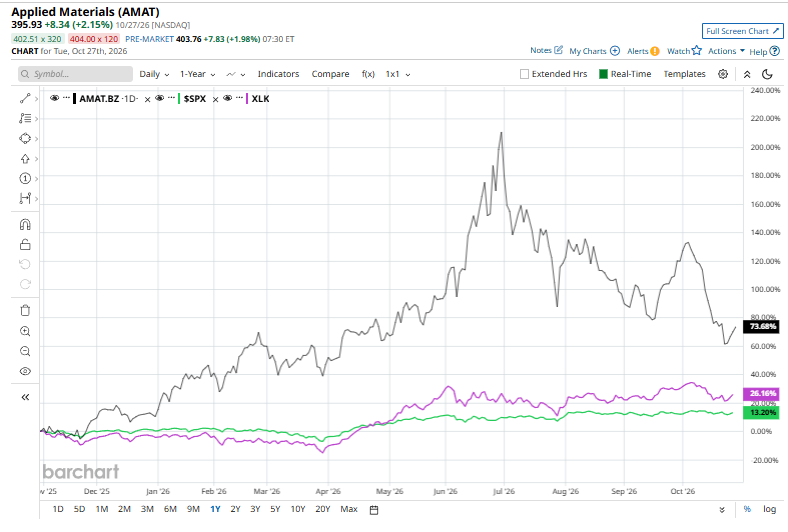
Applied Materials has outpaced the broader market over the past year as the AI infrastructure boom has fueled demand for advanced semiconductor manufacturing equipment. The company has benefited from record quarterly revenue and earnings, stronger investment in high-bandwidth memory (HBM), leading-edge chips and advanced packaging, and an improved growth outlook.
Another key catalyst has been management’s repeated upgrades to its outlook as chipmakers ramp up capital spending. Applied Materials expects to outperform the wafer fab equipment market through 2030, driven by surging AI infrastructure investment and rising demand for advanced chips. The company aims to gain more than 2 percentage points of market share by leveraging its strong positions in leading-edge logic, DRAM, and advanced packaging. It also expects service revenue to exceed $12 billion by 2030 and is expanding R&D and manufacturing capacity to capitalize on long-term semiconductor growth.
Analysts' consensus view on AMAT stock remains very bullish, with an overall "Strong Buy" rating. Out of 37 analysts covering the stock, 26 recommend a "Strong Buy," three "Moderate Buys," and eight give a "Hold" rating. The average analyst price target is $635.70, indicating a potential upside of 60.6% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.