


EN
Prosperity Bancshares (NYSE:PB) posts Q3 2026 sales in line with estimates while profit misses
Regional banking company Prosperity Bancshares (NYSE:PB) met Wall Street’s revenue expectations in Q3 2026, with revenue up 57.1% year on year to $495.7 million. Its GAAP profit of $1.18 per share was 13.8% below analysts’ consensus estimates.
For more on Prosperity Bancshares, read our free full research report.
Prosperity Bancshares (PB) Q3 2026 highlights:
- Net interest income $443 million vs analysts’ consensus estimates of $442.3 million (62% year-on-year growth, in line)
- Net interest margin 3.7% vs analysts’ consensus estimates of 3.7% (5.8 basis point beat)
- Revenue $495.7 million vs S&P analysts’ consensus estimates of $497 million (57.1% year-on-year growth, in line)
- Efficiency ratio 62.1% vs analysts’ consensus estimates of 49.5% (1,256 basis point miss)
- EPS (GAAP) $1.18 vs analysts’ consensus estimates of $1.37 (13.8% miss)
- Tangible book value per share $39.71 vs analysts’ consensus estimates of $40.22 (8.1% year-on-year decline, 1.3% miss)
- Market capitalization $8.37 billion
"These increases primarily reflect our three recent mergers. We are highlighting their magnitude because they demonstrate the expertise of our associates, who have extensive experience executing acquisitions and integrating the acquired institutions. Our greater scale strengthens our competitiveness, improves efficiency, and enables technology investments that would be difficult for a smaller bank," continued Zalman.
Revenue growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management and trading operations provide additional income. Prosperity Bancshares’s revenue grew at a tepid 6.4% annualized rate over the last five years, falling short of our standard for the banking sector.
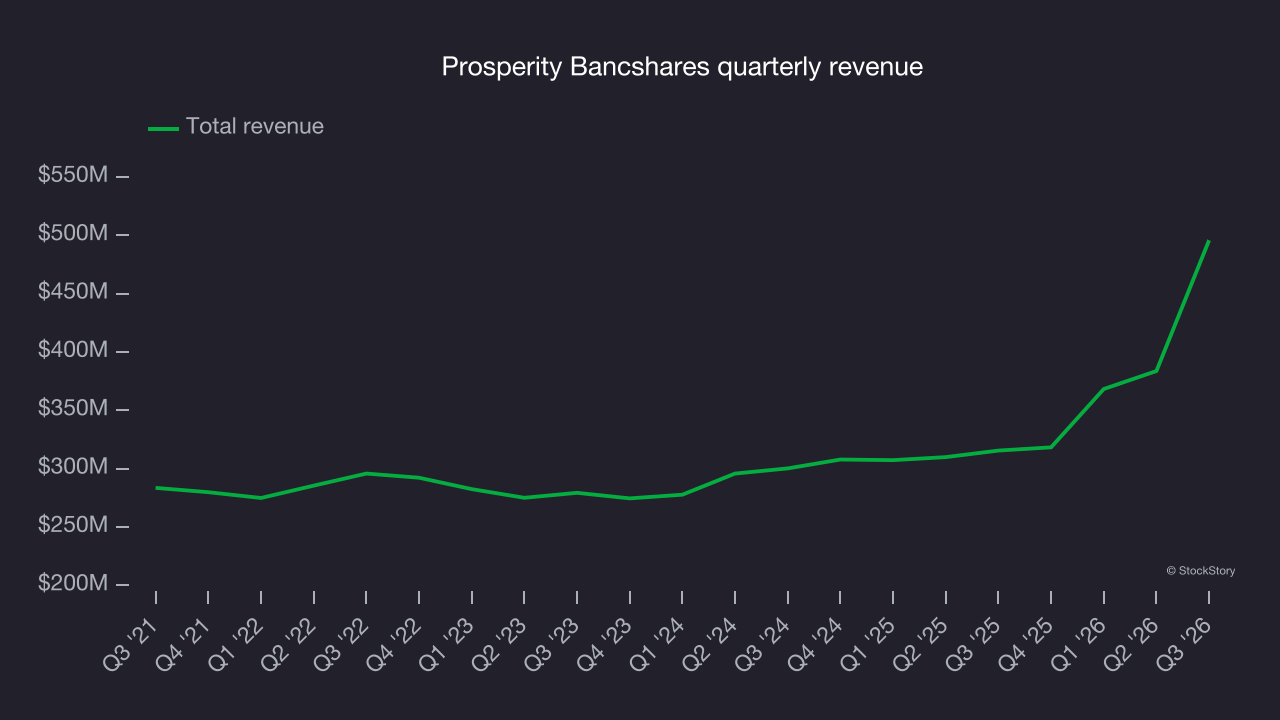
Long-term growth matters the most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Prosperity Bancshares’s annualized revenue growth of 16.8% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 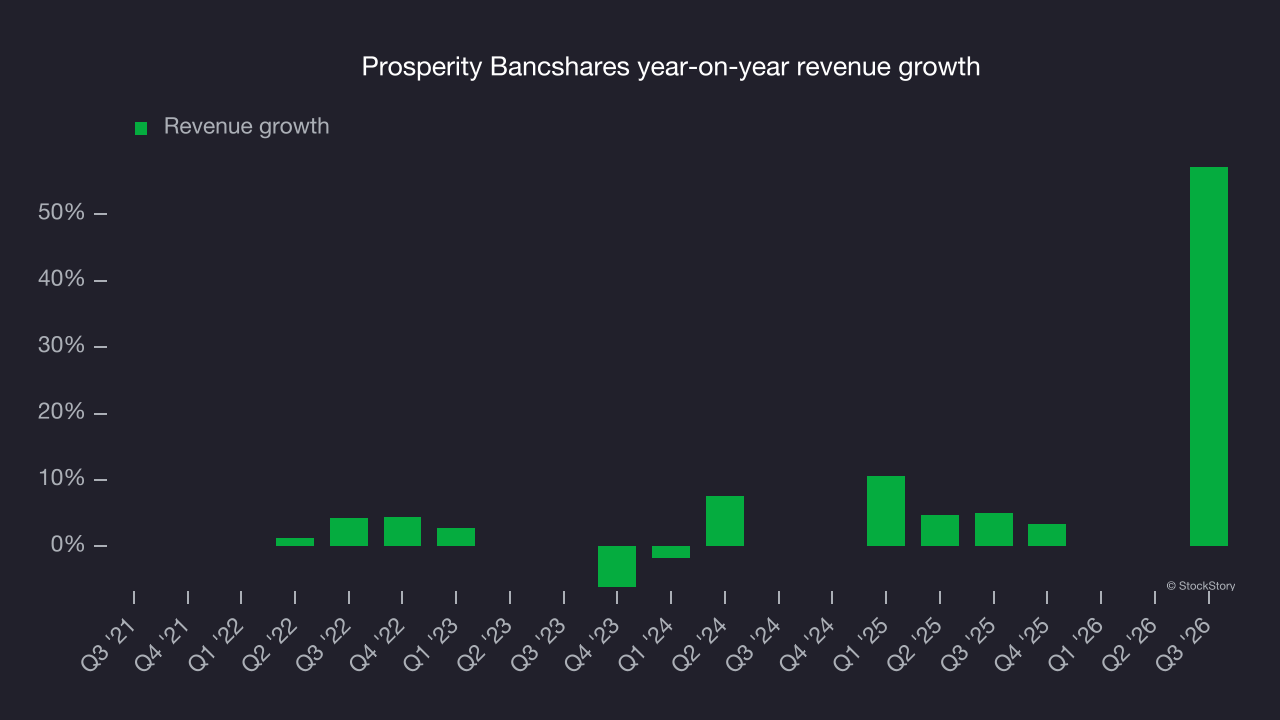 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Prosperity Bancshares’s year-on-year revenue growth of 57.1% was strong, and its $495.7 million in revenue was in line with Wall Street’s consensus estimates.
Net interest income made up 86.9% of the company’s total revenue during the last five years, meaning Prosperity Bancshares barely relies on non-interest income to drive its overall growth.
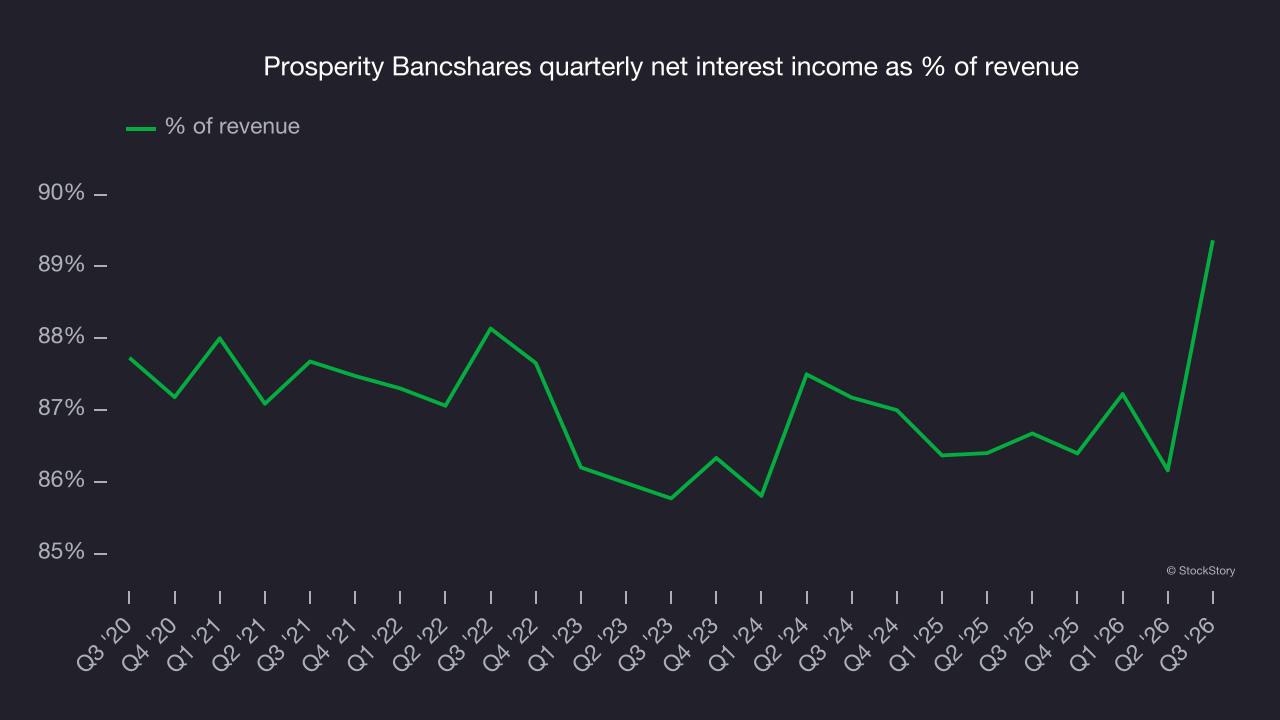
Markets consistently prioritize net interest income growth over fee-based revenue, recognizing its superior quality and recurring nature compared to the more unpredictable non-interest income streams.
Tangible book value per share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates underlying per-share value by removing intangible assets of uncertain liquidation value. EPS can be clouded by acquisition effects or accounting flexibility around loan provisions, while TBVPS is less susceptible to financial engineering.
Prosperity Bancshares’s TBVPS grew at a tepid 3.7% annual clip over the last five years. TBVPS growth has also decelerated recently as it was flat over the last two years at roughly $39.71 per share.
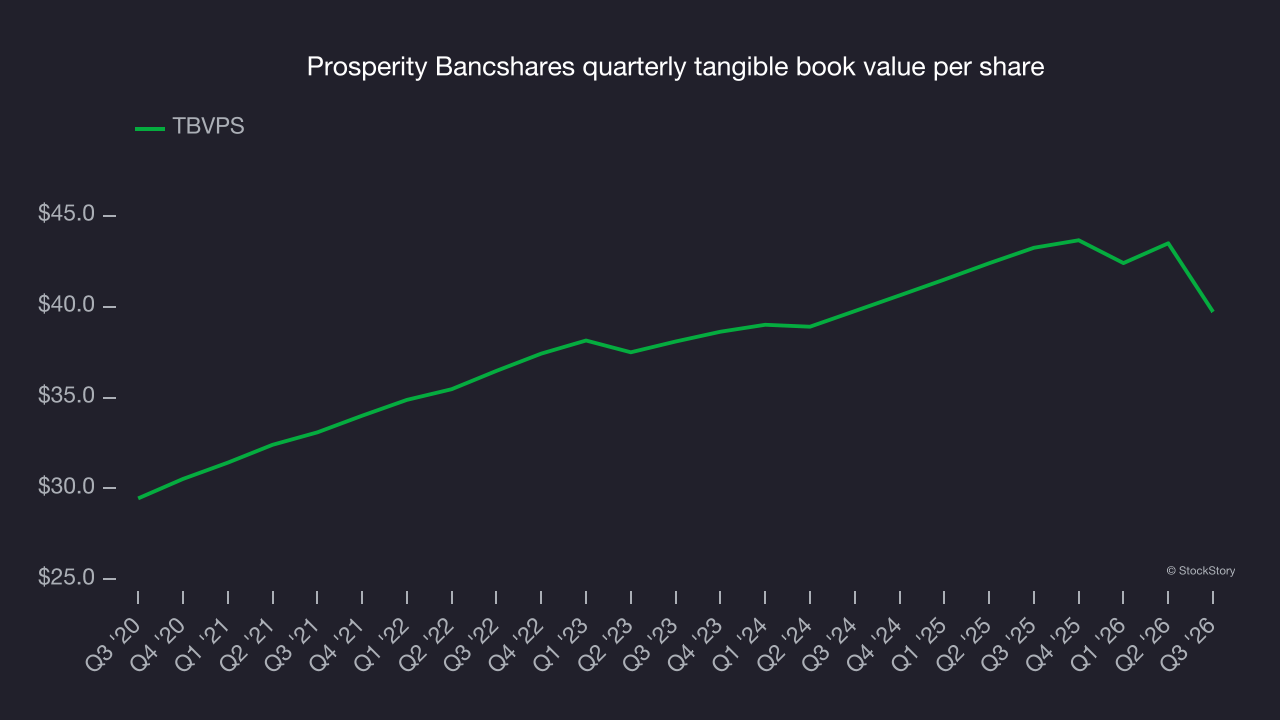
Over the next 12 months, consensus estimates call for Prosperity Bancshares’s TBVPS to grow by 12.6% to $44.73, a decent growth rate.
Key takeaways from Prosperity Bancshares’s Q3 results
EPS and tangible book value per share both fell short of Wall Street’s consensus estimates, with the latter missing only slightly. That left few positives in a quarter that could have been better. Shares remained flat at $69.53 immediately after the results.
Prosperity Bancshares may have had a tough quarter, but assessing whether the stock offers an investment opportunity requires a broader look at its valuation, business quality and latest earnings. For more on those factors, read the full research report here (it’s free).