


EN
Walt Disney Earnings Preview: What to Expect
Burbank, California-based The Walt Disney Company (DIS) is a global entertainment and media conglomerate that operates through three primary segments: Entertainment, Sports, and Experiences. Valued at $190.6 billion by market cap, its portfolio includes Disney, Pixar, Marvel, Lucasfilm, ABC, ESPN, Disney+, and Hulu. The company generates revenue through film and television production and distribution, streaming subscriptions, advertising, sports broadcasting, theme parks, resorts, cruise lines, and consumer merchandise.
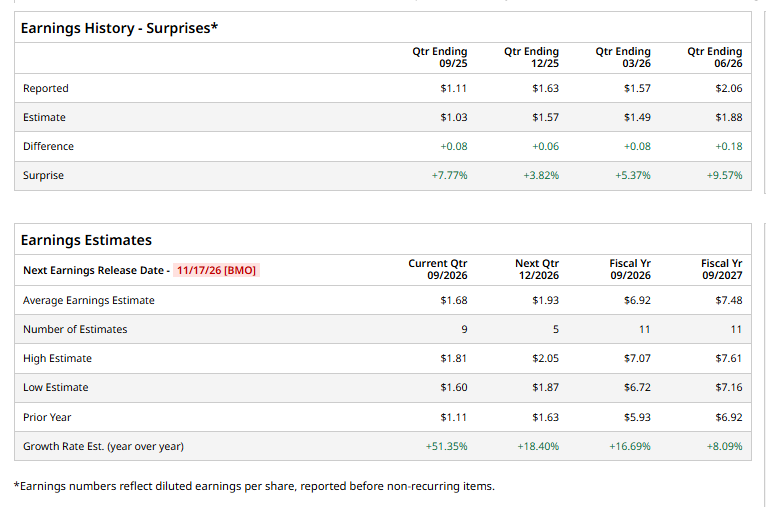
The entertainment giant is expected to announce its fiscal fourth-quarter earnings for 2026 before the market opens on Tuesday, Nov. 17. Ahead of the event, analysts expect DIS to report a profit of $1.68 per share on a diluted basis, up 51.4% from $1.11 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the current year, analysts expect DIS to report EPS of $6.92, up 16.7% from $5.93 in fiscal 2025. Its EPS is expected to rise 8.1% year over year to $7.48 in fiscal 2027.
DIS stock has declined 1.9% over the past year, underperforming the S&P 500 Index’s ($SPX) 12.3% gains. However, it has outpaced the State Street Communication Services Select Sector SPDR ETF’s (XLC) 11.6% decline over the same time frame.
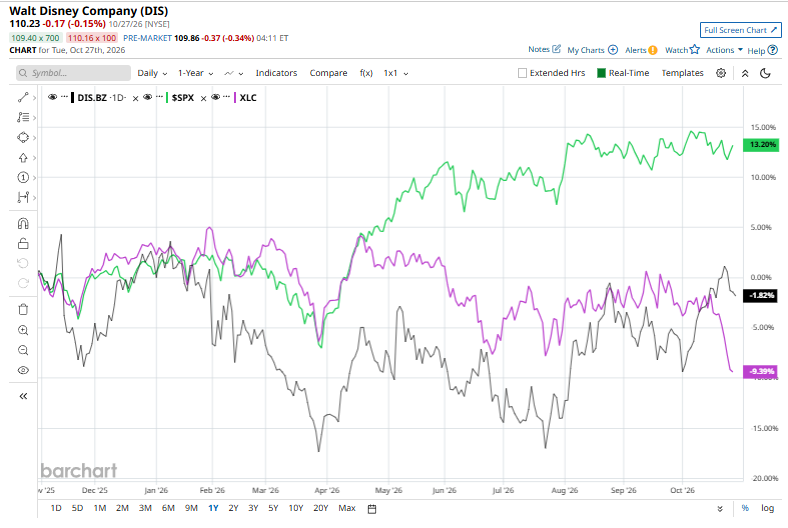
Although Disney has trailed the S&P 500 over the past year, it has outpaced the broader communications services sector, showing relative resilience amid industry headwinds. Under CEO Josh D’Amaro, the entertainment giant is doubling down on cost discipline, with a third round of layoffs since March 2026 and a potential television overhaul aimed at streamlining operations and strengthening its streaming business. These moves could help Disney rein in expenses and redirect resources toward long-term growth as traditional TV audiences dwindle and streaming competition intensifies.
Moreover, Disney has emerged as a stalking-horse bidder for select Character.AI intellectual property in a $20 million deal that includes transition support, potentially giving the entertainment giant an affordable way to expand its conversational AI capabilities. The move could help Disney develop interactive character experiences, access AI talent, and create new growth opportunities by combining its iconic intellectual property with emerging technology.
Analysts’ consensus opinion on DIS stock is very bullish, with a “Strong Buy” rating overall. Out of 33 analysts covering the stock, 24 advise a “Strong Buy” rating, four suggest a “Moderate Buy,” four give a “Hold,” and one recommends a “Strong Sell.” DIS’ average analyst price target is $128, indicating a potential upside of 16.1% from the current level.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.