


EN
Hasbro (HAS) Stock Looks Cheap On Its 192% Three Year Run
Hasbro has been on a striking run, and the question now is whether a share price around US$118 is still anchored to what its cash flows can reasonably justify. After several strong years for the stock and fresh headlines around its gaming arm, the issue for you is whether the current valuation is leaning more on enthusiasm than on the cash that the business is expected to generate.
- Over the past 3 years Hasbro has delivered a total return of 192.1%, which puts a lot of weight on the idea that future cash flows will grow into this higher market value.
- Record sales from Magic: The Gathering and higher expected revenue growth may support stronger cash generation over time, which can change how much investors are willing to pay for each dollar of Hasbro's future cash flows.
- What if you looked at Hasbro through its earnings instead? See why Hasbro's 17.5x P/E tells a different valuation story.
The stock's next move may depend on whether Hasbro's current price is in line with the intrinsic value suggested by its Discounted Cash Flow (DCF) estimate of future cash generation.
If you want a broader watchlist while you assess whether Hasbro's US$118 share price lines up with its cash flows, a focused stock screen is a useful second reference point via 29 high quality undervalued stocks.
Does Hasbro Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach used here projects the cash Hasbro could return to shareholders and then discounts it back to today. On the latest twelve month view, the group generated about $1.1b of free cash flow. This anchors the model in current cash generation rather than just headlines around Magic: The Gathering or the share price move to $118.33.
Analysts feeding into this 2 Stage Free Cash Flow to Equity model expect free cash flow in the next decade to remain in the hundreds of millions of dollars each year, with growth assumptions that are relatively steady rather than explosive. Because the DCF projections put Hasbro's estimated intrinsic value meaningfully above the current share price, the model implies investors are not paying a full price for those projected cash flows at $118.33 today. The raised 2026 outlook, supported by record Magic: The Gathering sales, helps explain why the cash based valuation screens higher than where the stock is trading. Find out what Hasbro could be worth using our Discounted Cash Flow (DCF) estimate.
The Hasbro Narrative: What Would Justify Today's Price?
Hasbro's valuation puzzle only really comes into focus when the story behind the numbers is made explicit. Narratives on Simply Wall St's Community page spell out what would need to be true about Hasbro's future growth, margins and earnings for the shares to trade meaningfully higher or lower than today. Each one turns that view of fair value into a thesis you can track over time, rather than a single dated snapshot.
One of the top community narratives on Hasbro: 5% overvalued
"Accelerating digital gaming revenues and strategic brand collaborations are broadening Hasbro's market reach and creating high-margin, recurring income streams..."
Discover why this Narrative puts Hasbro at 5% overvalued.
One more piece of the Hasbro puzzle that could shift your view
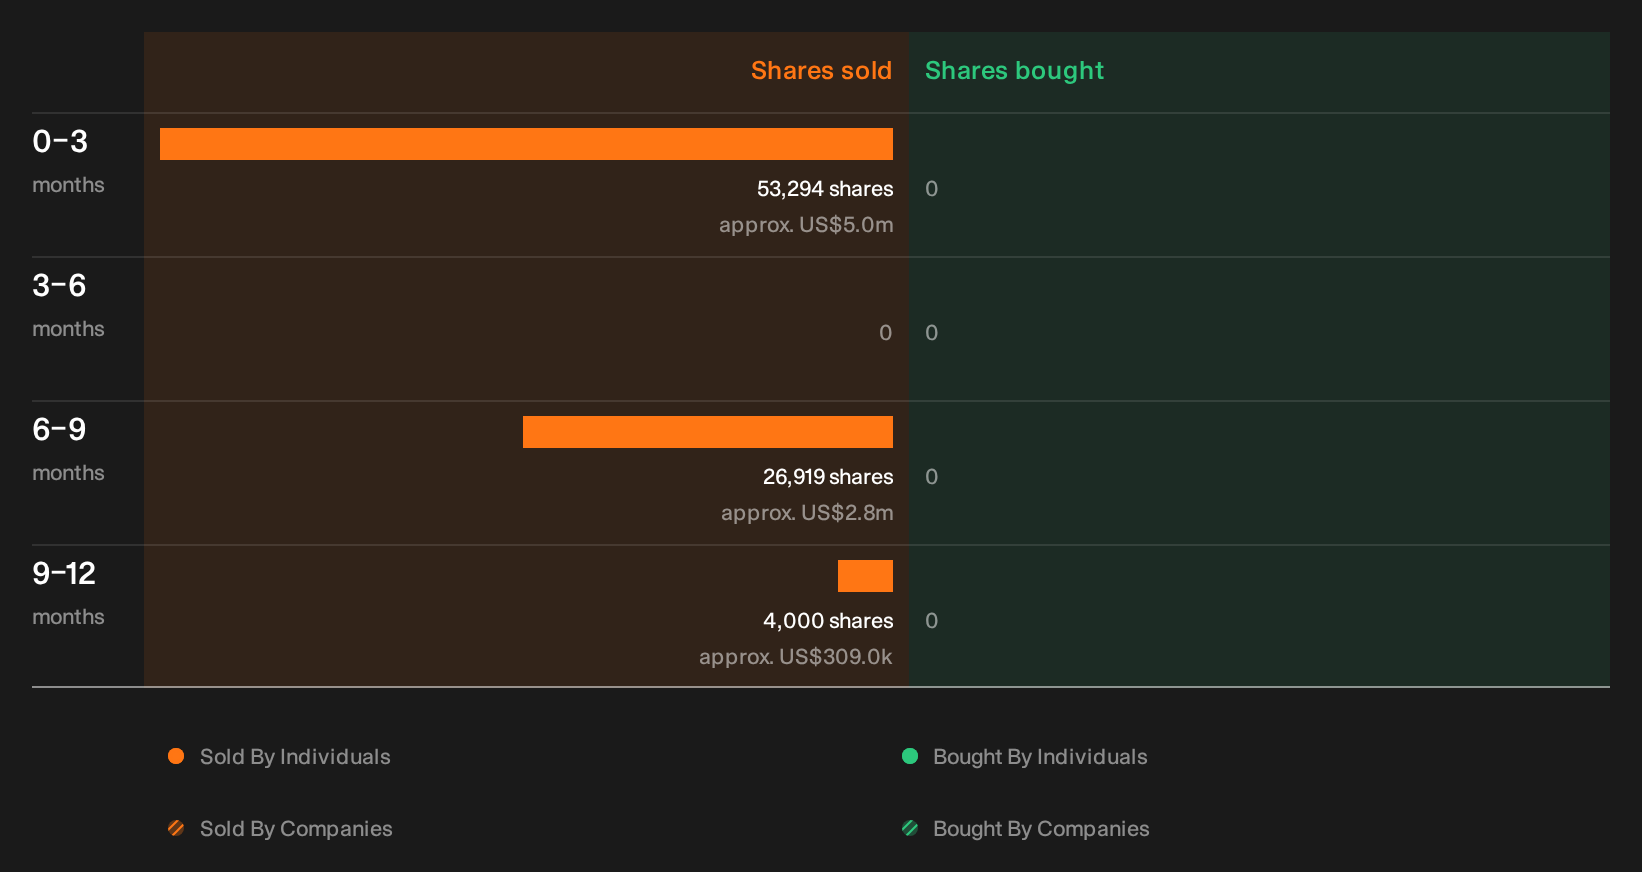
Price and cash flows tell only part of Hasbro's story. Recent share disposals by people inside the business raise a fresh question about behaviour that you can inspect in detail. See the recent insider selling flagged for Hasbro.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com