


EN
Ciena (CIEN) Stock Looks Cheap Even With Strong AI Expectations
Ciena has surged in recent years, and the sharp rise puts a spotlight on a simple question for you as a shareholder or potential buyer. Are the cash flows that the business can produce over time enough to justify where the stock trades today, based on a Discounted Cash Flow (DCF) view of its intrinsic value?
- Over the past 3 years the share price return is very large, which makes it especially important to test whether that move lines up with the long run cash the company can generate.
- Evercore ISI now projects strong long term sales and earnings growth tied to optical networking demand for AI infrastructure, which can support expectations for higher future cash flows if execution and industry trends play out as anticipated.
- What if you looked at Ciena through its earnings instead? See why Ciena's 76.1x P/E tells a different valuation story.
The issue now is whether Ciena's current market price lines up with the stream of cash flows implied by a Discounted Cash Flow (DCF) estimate over the coming years.
If you want to test the same cash flow question across a wider set of AI infrastructure plays, compare Ciena to 55 AI infrastructure stocks.
Is Ciena Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model looks at all the cash Ciena can return to shareholders over time and discounts those amounts back to today. On this view, the business is generating solid cash, with latest twelve month free cash flow of about $849.0 million in dollar terms, and the model assumes that this pool of cash grows from here rather than shrinking.
Projected free cash flow rises into the 2030s in the DCF, which is consistent with a company leaning into a large buildout cycle instead of behaving like a mature, low growth utility. Because Evercore ISI now ties that long term cash generation story to optical networking for AI infrastructure, the valuation model still points to an estimated intrinsic value substantially above today’s $351.15 share price. The recent Evercore call helps explain why expectations for Ciena’s long run cash flows are so strong relative to where the market currently prices the stock. Find out what Ciena could be worth using our Discounted Cash Flow (DCF) estimate.
The Ciena Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ciena pick up where the DCF puzzle leaves you by spelling out which paths for Ciena's growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on the market. Instead of a single output from a ratio or model, they map the future that number leans on so you can watch how Ciena's actual progress matches or departs from that storyline on the Community page.
The community sees the same Ciena story, yet one group thinks the market is underestimating it while the other believes most of the upside is already priced in.
Bull case: 32% undervalued
"Ciena's optical platforms, including RLS, WaveLogic 6 Extreme, pluggables and related interconnect systems, are now tied to a record backlog…"
Discover why this Narrative puts Ciena at 32% undervalued.
Bear case: roughly fairly valued
"Although the company is targeting about 50% gross margin and 32% to 35% operating margin by 2029, the current share price already embeds very large upside…"
Explore why this Narrative puts Ciena at roughly fairly valued.
Ciena’s valuation is only one piece of the picture
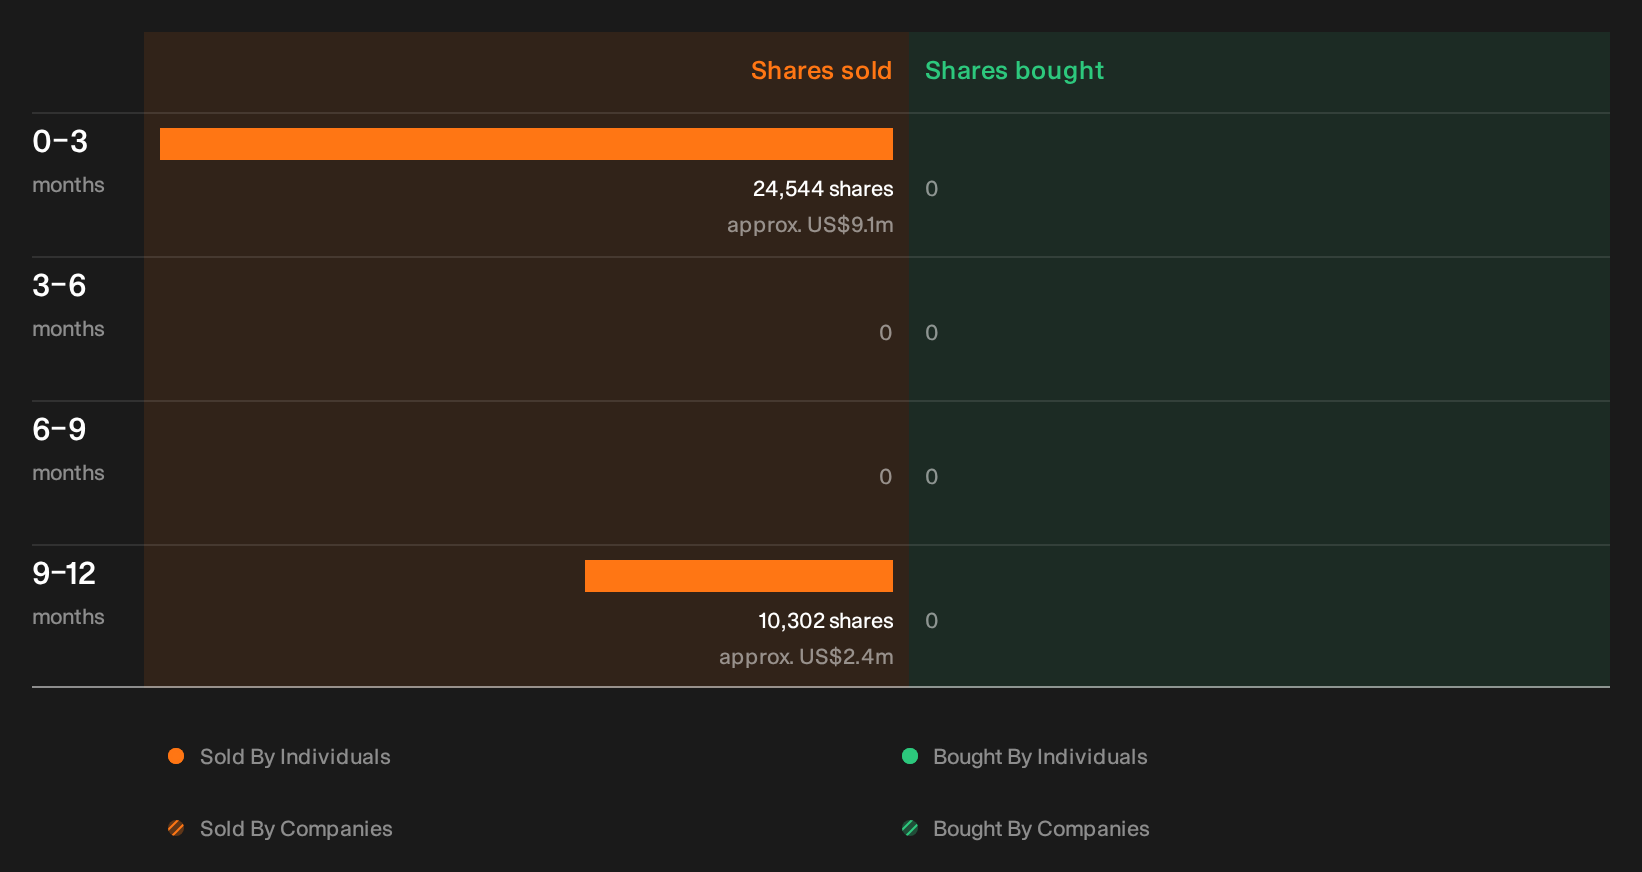
Price, cash flow and market expectations tell part of the Ciena story, yet our checks have also picked up recent insider share sales that deserve a closer look from you. See the recent insider selling flagged for Ciena.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com