


EN
Rogers (ROG) Stock Looks Rich Despite Its 56% One Year Run
Rogers Corporation has delivered a strong 56.4% share price gain over the past year, even as shorter term returns have cooled. This puts fresh attention on whether that climb is supported by the business it earns from its operations. For anyone following Rogers stock today, the live question is how well the current price lines up with the earnings power implied by that move.
- Rogers is up 56.4% over the past year, which puts recent buyers in profit and raises the stakes on whether the earnings profile can carry this valuation.
- The company recently reported higher sales and adjusted earnings, and management now expects further year over year improvement, which can influence how much weight investors give to its current and future profit stream.
- Your read on Rogers is one view; the desks covering it have another. See what analysts think Rogers's shares could be worth.
The stock's next move may depend on whether Rogers' current share price is well supported by the earnings the business is generating today.
If you want to stress test this same earnings driven question beyond Rogers, compare it with other stocks in the 29 high quality undervalued stocks
Does Rogers Look Pricey on Earnings?
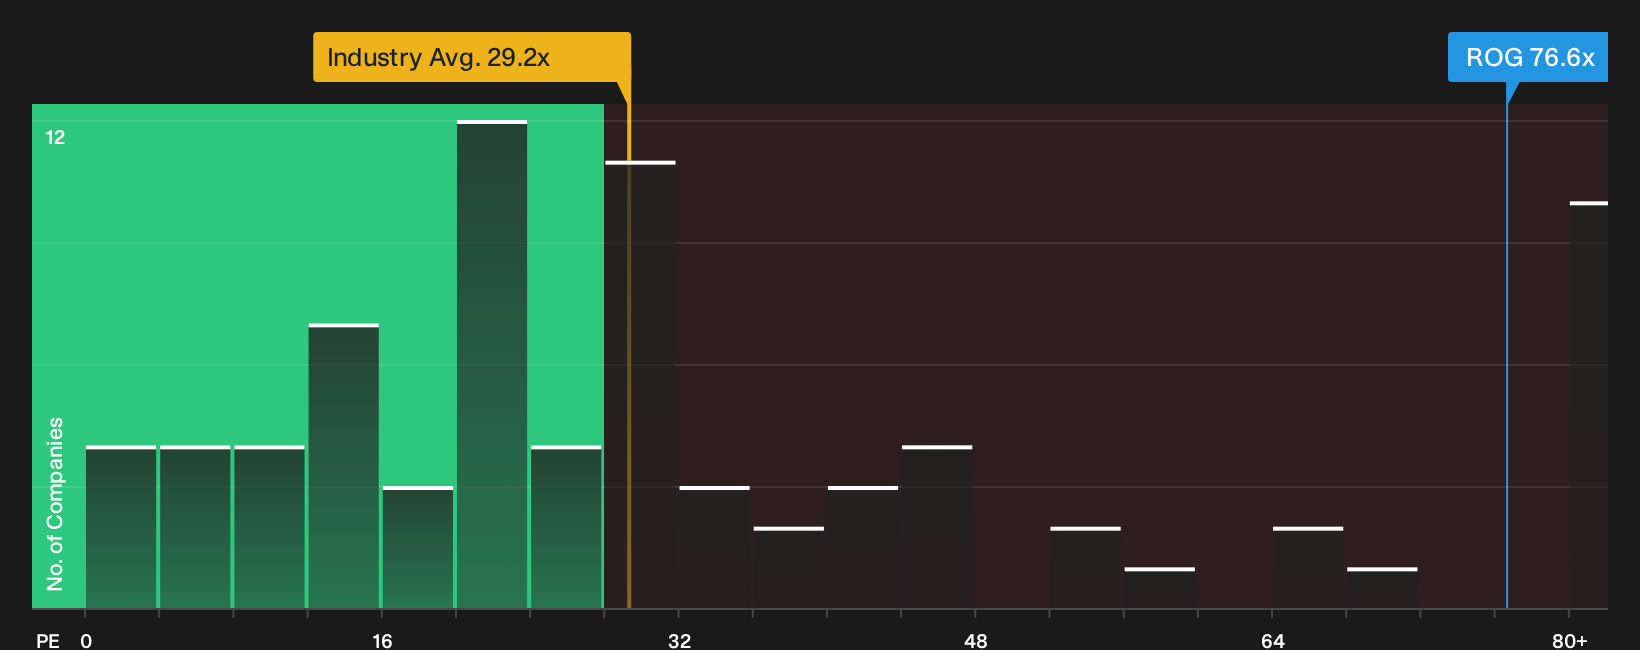
The P/E ratio fits Rogers because earnings are the main anchor for how investors value this kind of electronics manufacturer. Using this lens, the stock trades on a P/E of 76.6x, compared with an industry average of about 29.2x and a peer group average near 65.6x. Buyers today are therefore paying a much higher price per dollar of earnings than is typical in the sector.
Because the P/E investors might expect for Rogers based on its fundamentals screens lower than the current level, the multiple suggests that the shares look overvalued on this framework. The recent report of higher sales and adjusted earnings, plus guidance for further year over year improvement into the fourth quarter of 2026, helps explain why the market is comfortable assigning that premium. However, it still reflects a valuation that builds in a lot of confidence about future earnings power. Explore the numbers behind Rogers's P/E valuation.
The Rogers Narrative: What Would Justify Today's Price?
Narratives on Rogers' Community page pick up where the P/E discussion leaves off and outline which paths for revenue, margins and earnings would need to play out for the valuation to shift meaningfully higher or lower than today's share price. Rather than leaving you with a single output from a ratio or model, they unpack the future those numbers rely on so you can track how Rogers' actual progress compares with those assumptions over time.
One of the top community narratives on Rogers: 31% undervalued
"The main thing that has to go right is that Rogers successfully executes its operating model transformation and capacity ramp, including cost programs…"
Discover why this Narrative puts Rogers at 31% undervalued.
Rogers valuation leaves one big forward looking question unanswered
Rogers stock is priced on what the business is earning today, yet professional coverage also maps out where revenue and profits could be a few years from now. This gives you another lens on whether this price feels stretched or conservative. Explore where analysts expect Rogers to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com