


EN
Leidos (LDOS) Stock May Be 43% Below Fair Value After Cyber Contract Win
Leidos Holdings has delivered a 5 year share price gain while more recent returns have been weaker, which puts the spotlight on whether the current US$139.64 price is still in line with the cash the business can generate. With a series of fresh defense and cyber contracts in hand, the key issue is how those awards translate into long term cash flows that can support today's valuation.
- Over 5 years, Leidos Holdings has returned 51.6%, so a lot of investor capital is already riding on how durable its cash generation proves to be.
- Recent contract wins in U.S. cyber operations, Pentagon logistics and UK defence support may influence expectations for future cash flows and the timing of when that cash arrives.
- Prefer to judge Leidos Holdings on earnings? See what Leidos Holdings's 12.7x P/E says about the price.
The issue now is whether the current share price can be justified by the cash flows implied by a Discounted Cash Flow (DCF) view of Leidos Holdings.
If you want more context around Leidos Holdings and its recent contracts in cyber and AI enabled defense logistics, consider lining it up against 55 AI infrastructure stocks.
Is Leidos Holdings Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Leidos Holdings can return to shareholders over time. Latest twelve month free cash flow sits at about $2.1b, and the projection set assumes free cash flow that broadly holds in a similar billion dollar range rather than moving sharply higher or collapsing.
On those cash flow estimates, the DCF model places Leidos Holdings' estimated intrinsic value substantially above the current US$139.64 share price. Because the recent $160 million U.S. Cyber Command award adds another defined stream of work in a core specialty, the continued gap between cash flow estimates and the traded price suggests the market is still cautious on how durable that contract pipeline proves to be. Find out what Leidos Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The Leidos Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Leidos Holdings pick up where the valuation gap question leaves off, by explaining which paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s market price. Rather than focusing on a single multiple or DCF line, each narrative sets out the key assumptions behind its view of fair value so you can compare those inputs with the firm’s reported numbers over time.
Community views on Leidos Holdings are split between those who see the contract and cash profile as underappreciated and those who think recent enthusiasm already prices in a lot of good news.
Bull case: 8% undervalued
"Leidos continues to run a capital light, cash generative model with CapEx guided to around US$250m or roughly 1 to 1.5% of revenue and strong free cash flow…"
Discover why this Narrative puts Leidos Holdings at 8% undervalued.
Bear case: 10% overvalued
"While the Health business has secured awards like the US$456 million Military OneSource program and the My Service Treatment Record pilot, changes in Veterans Benefits exams, the entry of additional vendors and potential contract restructurings could cap segment revenue growth and keep net margins under pressure even as Leidos invests in new digital platforms…"
Explore why this Narrative puts Leidos Holdings at 10% overvalued.
One more angle on Leidos Holdings that could change how you see the story
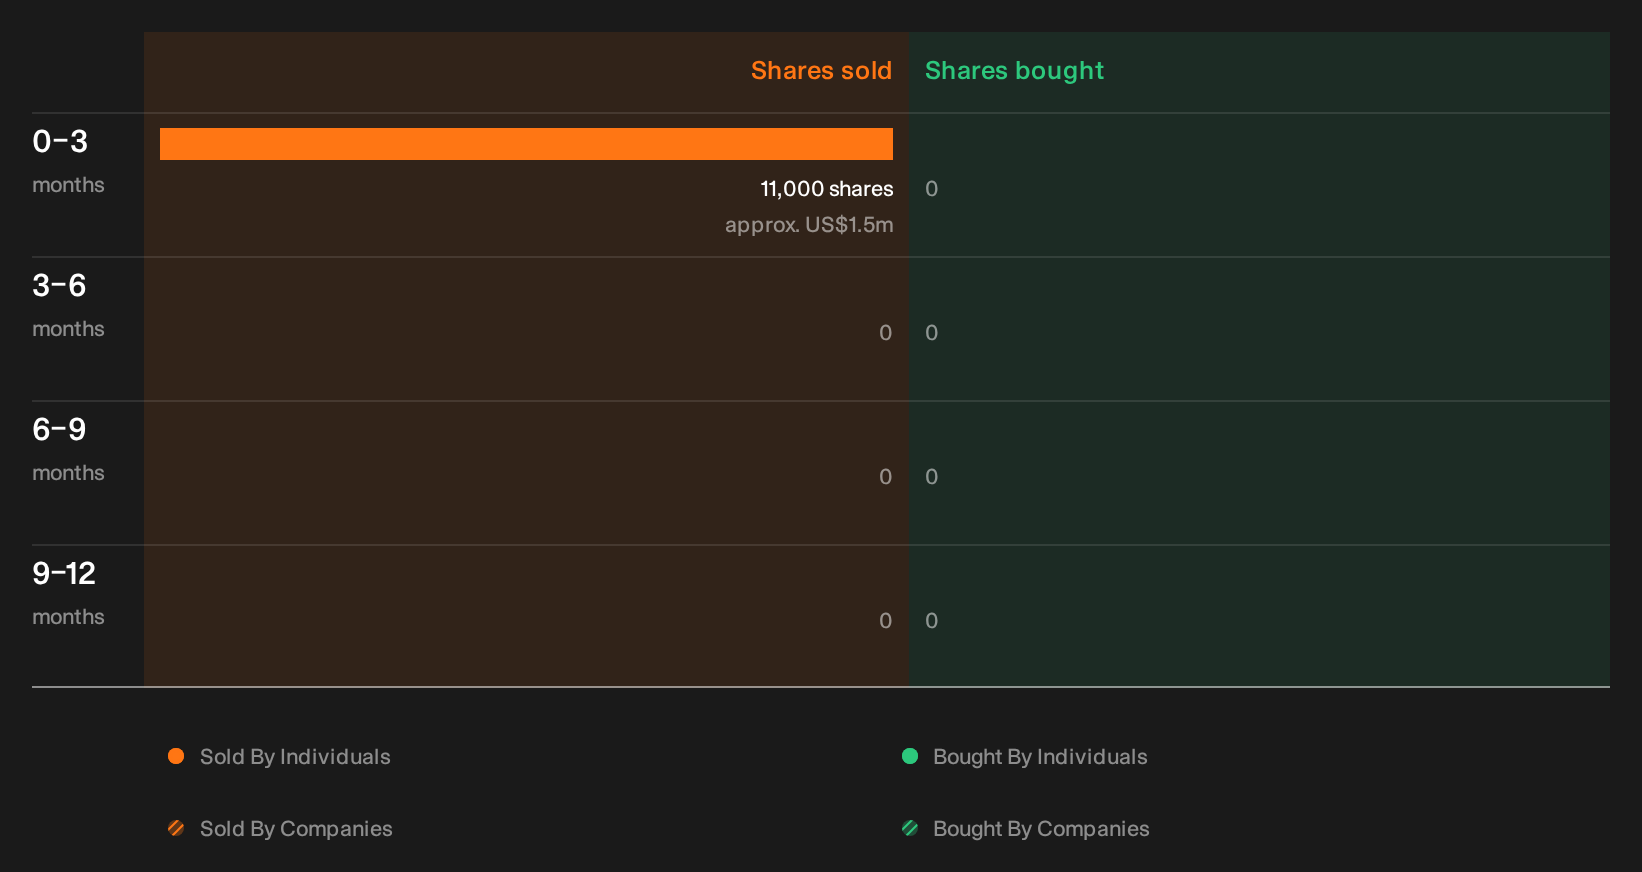
Cash flow, contracts and narratives only tell part of the story. Recent trading activity by people inside Leidos Holdings can add a different signal once you see who sold, how much, and when. See the recent insider selling flagged for Leidos Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com