


EN
Are Earnings Revisions Altering The Investment Case For Kosmos Energy Stock (KOS)?
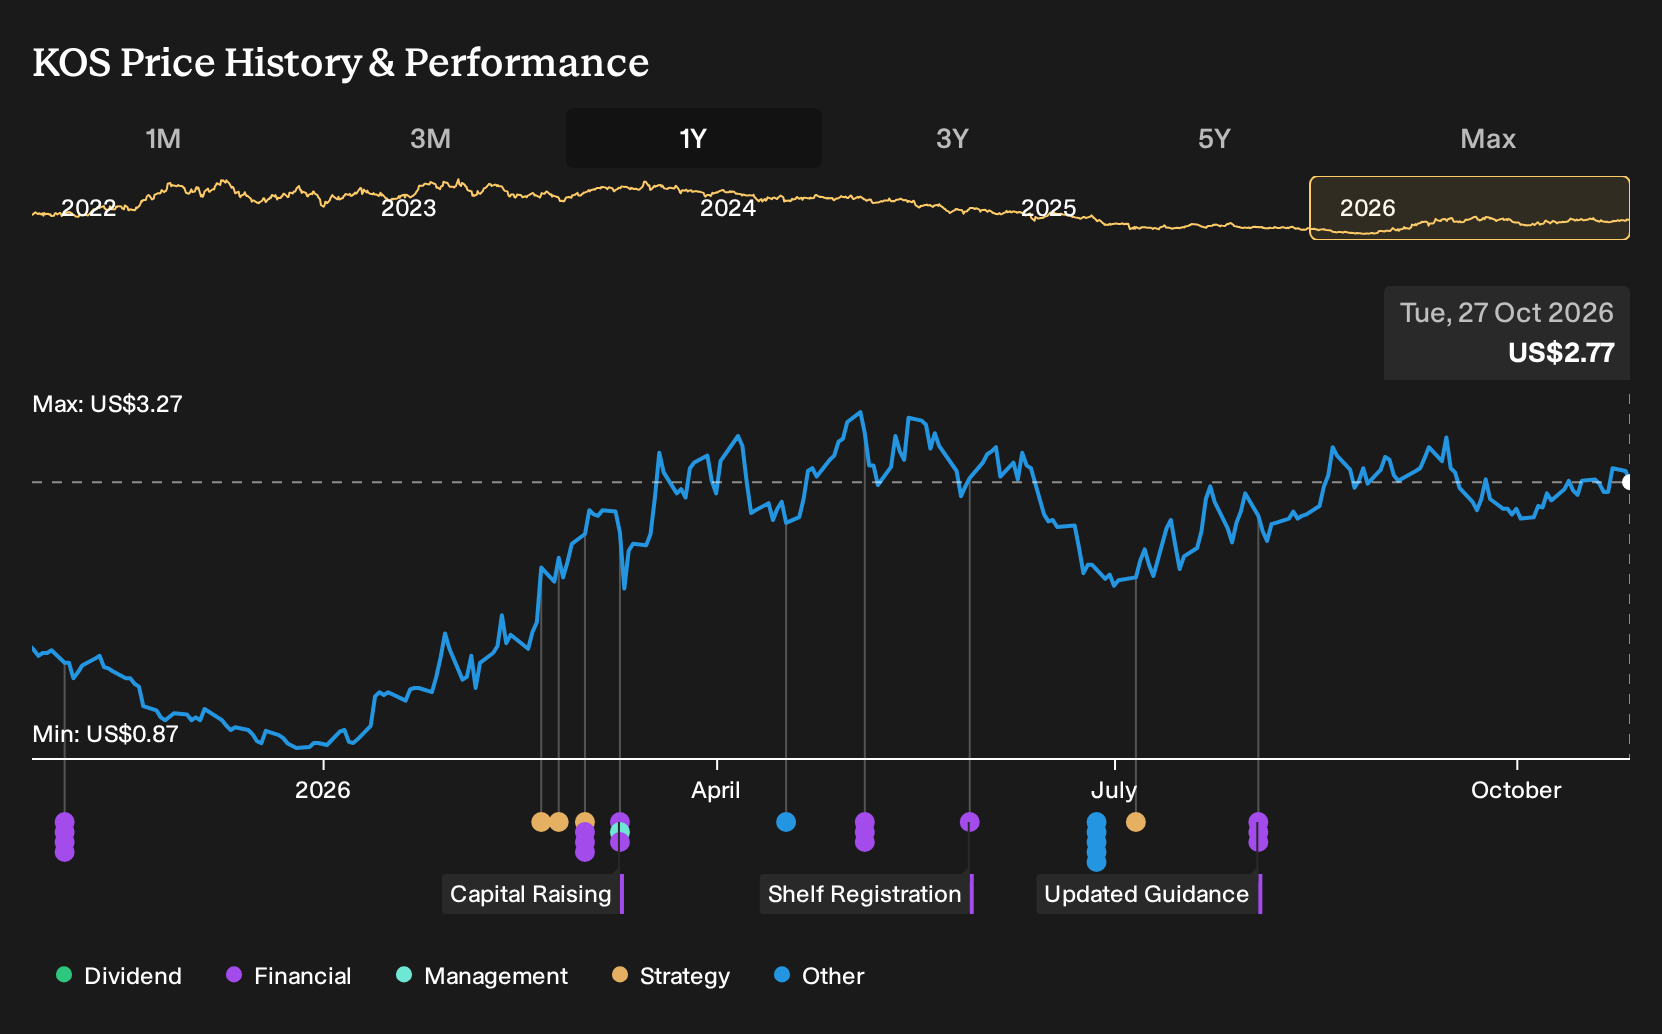
- Kosmos Energy recently attracted attention after upward earnings estimate revisions and strong momentum indicators pointed to improving expectations for its offshore oil and gas portfolio.
- The key question now is whether those higher forecasts align with Kosmos Energy’s push into lower cost projects and more stable cash generation.
- The next focus will be on how Kosmos Energy's upgraded earnings outlook could reshape the existing investment narrative around portfolio high grading.
Track Kosmos Energy's momentum story in context by scanning a hand picked universe of 29 high quality undervalued stocks that combine earnings revisions with stronger price trends.
Kosmos Energy Investment Narrative Recap
To own Kosmos Energy, you need to be comfortable with a simple idea. The business is trying to shift toward lower cost offshore projects while repairing a stretched balance sheet. The short term swing factor remains execution at projects like GTA LNG and Ghana, where production levels, uptime and unit costs will shape how much cash comes through.
The biggest current operational risk sits in higher leverage and project hiccups such as the Winterfell issues and volatility from hedging losses. Fresh momentum signals and higher earnings expectations do not materially change those core risks. They increase the pressure on management to deliver smoother cash generation.
The most relevant update linked to the recent momentum story is the consistent message around cost reduction and portfolio high grading, including the planned acquisition of the TEN FPSO. That move is tied directly to cutting operating costs from 2026, which matters if you are watching whether Kosmos Energy can translate production into steadier free cash flow.
Seen against a strong recent share price run and a high Momentum Style Score, this cost focus becomes a key execution test rather than background noise. If operating expenses at TEN and across Ghana trend lower and GTA LNG hits its targeted operating cost cuts, the upgraded earnings outlook looks more grounded. If not, leverage and cash drain into debt service stay front of mind.
Kosmos Energy Forecast Assumptions in Focus
Analysts are effectively asking investors to square two ideas at once for Kosmos Energy. The first is a shift toward lower cost projects that could help profit margins recover from deep losses. The second is a period where headline revenue is expected to edge down rather than climb.
The current analyst framework builds in revenue that is expected to decline by 1.8% per year over the next 3 years. At the same time, the models assume profit margins move from a loss position of 34.2% today to a small positive margin of 3.1% in 3 years. The core message is simple. Forecasts rely more on better economics per barrel and per MMBtu than on bigger volumes or higher top line.
Earnings expectations underline how sharp that swing would need to be. Analysts see Kosmos Energy moving from a loss of US$542.2 million today to earnings of US$46.0 million by 2029. That is an earnings change of roughly US$588 million. The spread between the most optimistic and most cautious forecasts is wide, with projections ranging from a profit of US$483.6 million to a loss of US$88.9 million, so the implied turnaround carries real debate.
These projections also assume the share count is not static. Analyst models factor in 7.0% annual growth in shares outstanding over the next 3 years, which matters for anyone thinking about per share outcomes rather than just headline profit. A higher share count means each slice of the earnings pie could stay thinner unless absolute profits rise enough to offset that dilution.
The valuation overlay then leans on a much higher P/E multiple than the wider sector. To hit the stated analyst price targets, Kosmos Energy would need to trade on a P/E of 60.9x on the 2029 earnings estimate of US$46.0 million. This compares with a current P/E of 2.8x in loss territory and an industry level cited at 12.3x. A discount rate of 8.78% is used in the Simply Wall St report to pull those future cash flows back into today’s dollars, which highlights how sensitive the story is to both execution and the multiple investors are willing to pay.
Kosmos Energy's narrative projects revenue of about US$1.5b and earnings of US$46.0 million by 2029. This requires a 1.8% yearly decline in revenue and an earnings increase of roughly US$588 million from a loss of US$542.2 million today.
Uncover why Kosmos Energy's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate story around Kosmos Energy revolves around upside from faster margin repair. The most optimistic analysts were already penciling in revenue of about US$1.7b and earnings of roughly US$481.3 million by 2029 before this latest momentum news. Those forecasts paint a far stronger earnings path, so you can use them as one reference point while you weigh how the new information might reshape expectations.
Explore 4 other Kosmos Energy fair value estimates, including one that suggests as much as 656% upside from the current price!
Reach Your Own Conclusion
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your Kosmos Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kosmos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kosmos Energy’s overall financial health at a glance.
Looking for more investment ideas beyond Kosmos Energy?
Once you have a view on Kosmos Energy, it can help to widen the lens and compare it with other companies that fit different risk, income and balance sheet profiles using the Simply Wall St Screener.
- For investors hunting for potentially mispriced opportunities with quality filters already applied, scan a curated set of 29 high quality undervalued stocks that pair stronger fundamentals with more reasonable valuations.
- If resilience and capital protection sit higher on your checklist, focus on companies from the 30 resilient stocks with low risk scores that score better on volatility and business risk metrics.
- When you want sturdier finances underpinning future decisions, concentrate on businesses in the list of solid balance sheet and fundamentals (24 results) where debt levels and liquidity look more robust on key ratios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com