


EN
Exploring Undervalued Small Caps With Insider Activity In October 2026
Over the last 7 days, the United States market has remained flat, yet it has shown a robust 9.2% rise over the past year with earnings forecasted to grow by 17% annually. In this environment, identifying stocks that are potentially undervalued and exhibit insider activity can provide unique opportunities for investors seeking to capitalize on market dynamics.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.5x | 0.5x | 31.58% | ★★★★★☆ |
| Enovis | NA | 0.5x | 37.17% | ★★★★★☆ |
| Union Bankshares | 9.3x | 2.0x | 26.65% | ★★★★☆☆ |
| Tilray Brands | NA | 0.4x | 14.56% | ★★★★☆☆ |
| German American Bancorp | 12.7x | 4.8x | 38.92% | ★★★☆☆☆ |
| Tennant | 61.5x | 0.9x | 21.12% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.6x | 2.6x | 6.97% | ★★★☆☆☆ |
| Chain Bridge Bancorp | 12.7x | 5.1x | 45.96% | ★★★☆☆☆ |
| Bank of Marin Bancorp | NA | 7.1x | 33.18% | ★★☆☆☆☆ |
| Citizens Community Bancorp | 15.6x | 3.8x | 2.58% | ★★☆☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
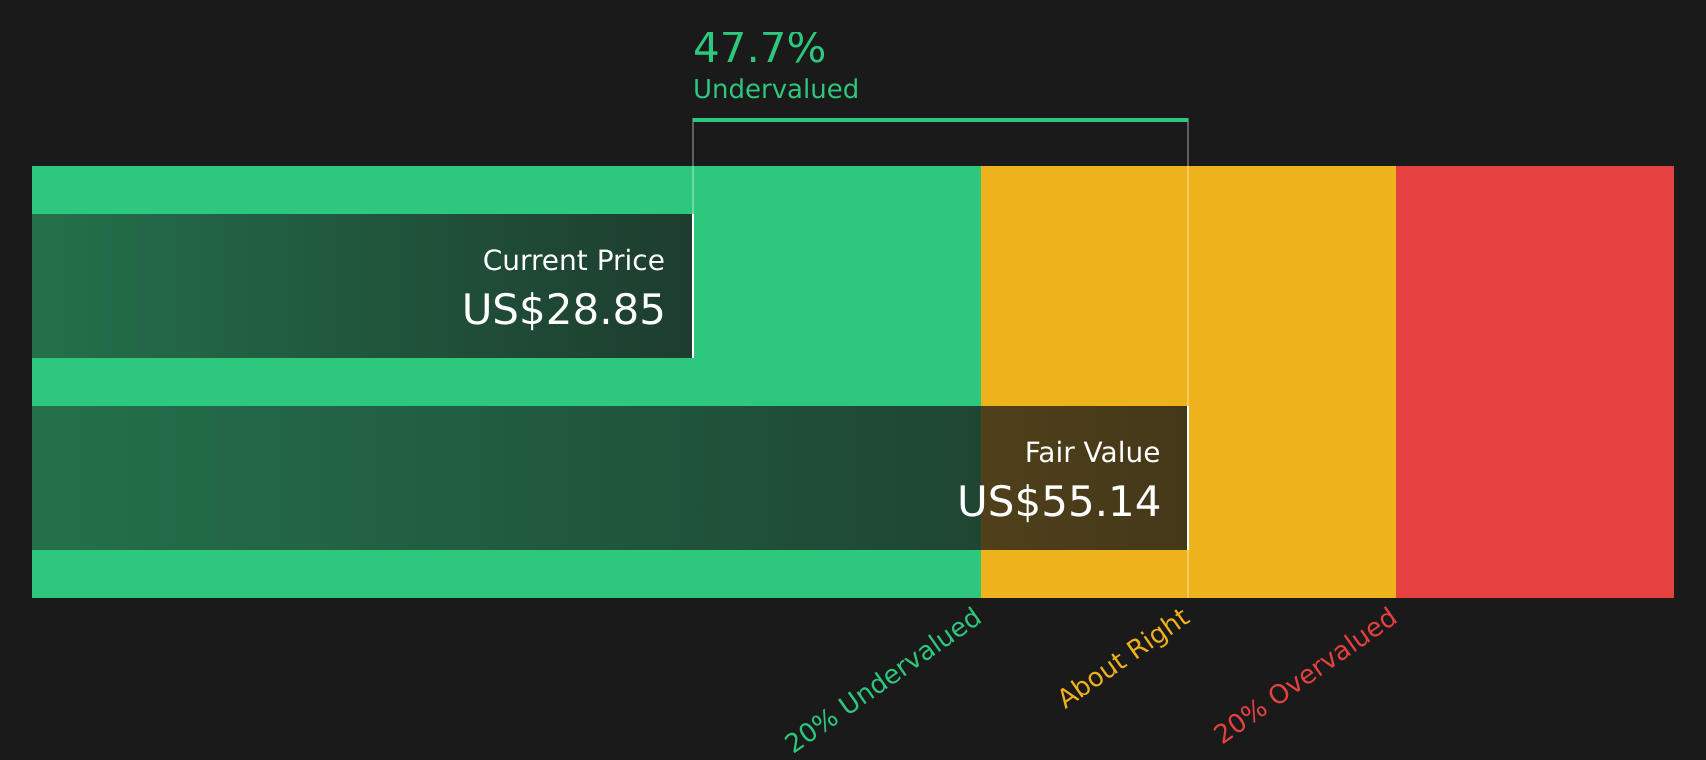
Commercial Bancgroup (CBK)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Commercial Bancgroup is a financial institution that provides a range of banking services, including personal and commercial banking, with a market capitalization of $2.35 billion.
Operations: CBK generates revenue entirely from its gross profit, consistently achieving a gross profit margin of 100%. The company's net income margin has shown an upward trend, reaching 43.11% by September 2026. Operating expenses are primarily driven by general and administrative costs, which amounted to $35.70 million in the same period.
PE: 11.0x
Commercial Bancgroup, a small-cap player in the financial sector, recently reported a solid increase in net income for both the third quarter and nine months ending September 30, 2026. With earnings of US$10.87 million for Q3 compared to US$9.47 million last year, their profitability is on an upward trend. Despite minor net charge-offs of US$41,000 this quarter, insider confidence remains strong with recent share purchases by executives. A stable dividend payout further underscores potential value for investors seeking growth within this segment.
- Take a closer look at Commercial Bancgroup's potential here in our valuation report.
Explore historical data to track Commercial Bancgroup's performance over time in our Past section.
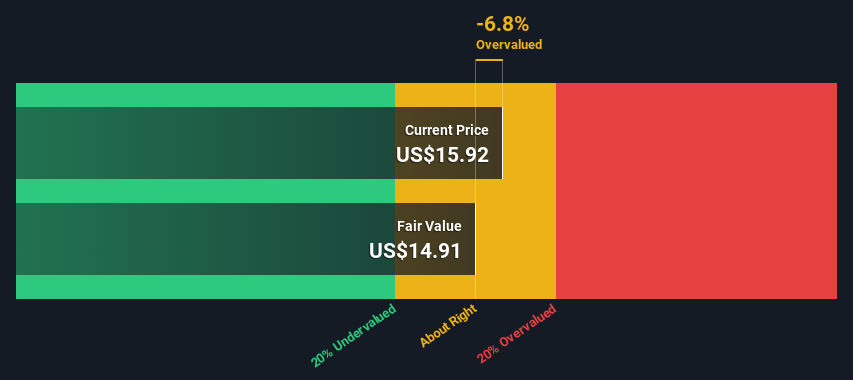
Shore Bancshares (SHBI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Shore Bancshares operates as a community banking organization, providing a range of financial services and products, with a market capitalization of approximately $0.22 billion.
Operations: The company generates revenue primarily from community banking services, with recent quarterly revenue reaching $234.38 million. Operating expenses have been significant, with general and administrative expenses consistently forming a substantial portion of these costs. The net income margin has shown variation over time, recently recorded at 29.27%.
PE: 11.0x
Shore Bancshares, a small financial institution, is demonstrating potential value with earnings forecast to grow 5.11% annually. Recent insider confidence is evident from share purchases within the last quarter, indicating belief in future performance. The company reported increased net interest income of US$55.13 million for Q3 2026 compared to US$48.42 million the previous year and repurchased shares worth US$3.4 million, reflecting strategic capital management despite higher net charge-offs of US$4.8 million this period compared to last year’s $1.8 million.
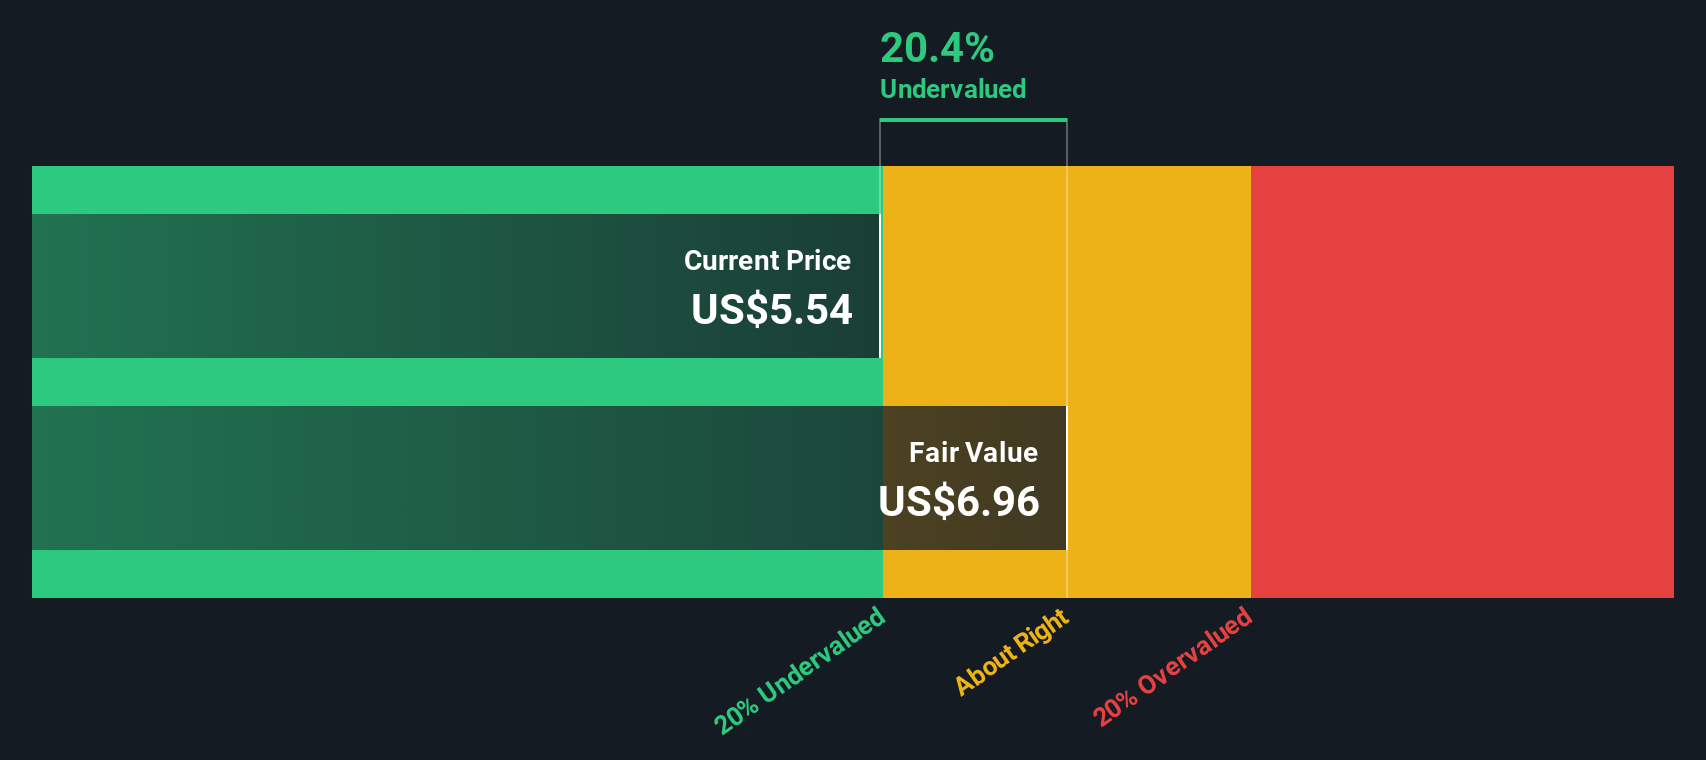
Medical Properties Trust (MPT)
Simply Wall St Value Rating: ★★★★★☆
Overview: Medical Properties Trust is a real estate investment trust focusing on healthcare facilities, with a market capitalization of approximately $4.5 billion.
Operations: The primary revenue stream is from its health care real estate investment trust (REIT) operations, with the latest reported revenue at $1.10 billion. The gross profit margin has shown fluctuations, recently reported at 95.94%. Operating expenses and non-operating expenses have been significant, impacting net income margins which have occasionally turned negative, as seen in recent periods with a net income margin of -0.03%.
PE: -51.4x
Medical Properties Trust, a company operating in the healthcare real estate sector, has shown potential as an undervalued stock. Despite reporting a net loss of US$2.6 million for Q2 2026, this is a significant improvement from the previous year's US$98.36 million loss. The company's recent buyback of 5.8 million shares for US$29.55 million suggests confidence in its future prospects despite challenging financial conditions and reliance on external borrowing for funding needs. A quarterly dividend of $0.09 per share further reflects stability efforts amidst forecasts indicating declining earnings over the next three years.
- Click here and access our complete valuation analysis report to understand the dynamics of Medical Properties Trust.
Understand Medical Properties Trust's track record by examining our Past report.
Where To Now?
- Discover the full array of 66 Undervalued US Small Caps With Insider Buying right here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com