


EN
Ansell And 2 Australian Undervalued Stocks To Watch
Asian shares have been lifted recently by strong enthusiasm for AI focused technology stocks, while oil prices and geopolitics keep making headlines. That mix of excitement and anxiety often pulls investor attention toward momentum stories. It can leave some Australian companies with solid cash flow potential trading quietly at a discount. This article highlights three such opportunities, all identified by a cash flow focused valuation screen.
The three stocks below are just a sample from this idea, as the full cash flow focused screen also surfaced six more businesses with equally compelling valuation stories that are not covered here.
If you want to identify and analyze those extra opportunities alongside your own watchlist, head straight into the Undervalued Stocks Based On Cash Flows screener.
Ansell (ASX:ANN)
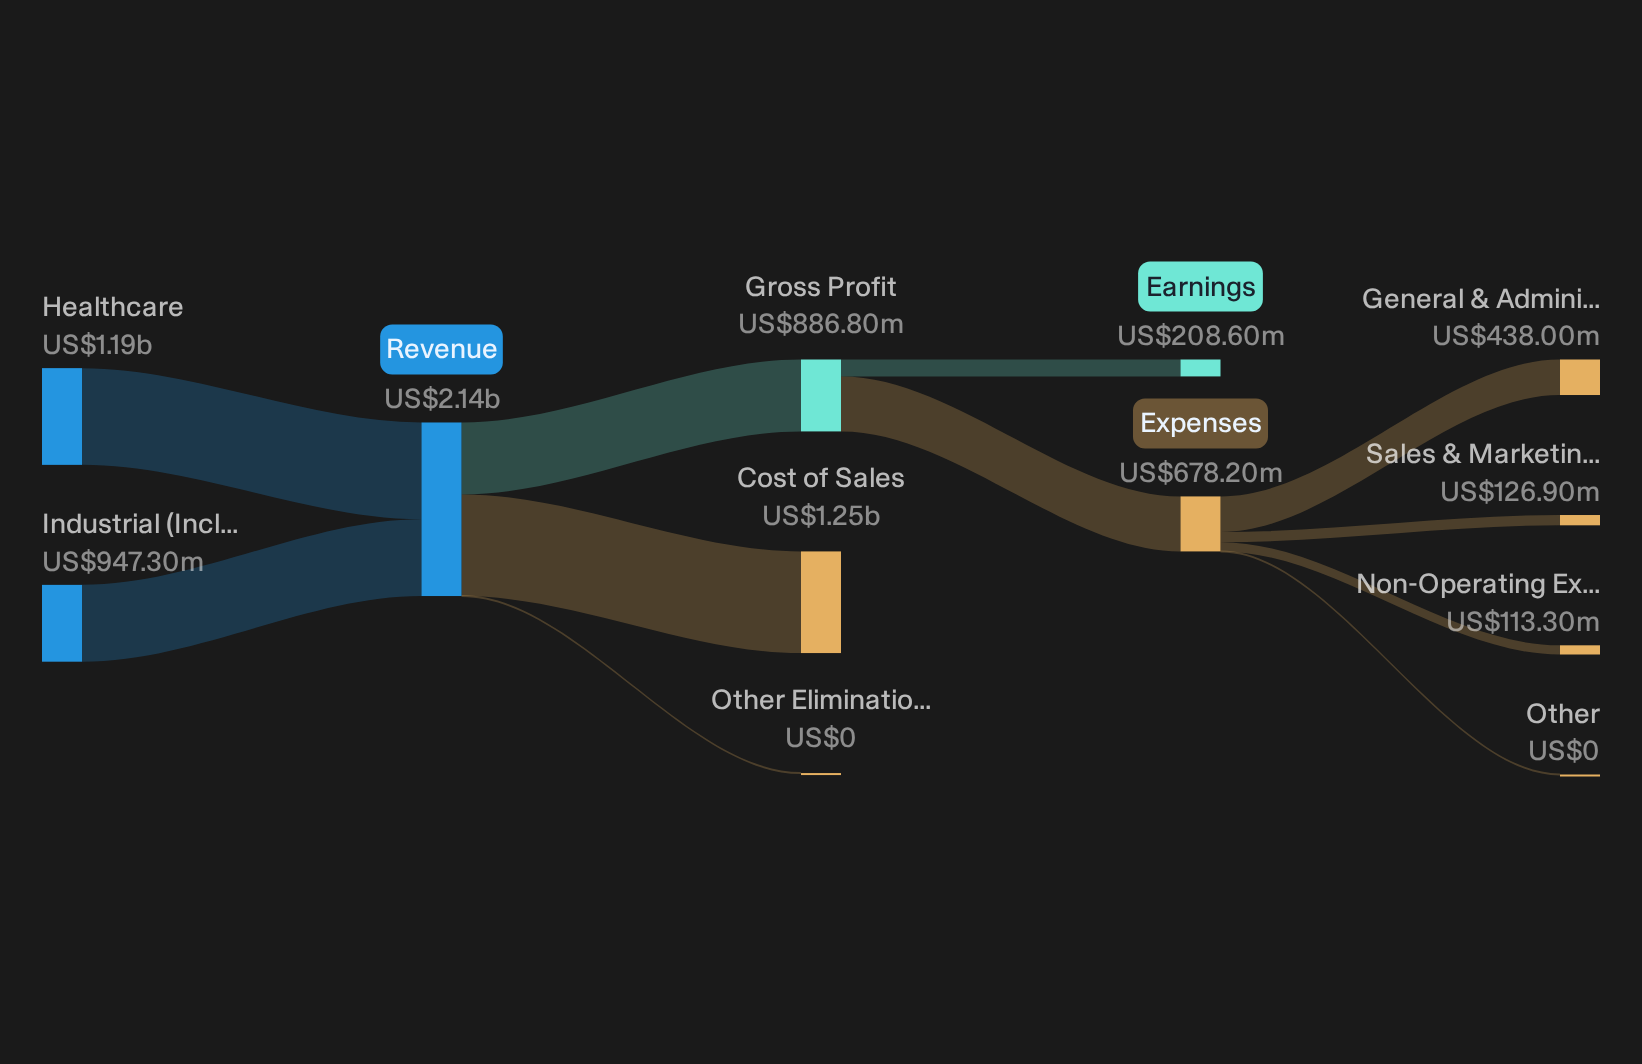
Ansell is a global personal protective equipment specialist whose Healthcare glove and consumables unit fits this cash flow focused screener, with the Healthcare division generating about US$1.2b and Industrial roughly US$947 million in revenue, and the group valued at about A$6.4b by market cap.
Gloves are not just a product line for Ansell, they are a recurring consumable that can underpin steady cash generation and help support a discounted cash flow valuation story when bought at the right price.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
The key question is how one evolving cost pressure ultimately shapes the profitability that underpins those recurring cash flows investors care about.
That hinges on how far that cost squeeze runs before pricing, mix and scale fully catch up, which is exactly what the full narrative for Ansell unpacks in detail.
Origin Energy (ASX:ORG)
Origin Energy ties directly into this cash flow focused theme through its integrated gas and LNG activities, while also running a large electricity and customer solutions platform that keeps its earnings base broader than a pure upstream producer.
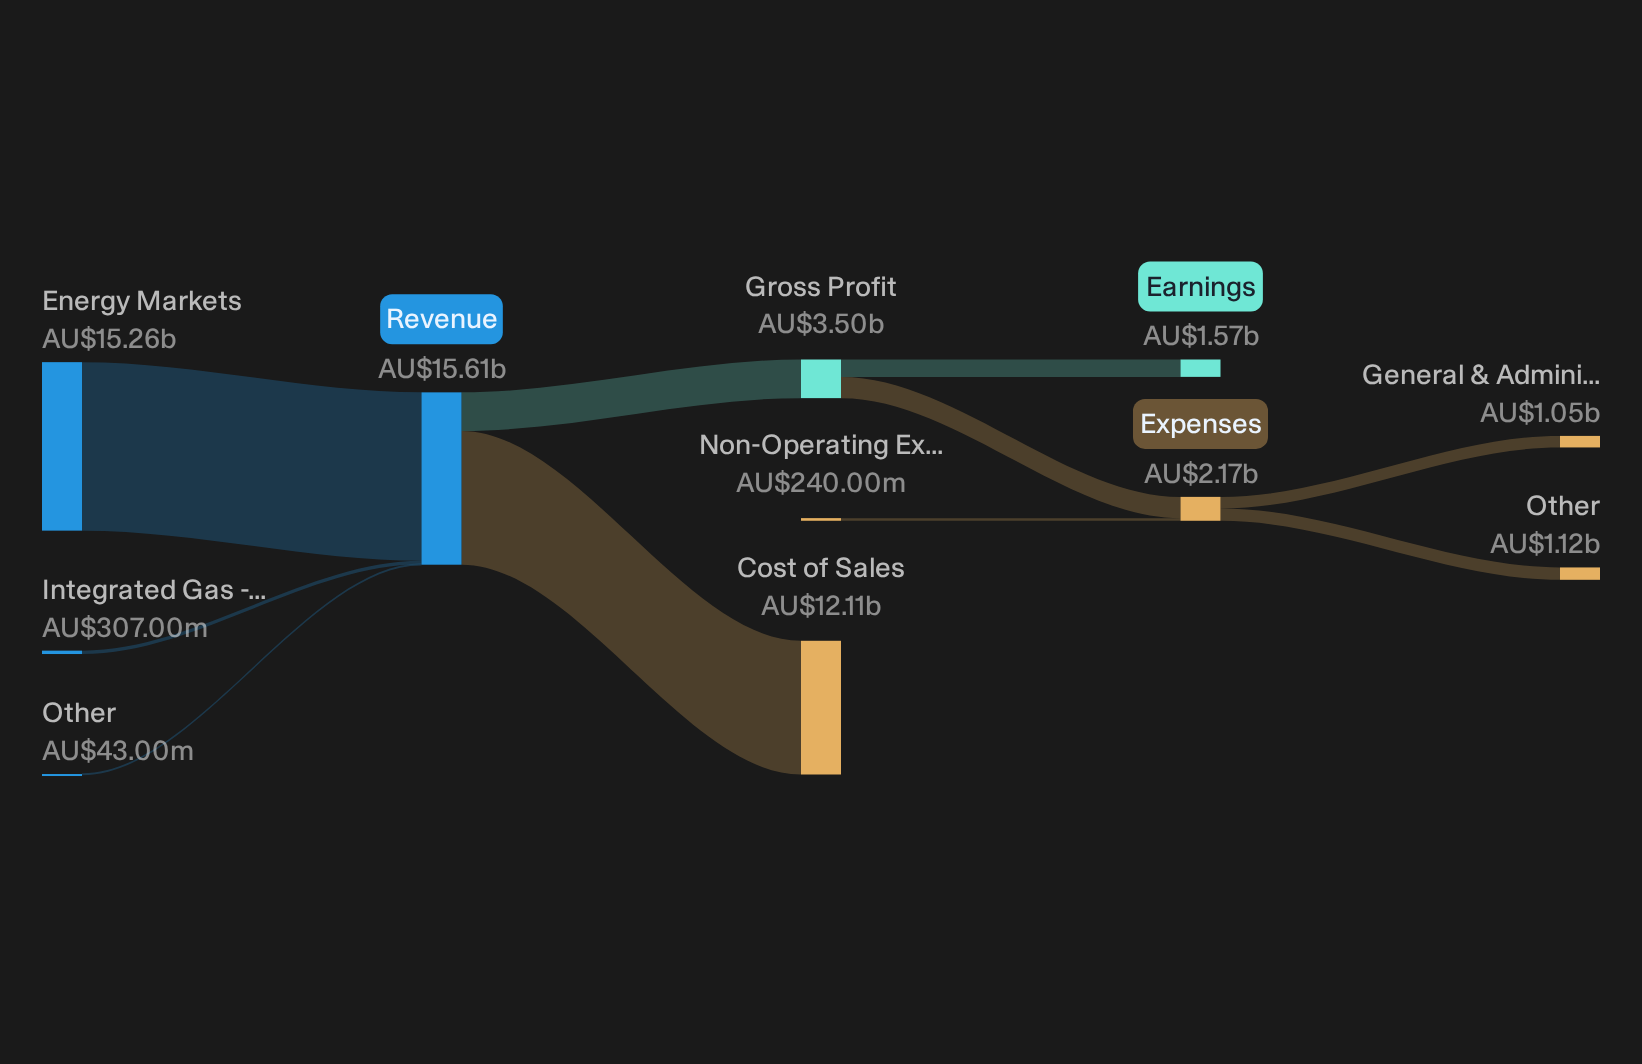
Origin Energy is an integrated utility that produces natural gas, generates electricity, and sells energy and related services across Australia. Most revenue comes from the Energy Markets segment at about A$15.3 billion and Integrated Gas at about A$307 million, with the group valued at around A$20.7 billion by market cap.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes. This affects wholesale and retail earnings visibility."
The major swing factor is how that shifting demand pattern interacts with gas linked cash inflows and one key pressure on long term margins.
That turning point on margins is exactly what the full narrative for Origin Energy unpacks for Origin Energy, including how cash flows could decouple from grid volume trends.
Life360 (ASX:360)
Life360 runs a mobile safety and location platform that turns family and pet tracking into a subscription business, so recurring Life360 Platform memberships are the clearest link to this cash-flow-focused screener, with Software and Programming revenue of about $573 million and a market value near A$5b.
For investors hunting recurring, cash-flow-driven stories, Life360 brings together a large user base, subscription-heavy revenue and a growing second leg from advertising. This sets up a useful test case for how this kind of model translates into long term cash generation.
"Although Life360 has resumed its intended MAU glide path with over 102 million monthly active users, the earlier technical issues on Android and lower end devices that forced management to trim full-year MAU expectations to 17 to 20% show how sensitive user growth is to product reliability, which could cap future subscription revenue and advertising reach if similar setbacks recur."
The real swing factor is how one cost-heavy growth push interacts with those subscriptions to shape the profitability underpinning any cash flow story investors rely on.
If that cost heavy push is what you are weighing up, the full narrative for Life360 shows how Life360 could convert scale into accelerating cash momentum.

Seeking Fresh Alternatives Before They Fly
Some of the most interesting ideas move from quiet to breakout before most investors even glance at them. Use this moment while it matters and consider getting in early.
- Scan for high quality companies that still look overlooked using the curated 15 high quality undiscovered gems. This can help you act before more money chases the same ideas and squeezes entry points.
- Track cash rich businesses where resilience and low risk scores meet real momentum through the focused 6 resilient stocks with low risk scores while they are still under the radar for now.
- Target consistent income from companies screened for robust payouts and balance sheets with the curated 4 dividend fortresses before yields start dropping as prices move.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com