


EN
Sphere Entertainment (SPHR) Could Be 29% Undervalued Following EPS Cuts
Sphere Entertainment (SPHR) heads into its Q3 2026 earnings release with sentiment under pressure after analysts cut consensus EPS forecasts, even as revenue projections point higher and expectations now center on a year-over-year profit decline.
Recent trading has been choppy for Sphere Entertainment, with the share price down 18.7% over the past month and 18.2% over 90 days, even as the year-to-date share price return sits at 21.7% and the 1-year total shareholder return is 68.6%. This points to longer term momentum that contrasts with the current pullback.
Scan how analysts are treating Sphere Entertainment, and then broaden your watchlist with a curated set of stocks screened for 29 high quality undervalued stocks that also balance quality and valuation pressure.
The stock’s slide into earnings can read as a verdict on Sphere Entertainment’s fundamentals or as a sharp swing in sentiment after a strong run. Which story does the current valuation actually tell?
Most Popular Narrative: 29% Undervalued
Against a last close of $114.73, the most followed narrative pegs Sphere Entertainment’s fair value at $160.54, which implies a clear valuation gap built on long run cash flow assumptions.
The expansion into new markets, particularly the development of both full-size and smaller franchise-model Spheres internationally (such as in Abu Dhabi and potential other cities), directly positions Sphere Entertainment to benefit from the increasing demand for experiential destination entertainment. This supports long-term revenue growth and margin scalability through asset-light models. Increasing consumer appetite for immersive, tech-driven live experiences supported by rapid advancements in AI and next-gen display technologies underpins Sphere's unique content offerings (e.g., Wizard of Oz at Sphere). This enables the company to achieve premium ticket pricing and improved per-event margins as expectations for high-quality, multi-sensory events rise.
See why 8 investors see Sphere Entertainment as 29% undervalued.
Result: Fair Value of $160.54 (UNDERVALUED)
Still, softer Wizard of Oz sell through and higher capital needs for new Spheres could pressure Sphere Entertainment if demand or partner support disappoints.
Find out about the key risks to this Sphere Entertainment narrative.
Another View: Sphere Entertainment on Sales-Based Valuation
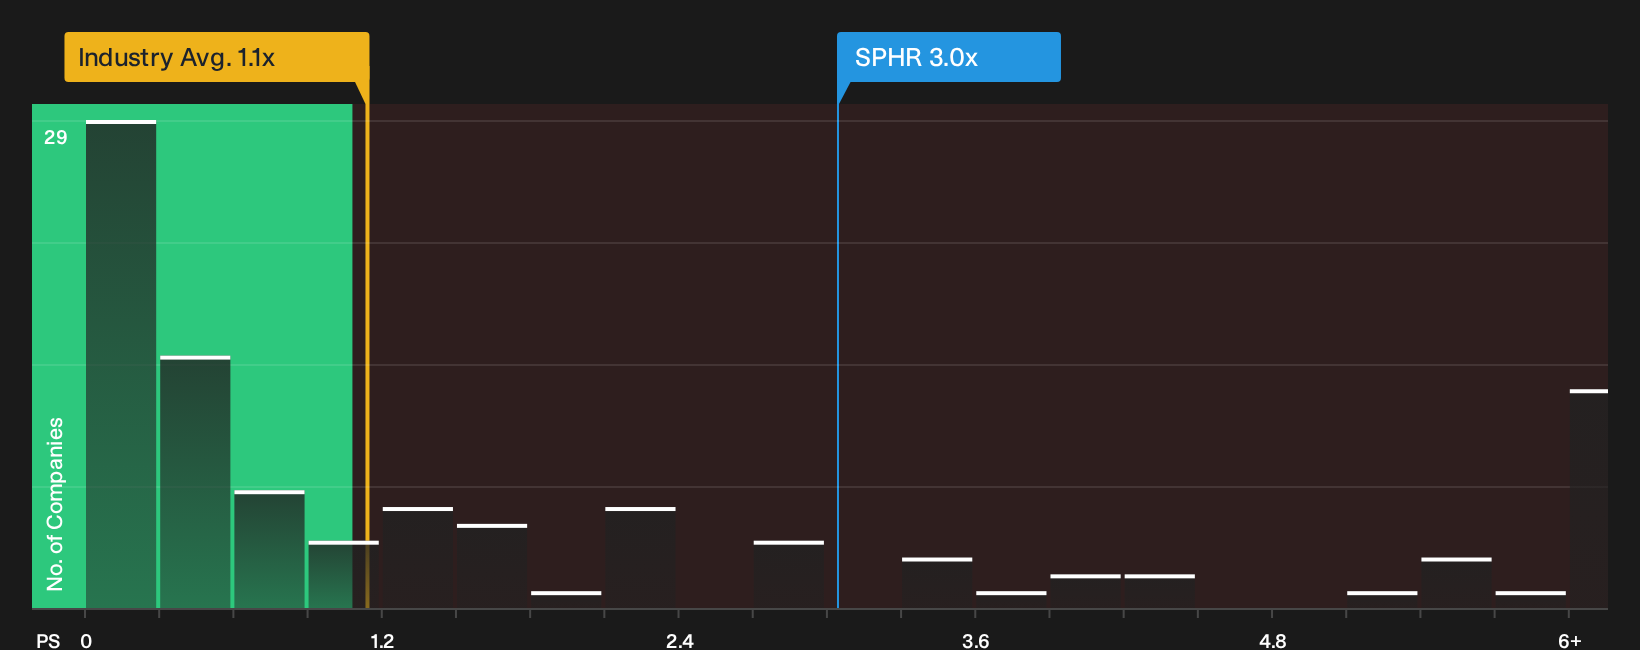
On the flip side of that undervalued fair value narrative, Sphere Entertainment screens as expensive on raw sales. The current P/S sits around 3x, while the US Entertainment industry averages about 1.1x and the estimated fair ratio for SPHR is also 1.1x.
That gap implies the market already pays a rich price for each dollar of revenue, which can leave less room for error if growth or margins underwhelm. The question for you is whether Sphere Entertainment’s model justifies that premium or if the share price needs to meet the fair ratio instead.
To see how this sales based view fits into a broader check on pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Sphere Entertainment so far, or firmly in one camp? Either way, act while expectations are moving and weigh up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sphere Entertainment?
Do not stop at Sphere Entertainment when a wider opportunity set is just a few clicks away. The right watchlist today can shape tomorrow’s decisions.
- Hunt for mispriced quality by scanning a focused set of companies flagged as potential value opportunities through the 29 high quality undervalued stocks.
- Strengthen your downside protection by zeroing in on businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Spot potential future standouts early by filtering for stronger fundamentals through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com