


EN
3 Global Stocks Estimated To Be Up To 43.4% Below Intrinsic Value
In recent weeks, global markets have experienced fluctuations driven by concerns over AI investment and rising oil prices, with small-cap and value-oriented stocks showing resilience amid a shift in market leadership. As investors navigate this volatile landscape, identifying undervalued stocks becomes crucial; these are companies whose current market price is believed to be lower than their intrinsic value, presenting potential opportunities for growth despite prevailing uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €26.86 | €53.92 | 50.2% |
| Thai Credit Bank (SET:CREDIT) | THB23.00 | THB45.73 | 49.7% |
| Smartsens Technology (Shanghai) (SHSE:688213) | CN¥104.80 | CN¥55.72 | -88.1% |
| P&H Tech (KOSDAQ:A239890) | ₩3120.00 | ₩6198.97 | 49.7% |
| PAL GROUP Holdings (TSE:2726) | ¥1472.00 | ¥2903.60 | 49.3% |
| Nissei ASB Machine (TSE:6284) | ¥8120.00 | ¥15723.78 | 48.4% |
| Natural Food International Holding (SEHK:1837) | HK$1.36 | HK$2.80 | 51.4% |
| Kissei Pharmaceutical (TSE:4547) | ¥3790.00 | ¥7679.17 | 50.6% |
| Henan Mingtai Al.IndustrialLtd (SHSE:601677) | CN¥14.50 | CN¥28.04 | 48.3% |
| ENN Energy Holdings (SEHK:2688) | HK$49.34 | HK$97.34 | 49.3% |
Let's take a closer look at a couple of our picks from the screened companies.
Fertiglobe (ADX:FERTIGLB)
Overview: Fertiglobe plc, along with its subsidiaries, is involved in the production and sale of nitrogen-based products across Europe, North and South America, Africa, the Middle East, Asia, and Oceania with a market cap of AED18.57 billion.
Operations: The company's revenue is derived from Third Party Trading, which accounts for $733.70 million, and the Production and Marketing of Owned Produced Volumes, contributing $2.83 billion.
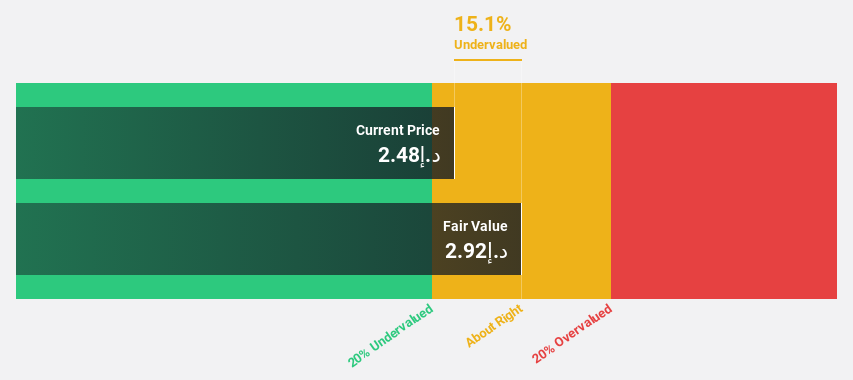
Estimated Discount To Fair Value: 36.9%
Fertiglobe is trading at AED2.27, significantly below its estimated future cash flow value of AED3.6, indicating it may be undervalued. Despite a recent 435.2% earnings growth, revenue and earnings are forecast to decline over the next three years by 7.7% and 16.5% annually, respectively. The company has a high projected return on equity of 20.8%, but its dividend track record is unstable, warranting caution for income-focused investors amidst strategic expansions in Europe’s ammonia market.
- Upon reviewing our latest growth report, Fertiglobe's projected financial performance appears quite optimistic.
- Click here and access our complete balance sheet health report to understand the dynamics of Fertiglobe.
Neway Valve (Suzhou) (SHSE:603699)
Overview: Neway Valve (Suzhou) Co., Ltd. is engaged in the research, development, production, and sale of industrial valves both domestically in China and internationally, with a market cap of CN¥27.07 billion.
Operations: The company's revenue from the valve industry segment amounts to CN¥8.26 billion.
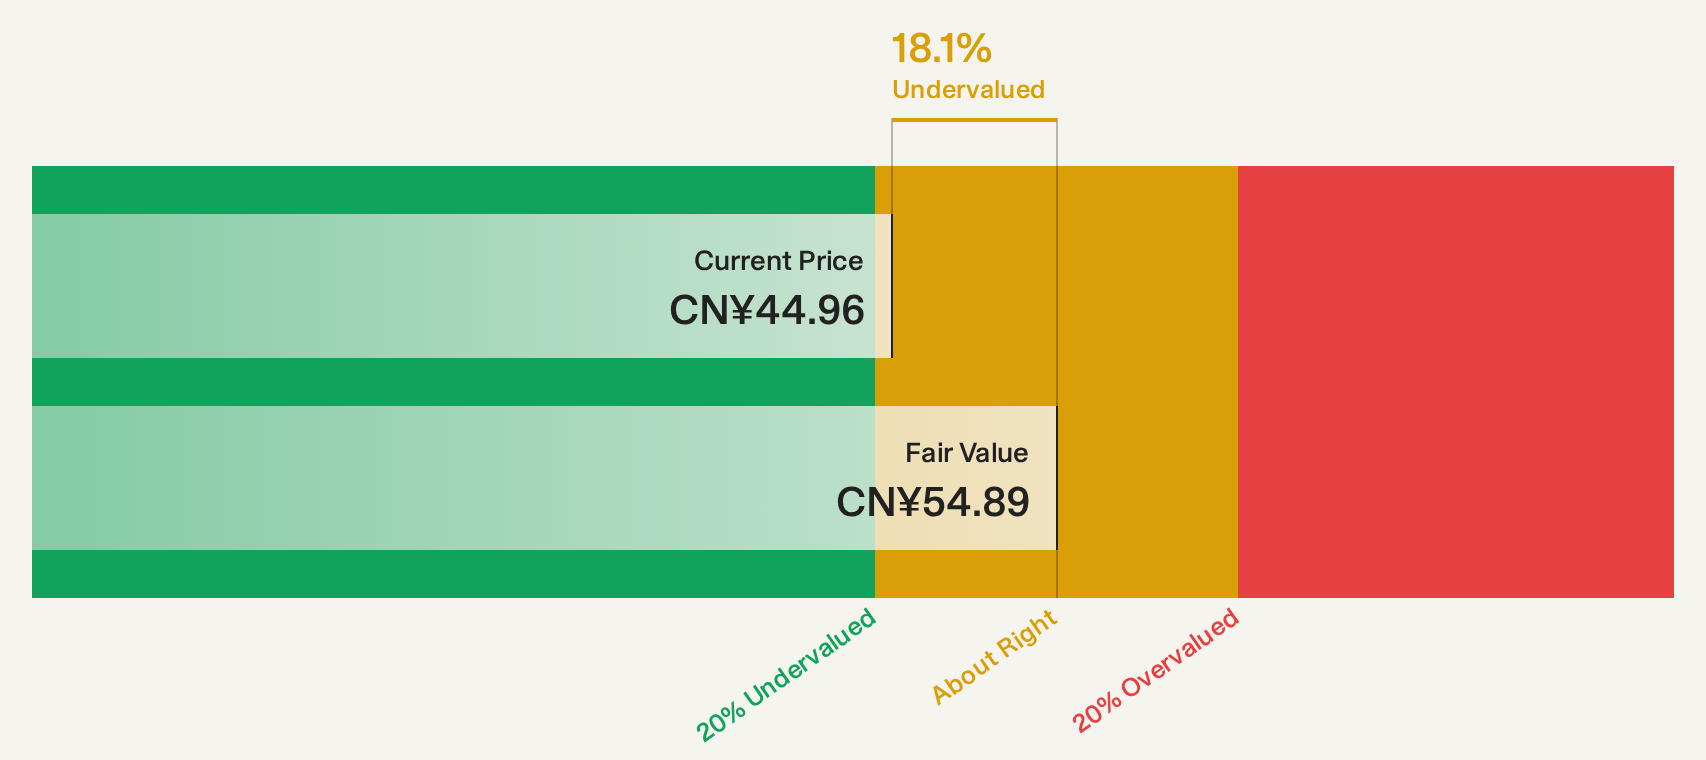
Estimated Discount To Fair Value: 31.2%
Neway Valve (Suzhou) is trading at CN¥38.02, well below its estimated future cash flow value of CN¥55.27, suggesting it is undervalued. Recent earnings grew by 30.2%, with revenue increasing to CNY 3,896.92 million from CNY 3,404.29 million a year ago. However, forecasted earnings and revenue growth are expected to lag behind the Chinese market averages at 19.2% and 15.1% per year respectively, despite strong analyst price target projections.
- Our growth report here indicates Neway Valve (Suzhou) may be poised for an improving outlook.
- Click here to discover the nuances of Neway Valve (Suzhou) with our detailed financial health report.
MINEBEA MITSUMI (TSE:6479)
Overview: MINEBEA MITSUMI Inc. is a company that manufactures and supplies machinery components, electronic devices and components, as well as automotive and industrial machinery, along with home security solutions both in Japan and internationally, with a market cap of approximately ¥1.29 trillion.
Operations: The company's revenue segments include Access Solutions with ¥338.29 billion, Precision Technologies at ¥305.12 billion, Motor, Lighting & Sensing generating ¥491.17 billion, and Semiconductors & Electronics contributing ¥613.46 billion.
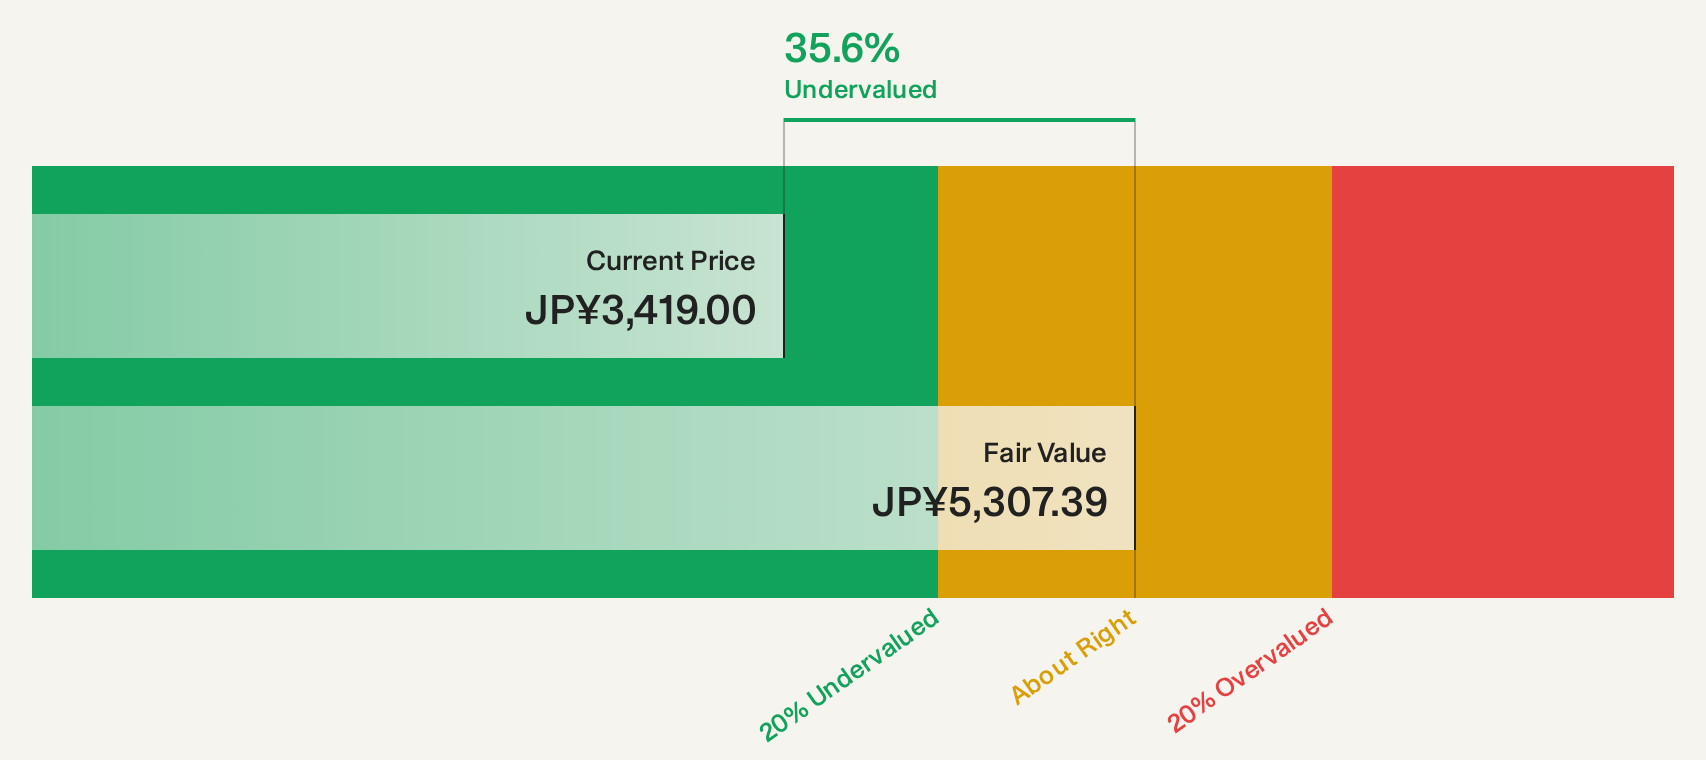
Estimated Discount To Fair Value: 43.4%
MINEBEA MITSUMI is trading at ¥3,310, significantly below its estimated future cash flow value of ¥5,847.46. Recent earnings showed robust growth with net income doubling to ¥21.30 billion from the previous year. Despite this, forecasted annual earnings and revenue growth rates of 4.3% and 3.1%, respectively, are projected to underperform compared to the Japanese market averages. Analyst consensus indicates a potential stock price increase of 46.3%.
- In light of our recent growth report, it seems possible that MINEBEA MITSUMI's financial performance will exceed current levels.
- Dive into the specifics of MINEBEA MITSUMI here with our thorough financial health report.
Next Steps
- Take a closer look at our Undervalued Global Stocks Based On Cash Flows list of 263 companies by clicking here.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com