


EN
How Investors May Respond To Tasmea (ASX:TEA) Board Election Challenge
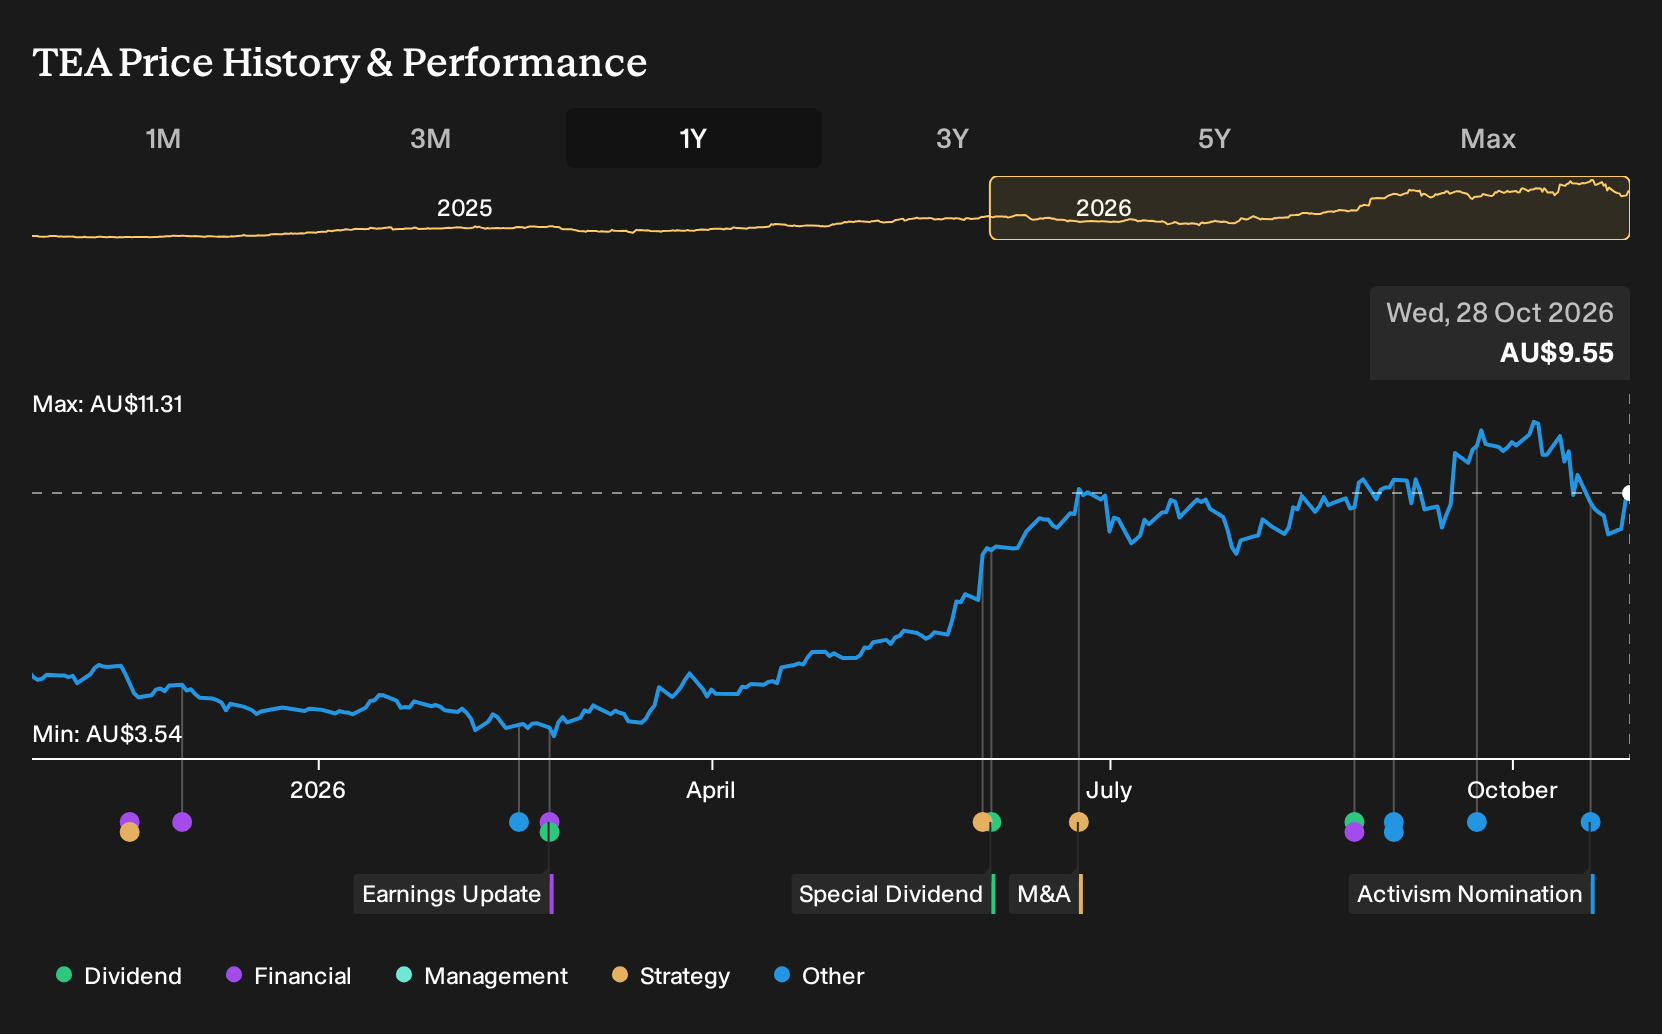
- On 20 October 2026, Tasmea investor Stephen Mayne confirmed he had nominated himself for election to the board, a move the company has asked shareholders to vote against at the 18 November annual meeting.
- The self nomination highlights a dispute over governance and board composition at Tasmea, which could influence how the business balances capital allocation, risk controls and long term project commitments across resources, energy and infrastructure clients.
- This report examines how Tasmea’s investment narrative intersects with this contested director nomination and what that might mean for governance.
Compare Tasmea's governance story with other industrial players by scanning our hand picked list of solid balance sheet and fundamentals (12 results) that may better align board oversight with financial resilience.
Tasmea Investment Narrative Recap
Tasmea asks you to believe in a services group that can keep turning specialist work in resources, energy and infrastructure into consistent earnings, helped by recurring maintenance contracts and a long project pipeline. The near term swing factor still sits in execution on data center, LNG and mining related work rather than this board dispute.
The key operational risk right now is that thinner net margins at 5.5%, compared with 9.7% last year, meet any slowdown or delays in award timing. The Mayne nomination speaks to board oversight and independence, but on its own it does not materially change near term contract conversion, workforce utilisation or cash generation.
The most relevant development is the 20 October 2026 announcement that investor Stephen Mayne has nominated himself for election to the Tasmea board, with the company recommending a vote against. For you, this relates to how governance supports or constrains capital allocation, acquisitions and risk controls over large, long dated projects.
You already know Tasmea leans on acquisitions, low leverage and a large specialist workforce across segments such as Electrical and Workforce Solutions. This director nomination lands against that backdrop and may focus attention on issues including board independence, dividend cover from free cash flow and how aggressively management pursues further programmatic deals.
What Tasmea's Forecasts Assume
Tasmea's current analyst storyline centres on strong expansion in both sales and profitability over the next few years, with the contested board seat running alongside rather than replacing that set of expectations. Forecasts point to revenue growing at 30.3% a year over the next 3 years, on the assumption that the project funnel in resources, energy and data centers keeps converting and that margins edge higher from 5.5% today to 5.8% by 2029. Earnings today sit at A$71.3 million, while the consensus view has profit reaching A$165.6 million by about 2029, which implies an increase of roughly A$94 million in annual earnings.
Tasmea's narrative projects A$2.9b revenue and A$165.6 million earnings by 2029. This requires 30.3% yearly revenue growth and an earnings increase of about A$94 million from A$71.3 million today.
Uncover how Tasmea's fair value indicates a 13% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly A$10.83 to about A$17.36, so some Tasmea followers see the stock as heavily undervalued while others are far more cautious. These views do not factor in the Stephen Mayne nomination, which could reshape perceptions of governance risk and future project execution. Readers can weigh these competing narratives and explore further community perspectives before deciding how the activism backdrop fits with their own expectations.
Explore 3 other Tasmea fair value estimates, including one that suggests up to 82% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tasmea research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tasmea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tasmea's overall financial health at a glance.
Looking for more Tasmea sized investment ideas?
Once you have formed a view on Tasmea, it can help to cross check that thesis against other opportunities that match your risk tolerance, return goals and time horizon. The Simply Wall St Screener lets you filter for different types of businesses so you can build a watchlist that fits how you like to invest.
- If you want potential mispricing backed by balance sheet strength, scan our 2 high quality undervalued stocks and see which candidates merit a closer look.
- For investors who care more about income durability than short term price moves, focus on our 4 dividend fortresses to spot yield opportunities with supporting fundamentals.
- If resilience matters most to you, start with the 6 resilient stocks with low risk scores and compare those profiles with Tasmea's risk and reward mix.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com