


EN
BCE (TSX:BCE) Stock Looks Cheap Even After The Tower Deal
BCE Inc. is trading around $28.23 after several years of weak share price performance. This puts a spotlight on a simple question for investors: Is today’s valuation properly explained by the earnings power the telecom group is generating and expected to generate from here?
- The share price has declined about 38.1% over 5 years, which puts past holders under pressure and makes the link between BCE’s current earnings and today’s price especially important.
- The planned sale of a 49.9% stake in Bell’s new TowerCo for about $2.45b can reshape how investors think about BCE’s future earnings mix, capital needs and the timing of cash flows tied to its wireless infrastructure.
- Your read on BCE is one view; the desks covering it have another. See what analysts think BCE's shares could be worth.
The issue now is whether BCE’s current share price is justified by what the business earns today and what those earnings reasonably point to over time.
To see how this earnings question plays out across other telecom and AI infrastructure plays, compare BCE with a wider group of 55 AI infrastructure stocks
Is BCE Still Cheap on Earnings?
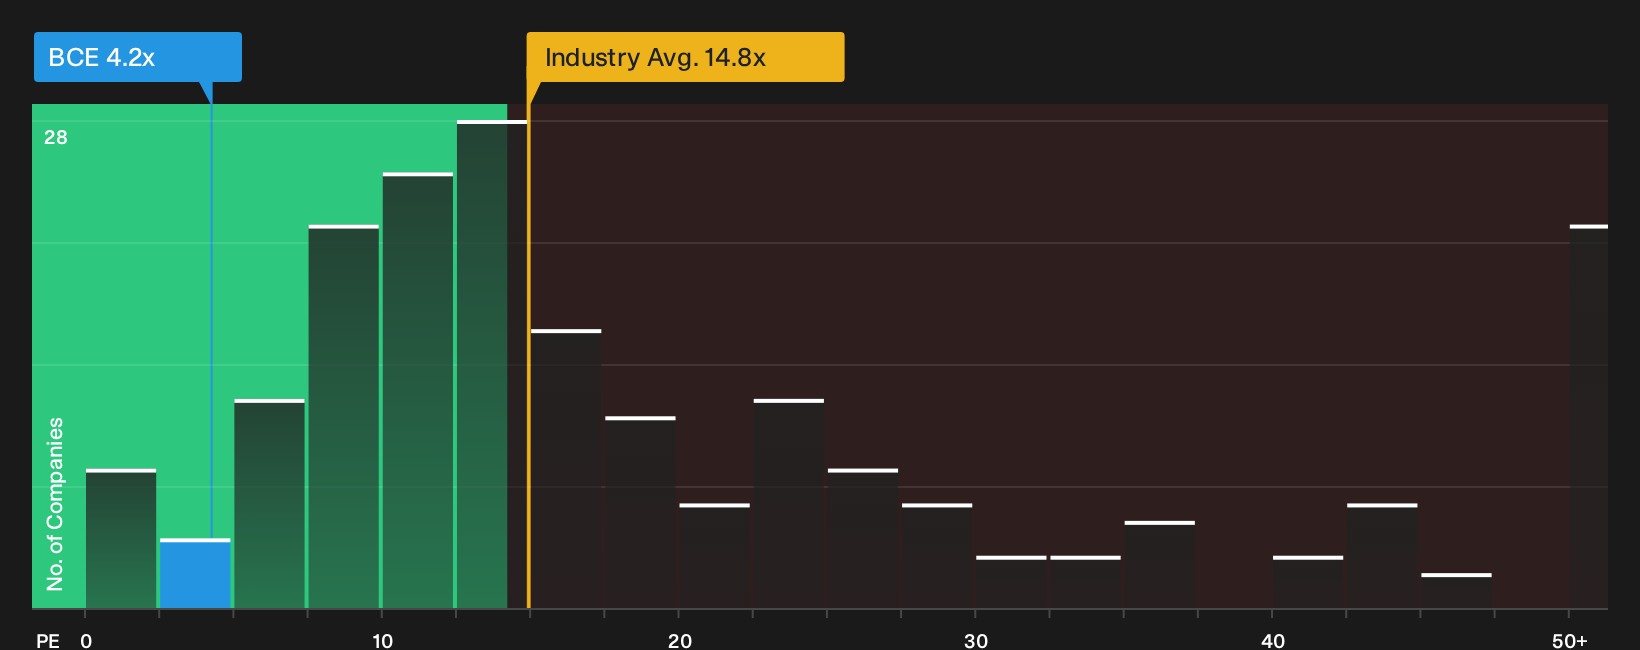
P/E fits BCE because earnings remain a key anchor for how investors look at large telecom groups with heavy infrastructure spending. On that yardstick, BCE trades on a P/E of about 4.2x, compared with roughly 14.8x for the broader Telecom industry and around 21.7x for its peer set. That gap is wide, so the market is attaching a much lower price tag to each dollar of BCE’s reported profit than to many comparable operators.
The Fair Ratio framework, which adjusts the benchmark multiple for factors such as margins, expected cash generation, scale and risk, points to a higher P/E than where BCE trades today. This screens the stock as undervalued on this metric. Because the new CA$2.45b TowerCo deal helps clarify the stream of future tower lease income, the low P/E suggests investors are still pricing BCE at a discount even as that tower cash flow becomes more visible. Explore the numbers behind BCE's P/E valuation.
The BCE Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this BCE valuation puzzle leaves off and spell out which assumptions about BCE's future earnings power, margins and cash generation would need to hold for the stock to be worth meaningfully more or less than today’s price.
Each scenario sets out its own fair value logic in terms of those inputs rather than relying on a single multiple, so you can track how the underlying assumptions stack up against BCE's reported results as they come through on the Community page.
One of the top community narratives on BCE: 12% undervalued
"The main thing that has to go right is that BCE successfully scales its AI-powered infrastructure and enterprise services while maintaining fiber-led internet and digital media momentum..."
Discover why this Narrative puts BCE at 12% undervalued.
One more BCE check that belongs beside the valuation work
Price and earnings only tell you so much. The people steering BCE, how their rewards line up with your interests and what that says about future decisions is the next piece to examine. See who runs BCE and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com