


EN
Learn Why The Bull Case For Magnite Stock Could Change Following LG Deal Extension
- LG Ad Solutions and Magnite extended their partnership for three years, keeping SpringServe as LG’s exclusive CTV video ad server and making LG Home Screen inventory available for agentic buying through Magnite’s Seller Agent across North America, APAC, and EMEA.
- The collaboration deepens the link between Magnite’s SpringServe and ClearLine platforms, with LG Ad Solutions also using Magnite’s GenAI creative agent to build CTV ad units and streamline campaign execution for advertisers.
- We will examine how Magnite’s extended LG Ad Solutions partnership and new agentic buying access may influence the broader investment narrative.
Compare Magnite's CTV ad-tech positioning with a curated group of peers by scanning the 39 profitable AI stocks that aren't just burning cash that are already turning AI driven products into real earnings power.
Magnite Investment Narrative Recap
To own Magnite, you need to believe its independent CTV ad platform keeps earning a meaningful role with big streamers, OEMs and agencies, even as those partners test more in-house or vertically integrated tools. The LG extension fits that view but does not fundamentally change the near term story around contribution ex TAC, EBITDA margins or free cash flow.
The more immediate operational swing factor still looks like how quickly deeper programmatic CTV adoption and AI driven tools offset pressure in weaker areas such as web display inside DV+. The key risk stays the same. Any loss of a large CTV or agency relationship could hit both CTV and DV+ contribution faster than new deals ramp.
The LG Ad Solutions agreement lines up closely with one of the bigger existing catalysts for Magnite. Management has been tying the thesis to OEM and home screen wins with Samsung, LG and HP TV+, plus AI and agent based products that already handle millions of dollars of spend with major advertisers and agencies.
What feels most relevant here is the operational link between SpringServe, ClearLine and Magnite’s buyer and seller agents. LG exposing home screen inventory through Seller Agent, and using Magnite’s GenAI creative tools, feeds directly into that supply side data and workflow story. It reinforces the idea that if OEM and commerce media partners keep adopting these tools, Magnite’s mix and margins could benefit.
Magnite's analyst narrative points to revenues of US$926.0 million and earnings of US$136.5 million by 2029, based on an assumed 7.7% yearly revenue growth rate and an earnings decline of US$30.4 million from US$166.9 million today.
Uncover how Magnite's fair value indicates a 36% potential upside to its current price before the market closes the gap.
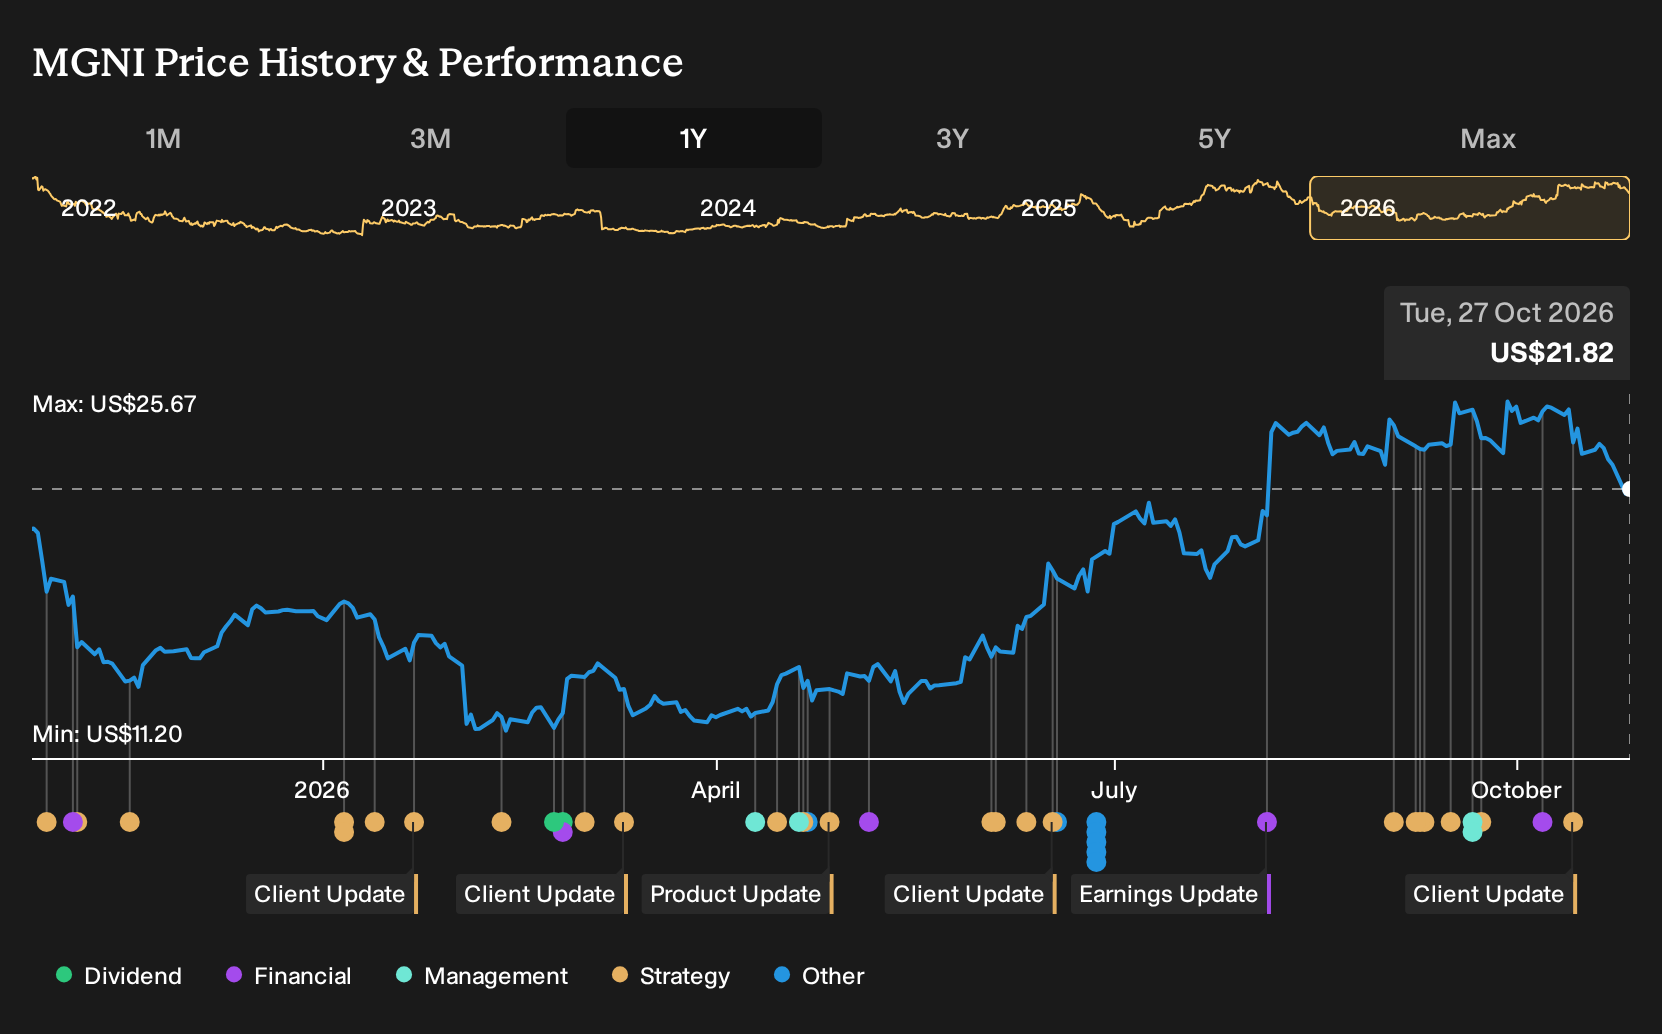
Exploring Other Perspectives
Some bullish analysts frame Magnite’s AI and agentic tools as the real swing factor, not just CTV share. Before this LG news, the most optimistic forecasts were for revenue to reach about US$1.0b and earnings of US$172.9 million by 2029. That is far above the US$926.0 million and US$136.5 million consensus view, and these projections may shift as investors digest the new LG agreement.
Explore 3 other Magnite fair value estimates, including one that suggests as much as 36% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Magnite research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Magnite. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magnite's overall financial health at a glance.
Looking for more Magnite-like investment ideas?
If the Magnite story has sharpened your thinking, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who put balance sheet strength first, start with a list of solid balance sheet and fundamentals (24 results) that already filters for companies with financial resilience.
- If your priority is cushioning volatility while still staying invested in equities, consider a 30 resilient stocks with low risk scores that screens for businesses with more measured risk profiles.
- When you want to spot potential early stage opportunities with room to grow, work through a 7 elite penny stocks with strong financials that focuses on smaller companies with market caps at the lower end of the spectrum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com