


EN
How Q3 Production Results At Anglo American (LSE:AAL) Have Changed Its Investment Story
- Anglo American reported third quarter 2026 production with mixed volumes across copper, iron ore, manganese, diamonds, steelmaking coal and nickel, and issued 2026 output guidance that outlines expected ranges for key commodities.
- The updated guidance on copper, premium iron ore and diamonds gives investors a clearer view of how Anglo American is planning around demand patterns, capital deployment and portfolio priorities across its core resources.
- We will now look at how Anglo American’s new 2026 copper guidance could shape the broader investment narrative around its portfolio shift.
Scan how Anglo American’s copper-heavy pivot compares across the sector by checking a curated set of 16 top copper producer stocks that could also be repositioning production and portfolios.
Anglo American Investment Narrative Recap
To own Anglo American, you need to buy into a mining group that is reshaping itself around copper and premium iron ore while working through a period of uneven production and current losses. The latest quarter showed mixed volumes across key commodities, so the near term focus stays on execution at existing copper assets and keeping unit costs under control.
The main short term catalyst is delivery against the 2026 production guidance, especially the 700 kt to 760 kt copper range. Any repeat of operational issues or logistics constraints would quickly pressure that narrative. The largest risk remains delays or value leakage around planned divestments, including De Beers. These could keep leverage and cash flow under strain.
The most relevant update alongside the copper pivot is the production guidance for 2026. Anglo American is flagging 700 kt to 760 kt of copper, 55 Mt to 59 Mt of premium iron ore and 25 Mct to 28 Mct of diamonds. Those ranges give you a working yardstick to judge whether the portfolio reshaping is coming through in actual tonnes.
For catalysts, that guidance sits next to the ongoing De Beers sale discussions, which could reshape Anglo American’s exposure to a weaker diamond market and free up capital for copper and iron ore. Execution risk cuts both ways here. A clean exit on acceptable terms would simplify the business, while delays or tough regulatory conditions in African jurisdictions could keep group returns under pressure.
What The Anglo American Forecasts Are Asking You To Assume
Analyst models around Anglo American are built on a fairly specific earnings reset. The consensus view has revenue growing by 3.8% a year over the next three years while profit margins move from a 7.0% loss position today to 13.2% by 2029.
On that framework, earnings are projected to swing from a loss of US$1.4b today to profits of US$2.9b by 2029. That is a value change of US$4.3b in earnings, with forecasts clustered between US$2.5b on the cautious side and US$4.8b at the top end.
Those profit expectations sit behind a 2029 P/E multiple of 27.5x on consensus, compared with a current P/E of 42.7x in loss territory and an industry average of 11.9x for GB metals and mining stocks. For you as an investor, that gap highlights how much of the Anglo American thesis depends on the copper and premium iron ore pivot translating into a cleaner, higher margin earnings stream.
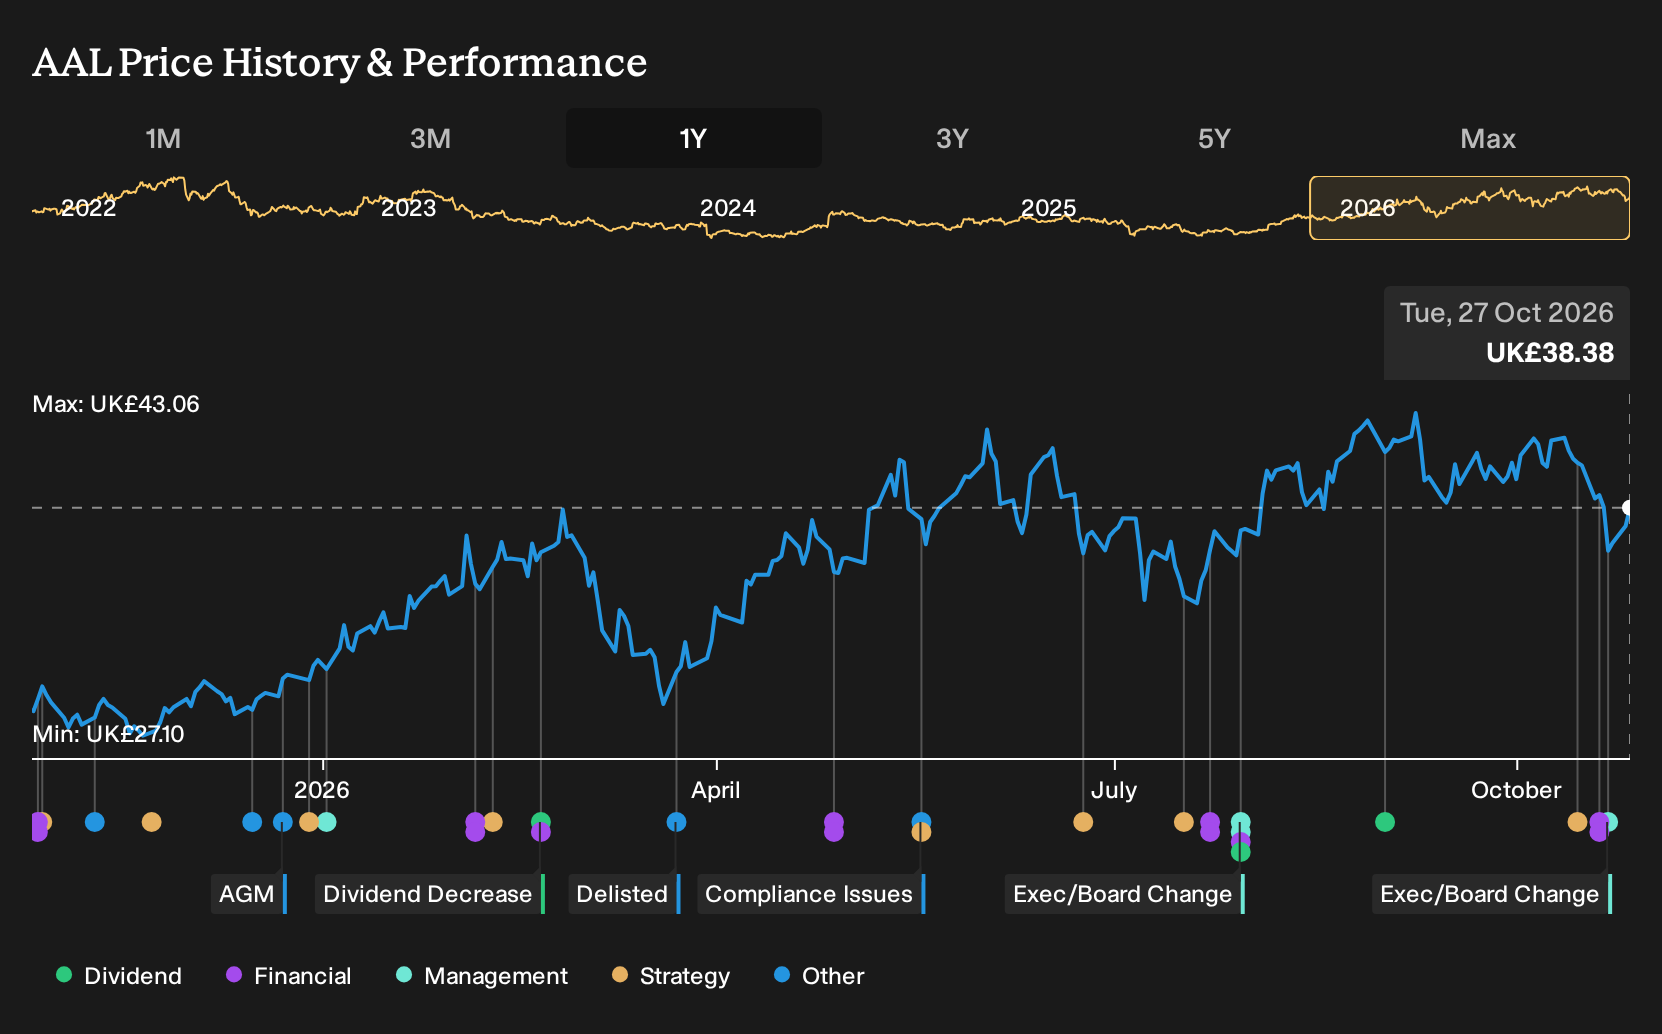
On the pricing side, the group trades at about £41.20 with analysts collectively pointing to a £41.77 target. That 1.4% difference suggests the stock is viewed as roughly in line with fair value on current information. The more important consideration is whether Anglo American can reach the 2029 revenue and profit milestones that underpin those models.
Anglo American's current analyst narrative points to US$21.8b in revenue and US$2.9b in earnings by 2029. That profile assumes yearly top line expansion of 3.8% and an earnings move of US$4.3b from a loss of US$1.4b today.
Uncover why Anglo American's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle focuses on geopolitical and ESG risk rather than copper growth. The most cautious analysts, who were pencilling in about US$20.6b of revenue and US$2.6b of earnings by 2029 before this Anglo American update, see tighter regulations and host country politics as the real swing factor. Board changes such as Anne Wade’s new role and the latest production data could shift those expectations. Treat this as a reminder that opinions differ widely and are likely to move as fresh information lands.
Explore 3 other Anglo American fair value estimates, including one that suggests as much as 29% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Anglo American research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Anglo American. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Anglo American's overall financial health at a glance.
Looking for more investment ideas beyond Anglo American?
If Anglo American has sharpened your focus on where capital might work harder, it can help to scan a broader watchlist and see how other businesses stack up on quality, value and resilience using the Simply Wall St Screener.
- If you want potential upside with a margin of safety, start with a curated pool of 10 high quality undervalued stocks that combine quality fundamentals with more modest pricing.
- If capital preservation sits high on your checklist, narrow your search to a 4 resilient stocks with low risk scores and compare how different companies score on balance sheet strength and volatility.
- If you prefer companies with room to grow that are not crowded trades yet, scan a 5 high quality undiscovered gems to spot lesser known tickers with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com