


EN
How Investors Are Reacting To Elmos Semiconductor (XTRA:ELG) LED Controller Design Wins
- Elmos Semiconductor reported its first design wins with a German premium OEM for the E522.96 LED controller, which supports pixel based OLED rear lights with several hundred individually controllable pixels and up to 48 channels.
- The new controller points to broader use of complex lighting electronics in vehicles, which could increase semiconductor content per car and deepen Elmos Semiconductor’s role in exterior lighting architectures.
- We will now see how Elmos Semiconductor’s investment narrative could be influenced by the new E522.96 pixel based OLED design wins.
Elmos Semiconductor Investment Narrative Recap
For a shareholder in Elmos Semiconductor, the core belief is that demand for intelligent automotive electronics, from lighting to sensing to power management, keeps translating into design wins that move into volume production. The recent E522.96 OLED controller win fits that story, but by itself does not reshape the near term outlook. The more immediate swing factor still looks like how quickly awarded projects ramp into series supply.
The biggest operational risk remains capacity access and cost on 8 inch nodes as AI related power chips compete for similar production slots. Any squeeze here could pressure gross margins or slow execution on booked projects. The new lighting win and broader sensor and motor control portfolio do not remove that risk, although longer term foundry agreements already in place give some supply underpinning.
The electronica 2026 showcase is arguably the most relevant recent announcement for this lighting news. It puts the E522.96 into a wider context, with Elmos Semiconductor presenting a line up that spans intelligent lighting, ultrasonic distance measurement, sensor ICs, motor control, and secure data communication. That breadth matters because large OEMs increasingly look for suppliers who can support whole subsystems rather than single chips.
On catalysts, the robotics angle introduced at electronica is especially interesting. Management sees more than 120 potential IC applications across motion, sensing, power, and connectivity in humanoid robots. If even a portion of those opportunities turns into concrete programs, it could diversify revenue that today leans heavily on automotive while still reusing existing technologies. Execution risk is real, since this is an adjacent market, but it ties directly into the same capacity, design win, and ramp up questions that already define the Elmos Semiconductor investment case.
What The Consensus Implies For Elmos Semiconductor
Elmos Semiconductor's narrative projects €889.1 million revenue and €179.8 million earnings by 2029. Meeting those analyst expectations would mean 12.5% yearly revenue growth and an earnings increase of about €77.5 million from €102.3 million today.
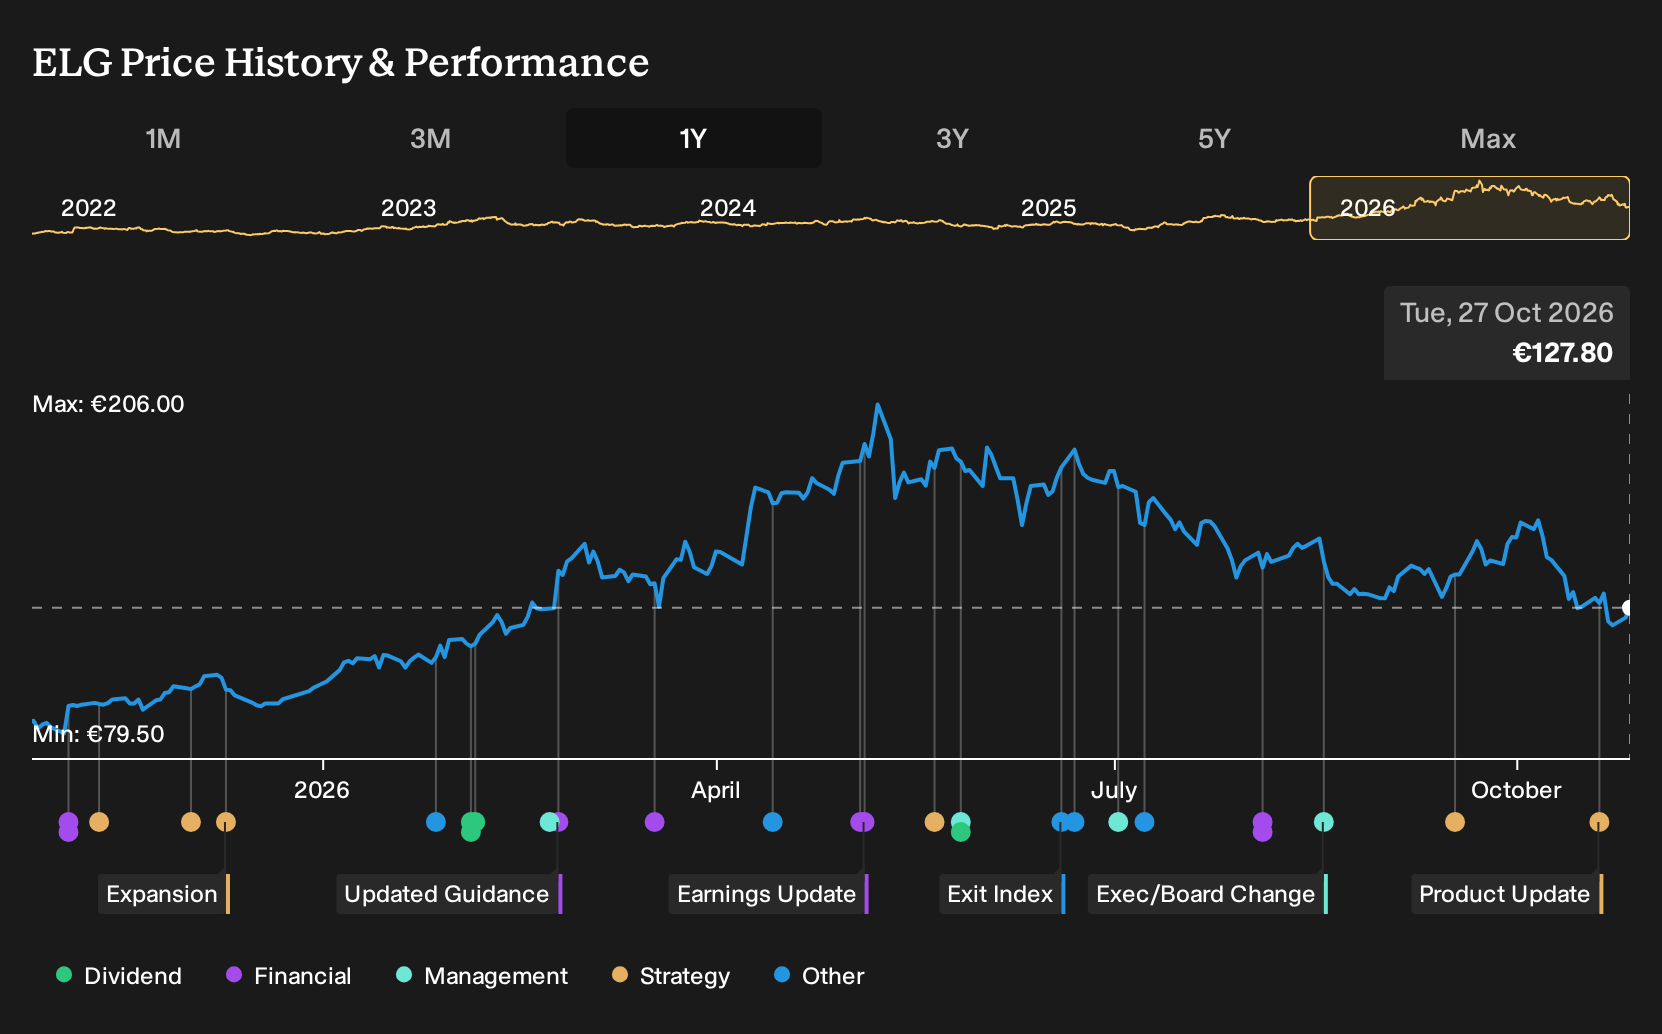
Uncover why Elmos Semiconductor's fair value indicates a 51% potential upside to its current price that investors may see materialize sooner than expected.
Exploring Other Perspectives
One bullish twist on the Elmos Semiconductor story focuses on humanoid robotics rather than cars. The most optimistic analysts were already pencilling in €925.9 million revenue and €199.2 million earnings by 2029 before this E522.96 lighting win and electronica showcase. You can treat those forecasts as one possible path and compare them with more cautious views.
Explore 4 other Elmos Semiconductor fair value estimates, including one that suggests there could be as much as 68% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Elmos Semiconductor research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Elmos Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elmos Semiconductor's overall financial health at a glance.
Looking for more investment ideas beyond Elmos Semiconductor?
If the Elmos Semiconductor story has sharpened your thinking, it can be useful to line it up against other listed businesses with different financial profiles. Use the Simply Wall St Screener to scan for stocks that fit the type of balance sheet strength, income profile, or valuation setup you want to research next.
- For investors who care most about financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (207 results) that can help you focus on companies with sturdier foundations.
- If income is your priority, you might prefer stocks offering stronger cash returns, so filter for 224 dividend fortresses that can help you stress test payout strength and consistency.
- Those hunting for potential mispricing can sort through 195 high quality undervalued stocks and look for situations where quality fundamentals and current prices appear out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com