


EN
AppFolio (APPF) Lifts Guidance On Results While Fair Value Still Sits Higher
AppFolio (APPF) moved back into focus after reporting third quarter and year to date results, with higher sales, earnings and updated full year revenue guidance giving investors fresh numbers to reassess the stock.
Despite the stronger quarterly figures, AppFolio’s recent trading tells a different short term story, with the share price down 6.01% on the day and 9.95% over the past week. This leaves the year to date share price return down 12.56%, while the 5 year total shareholder return of 52.30% points to far more constructive longer term momentum.
Scan how AppFolio compares with other software names showing strong execution and resilient fundamentals using the curated 21 high quality undiscovered gems.
Recent earnings strength and a softer share price now pull in opposite directions. For AppFolio, at around US$201, does that wobble open up an attractive entry, or signal a market re-rating that still has further to run?
Most Popular Narrative: 18% Undervalued
On the most followed view, AppFolio’s fair value sits at $245.91, comfortably above the last close of $201.45. This frames today’s pullback as a valuation gap rather than a finished story.
The numbers imply a share price that already reflects strong revenue, margin, and cash flow delivery, yet still prices AppFolio below what this narrative views as a fair outcome if AI-led automation, platform consolidation, and resident monetization continue to compound.
See why 21 investors see AppFolio as 18% undervalued.
Result: Fair Value of $245.91 (UNDERVALUED)
Still, the AppFolio narrative can wobble if higher cloud and payments costs keep pressure on margins, or if recent insider selling foreshadows softer growth expectations.
Find out about the key risks to this AppFolio narrative.
Another View: AppFolio on Earnings Multiples
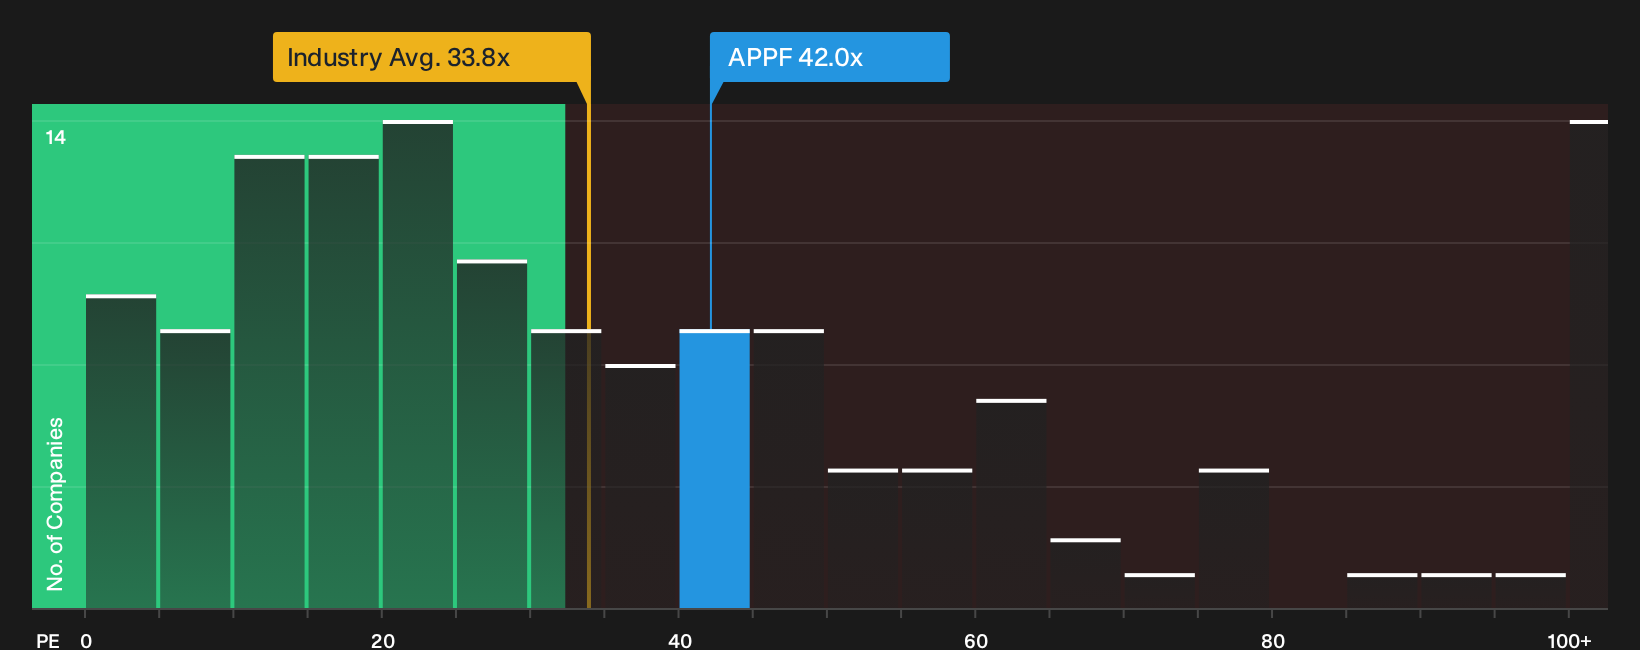
On the flip side of that fair value estimate, AppFolio appears more expensive when you focus on the current P/E. The stock trades around 42x earnings, compared with a 32.7x average for US software peers and a fair ratio of 31.7x.
That gap points to valuation risk if sentiment cools. For an investor, the question is whether the growth story and quality metrics justify paying meaningfully more than both the sector average and the fair ratio, or whether patience is the better response while expectations reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and earnings momentum can pull investors in opposite directions, so move quickly to study the numbers and weigh the 3 key rewards and 2 important warning signs.
Looking for more AppFolio-sized investment ideas?
If AppFolio has your attention, do not stop here. The market is full of other high quality opportunities that fit very different risk and income profiles.
- Target steadier potential compounding by scanning a curated 29 high quality undervalued stocks that combine quality fundamentals with room for re-rating.
- Build a more dependable income stream by reviewing a focused 5 dividend fortresses that offer higher yields backed by underlying business strength.
- Dial down portfolio stress by concentrating on a 30 resilient stocks with low risk scores built around resilient balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com