


EN
What Investors Got Wrong About Aspen Aerogels Before The Drop
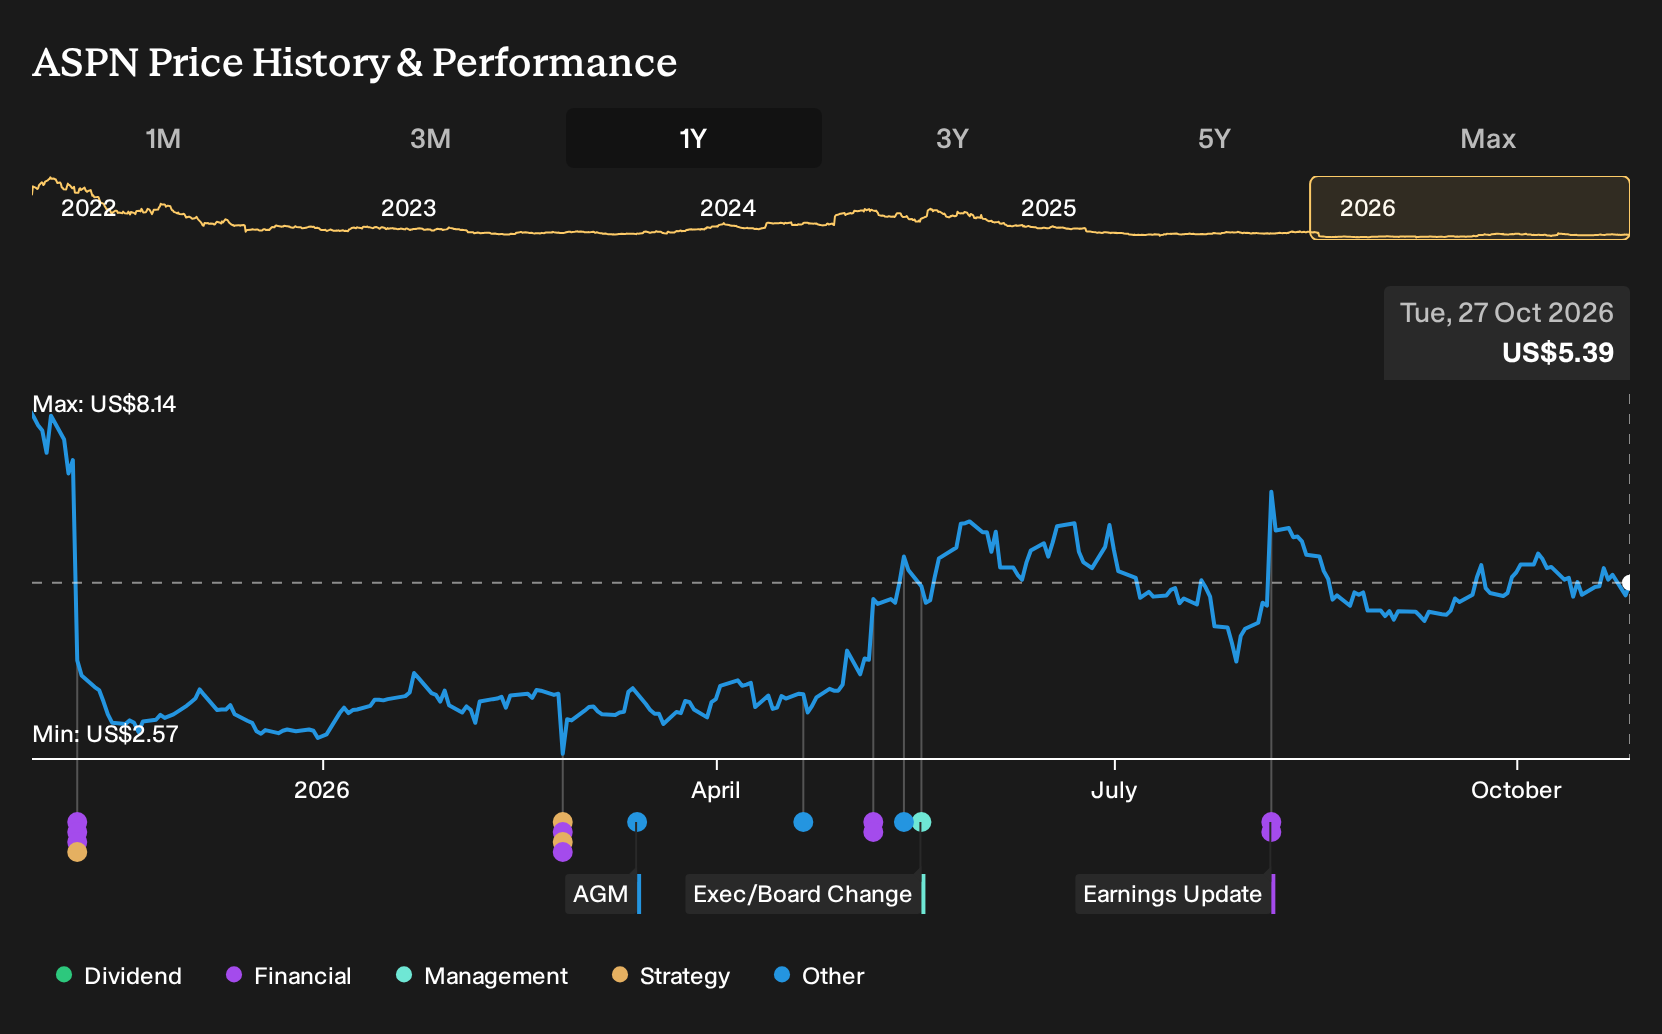
On 7 August 2026, Aspen Aerogels reported that Q2 revenue was US$49.849 million and that the loss excluding extra items deepened to US$23.264 million, with net margin falling to 46.7% in the red. Investors who held Aspen Aerogels over the past year are down 32.5%, including dividends. If you had bought at the start of this period, you may now be reassessing how to view a business that was expected to cut costs and benefit from growing EV demand, yet is currently reporting this profit picture.
Aspen Aerogels has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Argument Investors Had To Weigh On Aspen Aerogels
The shares cost US$8.13 at the start of the period, and you were really choosing between two stories about where Aspen Aerogels might head next.
On the optimistic side, the bullish view pointed to cost cuts and EV thermal barrier demand, with a Fair Value of US$9.58, the price implied if assumptions played out, built on revenue growth of 8.9% and profit margin rising to 12.3%.
The cautious narrative gave more weight to regulatory uncertainty and cash demands, with a Fair Value of US$7 built around flat to slightly declining revenue of 0.8% a year and pressure from rising compliance and input costs.
What The Results Changed For Aspen Aerogels
The clearest new fact was Aspen Aerogels reporting Q2 2026 revenue of US$49.849 million, down from US$78.024 million a year earlier. The quarterly loss excluding extra items widened to US$23.264 million, and net margin moved from 11.6% in the red to 46.7% in the red. That outcome challenged the optimistic case built on improving profitability and provided more support to the cautious scenario.
The episode turned on one simple assumption: that cost cuts and EV demand would quickly show up in reported earnings. When you look at another company, test that same claim against the trend in operating loss and net margin rather than relying on the story alone.
What You Are Paying For In Aspen Aerogels Today
With Aspen Aerogels at US$5.39 after a 32.5% loss over the past year, the selected Narrative’s Fair Value sits above the current price. That view leans on a wider Energy Industrial backlog, growing European EV thermal programs, and early battery storage work as potential supports for a broader revenue mix.
The same Narrative leans on guided progress toward positive adjusted EBITDA and a net cash position as cushions while these programs mature. A buyer today would need to believe those Energy Industrial projects and European thermal platforms scale as outlined and that battery energy storage becomes a meaningful third leg of the business.
"Key Takeaways: Bullish analysts expect Aspen Aerogels to convert its Energy Industrial backlog, growing European EV thermal programs, and emerging battery storage opportunity into a larger and more diversified revenue base that supports the view that the stock is undervalued. The main thing that has to go right is that Aspen Aerogels sustains Energy Industrial growth while European Thermal Barrier programs and battery energy storage systems scale as planned and offset a weaker U.S. EV backdrop and incident related cost pressures."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Another Piece In The EV Puzzle
Aspen Aerogels sits where heat meets safety. Your EV thesis might not stop there.
Every motor, inverter and wind turbine that Aspen-related customers use still needs rare earth magnets.
One specialist miner refines those materials and is building downstream plants that turn them into finished magnet products.
Government contracts support part of that effort, which can steady cash flow through raw material price swings.
If EVs, turbines and advanced electronics keep using these magnets, that builder of magnet capacity could matter more than the market story around Aspen alone.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 73% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com