


EN
Why Everyone Is Watching Pandox (OM:PNDX B) Today
Pandox (OM:PNDX B) has drawn fresh attention after reporting third quarter results on 22 October 2026, with higher sales, revenue and net income compared with the same period a year earlier.
Pandox shares trade at SEK163.6 after a 1-day share price return of 1.49% and a 30-day gain of 3.54%. However, the year-to-date share price return is down 18.2%, while the 3-year total shareholder return of 61.13% points to stronger longer term momentum than the recent 90-day decline of 6.3% might suggest.
Scan how Pandox compares with a curated 195 high quality undervalued stocks that combines stronger balance sheets and cash flows with potential pricing gaps the market may be overlooking.
Pandox trades at a clear discount to analyst targets after a strong earnings print and a weak year-to-date share price. Is the market fairly cautious, or is the valuation gap too wide given these numbers?
Most Popular Narrative: 20.4% Undervalued
The most followed narrative puts Pandox fair value at SEK205.4, above the last close at SEK163.6. This frames analyst debate around balance sheet risk, capex execution and long term returns on the Dalata portfolio.
The main thing that has to go right is that Pandox converts its SEK 4.2b high-yield capex pipeline and the Dalata integration into the targeted 9.5 to 10% yields while containing financing costs and managing its roughly 52% loan-to-value and 2.4 to 2.5x interest cover.
The current valuation implies that the market continues to discount Pandox for elevated financing costs and balance sheet risk even though recent earnings growth, ongoing refinancing savings and delivery from Dalata and capex projects point to an undervalued share price.
See why 2 investors see Pandox as 20% undervalued.
Result: Fair Value of SEK205.4 (UNDERVALUED)
Still, the story can break if yields on the SEK4.2b capex pipeline disappoint, or if Dalata related leverage and interest costs stay heavier for longer.
Find out about the key risks to this Pandox narrative.
Another View: Pandox Through Cash Flows
Analysts see upside for Pandox on earnings and price targets, yet the Simply Wall St DCF model paints a very different picture. On that framework, the shares trade well above an estimated future cash flow value of SEK32.64, which points to an overvalued result rather than a discount. Which story do you trust more: the earnings path or the cash flow math?
For investors who want to unpack how that gap arises between fair value and today’s share price, the SWS DCF model is laid out step by step in the full valuation workup, including the key assumptions on growth, margins and discount rate that drive the result. Look into how the SWS DCF model arrives at its fair value.
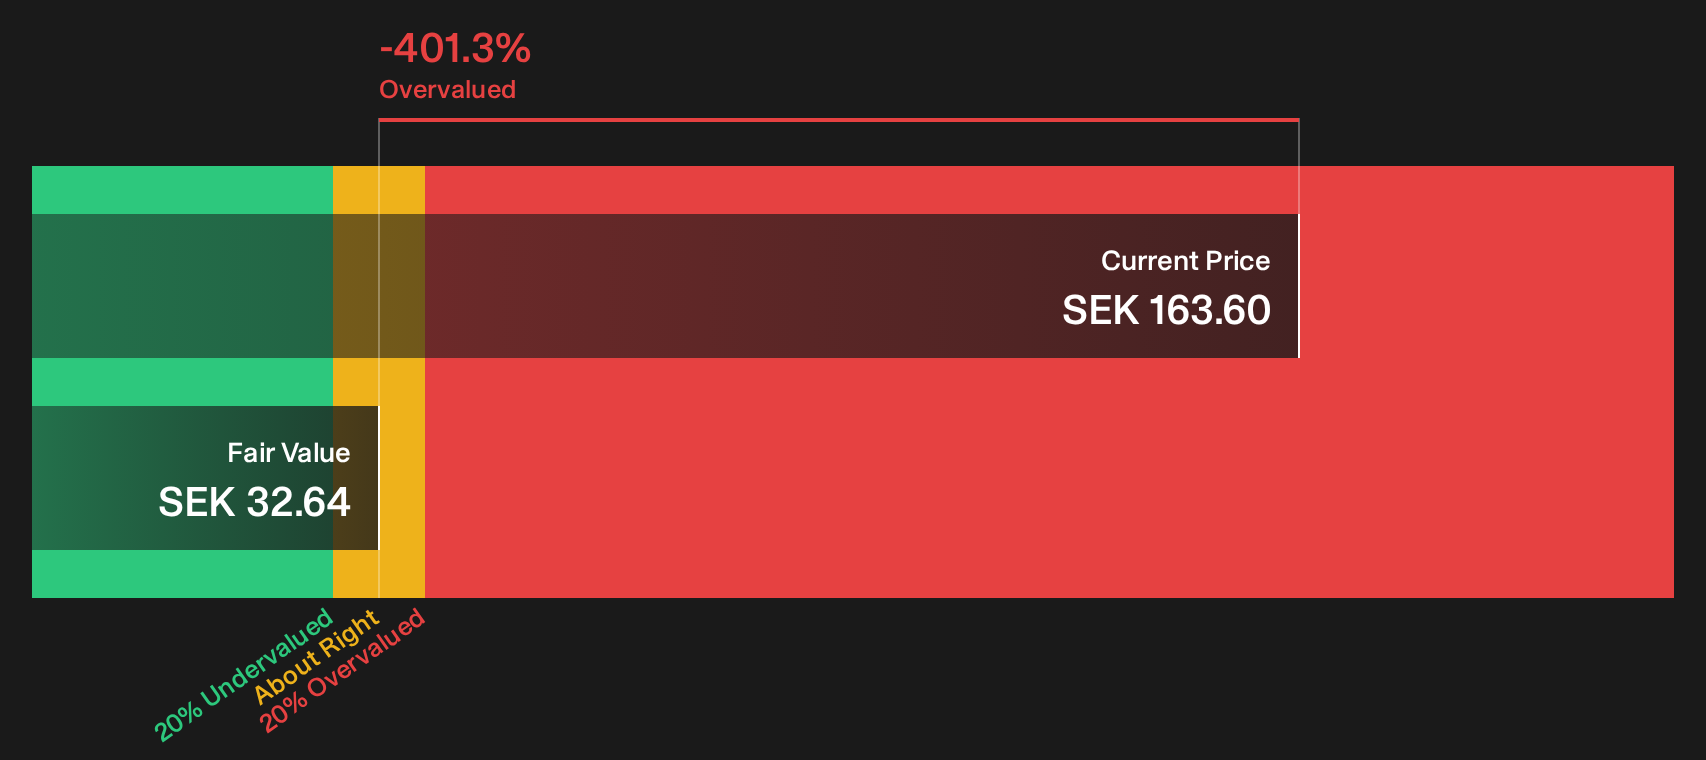
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pandox for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views like these only matter if Pandox investors use them as raw material rather than a script to follow. Move quickly from reading to testing your own thesis by weighing the 5 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Pandox?
Once you have a clear view on Pandox, widen the lens and pressure test your thinking against a wider set of listed opportunities using curated screeners.
- Target resilience by scanning a 223 resilient stocks with low risk scores that focuses on companies scoring well on financial strength and volatility controls.
- Hunt for mispriced quality through a 610 high quality undiscovered gems tailored to highlight stocks with strong fundamentals that many investors may be overlooking.
- Prioritise financial robustness with a list of solid balance sheet and fundamentals (207 results) designed to surface businesses with healthier debt levels and sturdier funding profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com