


EN
Why Analog Devices Doubters Were Wrong Before A 80% Gain
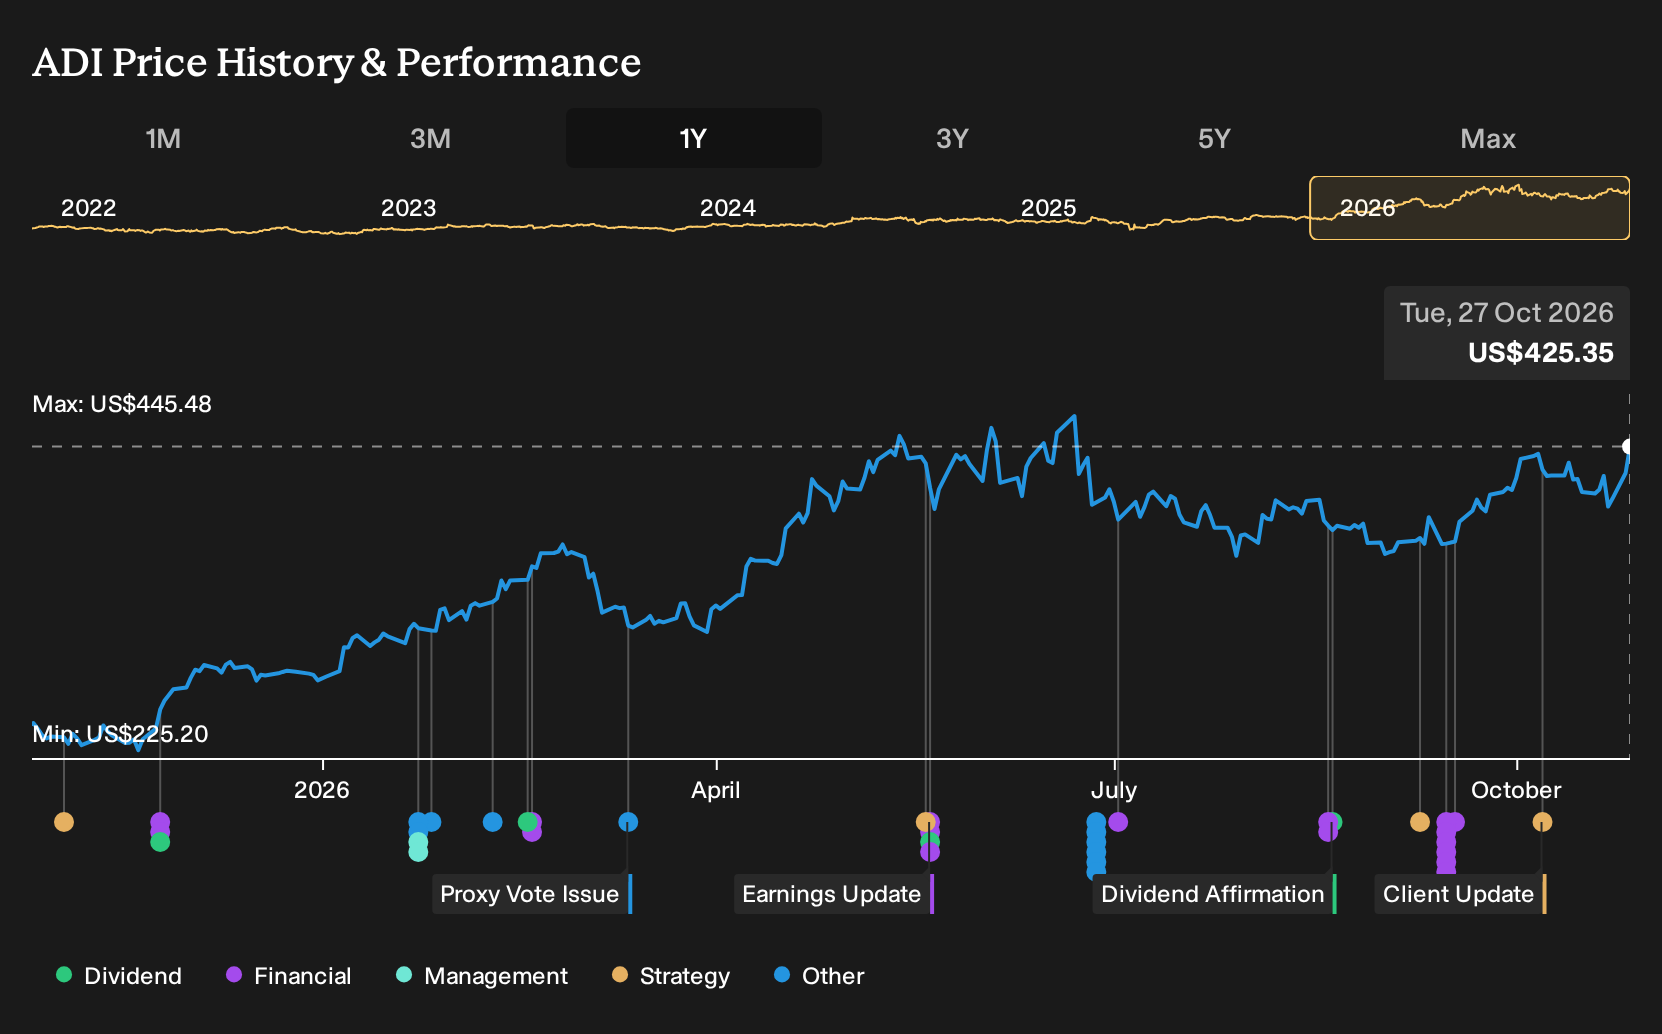
If you only glanced at Analog Devices headlines this year, record AI-fuelled quarters and big-ticket acquisitions might feel like the whole story. Investors who held Analog Devices over the past year are up 79.9%, including dividends. That gain landed after a starting point where bullish analysts saw upside and a bearish camp argued the shares already priced in too much. If you were deciding on 27 October 2025, which side of that split would have looked more convincing?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Analog Devices. See which of 42 power grid technology and infrastructure stocks may still merit a closer look.
The Two Analog Devices Stories Investors Had To Weigh
The shares cost US$243 at the start, and anyone looking at Analog Devices then had two sharply different stories to consider.
On the bullish side, the Narrative pointed to a Fair Value of US$267, with an assumption that revenue would grow 11.3% a year and margins would reach 34.6% as robotics and edge AI widened its opportunity.
The more cautious view focused on a Fair Value of US$155 and highlighted concerns that OEMs building chips in house and a shift toward digital systems could pressure demand and profit margins.
What The Results Changed For The Analog Devices Case
Analog Devices later reported Q3 2026 revenue of US$4.02b and net income of US$1.34b, compared with US$2.88b and US$518.5m in Q3 2025. Net margin moved from 18.0% to 33.3%. That combination of higher sales and profitability leaned toward the bullish narrative that expected stronger earnings power, although it did not directly address long term competitive threats.
The simple takeaway is this. When a thesis hinges on margins rising to a specific level, as it did for Analog Devices, you can track that claim directly in reported net margin and see how fast it is moving toward the assumption.
What Analog Devices' Price Now Asks You To Believe
Analog Devices trades at US$425 today after a 79.9% gain over the past year. The selected Narrative's Fair Value sits below the current price, which frames that rally as baking in a lot of confidence about where earnings and cash generation go next.
The Narrative leans on a simple tension. AI, autos and industrial demand could support strong profitability, yet the case argues recent optimism leaves less room if those end markets or acquisitions deliver less than hoped. A buyer now has to judge whether Analog Devices can keep turning its AI heavy pipeline into durable high margin revenue.
"The main thing that has to go right is that Analog Devices converts its AI driven data center, energy, aerospace and defense, ATE and automotive content pipeline into sustained high margin revenue while continuing to realise acquisition synergies and maintain strong free cash flow generation."
One Narrative disagrees with today's price. → See where this Narrative says Analog Devices should trade
Where Analog Devices Meets Memory
Once you have thought through Analog Devices, it can help to look sideways. AI hardware needs precise signals, but it also needs fast data access.
One specialist focuses on the memory and storage that AI servers rely on. It builds working memory for training and inference, plus flash storage for model data.
This business is leaning into higher bandwidth designs that keep accelerators supplied with information. It is also using longer supply agreements to gain better planning visibility.
If AI infrastructure keeps scaling, another question emerges. How much could a memory supplier shift away from classic boom bust cycles?
One Narrative has already put a figure on it. → Uncover the company trading 26% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com