


EN
What Is Behind Chugin Financial GroupInc (TSE:5832) Shares Climbing Today?
Chugin Financial Group Inc (TSE:5832) raised its earnings outlook for the six months to September 30, 2026, after reporting stronger ordinary income tied to securities portfolio rebalancing and higher interest income in a rising rate environment.
Today’s ¥3,440 share price comes after a 4.75% 1-day share price return and a 3.12% gain over the past week, even though the 30-day share price return is down 9.33%. Investors are still sitting on a 36.40% year to date share price return alongside a 65.90% 1-year total shareholder return that builds on a very large 3-year and 5-year total shareholder return base.
Scan for other regional lenders that may be benefiting from higher rates and stronger securities income with our curated list of solid balance sheet and fundamentals (23 results)
After a sharp rebound and a richer earnings outlook, Chugin Financial GroupInc now asks a practical question of you as an investor. Is it worth stepping in after this move, or does it make more sense to wait for a cheaper entry as the valuation stacks up against the new guidance?
Price-to-Earnings of 14x: Is it justified?
On a simple headline measure, Chugin Financial GroupInc trades on a P/E of 14x, which screens as cheaper than both its own estimated fair P/E of 16.8x and the peer average of 17.3x, even though it sits slightly above the broader JP Banks industry on 13.5x.
The P/E ratio compares what you pay today for each ¥1 of current earnings. For a lender like Chugin Financial GroupInc, where profits are closely linked to interest income and credit costs, this measure gives a quick read on how the market is weighing current profitability against expected future earnings.
Here the picture is mixed. The stock looks inexpensive against the peer group and below the fair P/E level that the fair ratio model suggests the market could move toward. At the same time, the current P/E sits a touch richer than the JP Banks industry, despite earnings quality being flagged as high and revenue and earnings both forecast to grow faster than the wider Japanese market.
Against industry, the comparison is blunt. A 14x P/E is higher than the 13.5x JP Banks average, so investors are paying a premium relative to the sector while still getting a discount to both the 17.3x peer average and the 16.8x fair P/E estimate that implies room for re-rating if forecasts hold.
Explore the SWS fair ratio for Chugin Financial GroupInc.
Result: Price-to-Earnings of 14x (UNDERVALUED)
Still, the bullish setup for Chugin Financial GroupInc can crack if higher rates reverse, or if securities portfolio gains unwind faster than earnings can absorb.
Find out about the key risks to this Chugin Financial GroupInc narrative.
Another View: Our DCF Model Says Overvalued
The P/E points one way, but the SWS DCF model points in the opposite direction. On this approach, Chugin Financial GroupInc at ¥3,440 screens as expensive compared with an estimated future cash flow value of ¥2,996.3, which flags the shares as overvalued on this metric.
This gap matters. It suggests you are paying a higher upfront price than the modelled stream of future cash flows might justify, so the margin for error is slimmer if forecasts or the rate backdrop shift against Chugin Financial GroupInc.
Look into how the SWS DCF model arrives at its fair value.
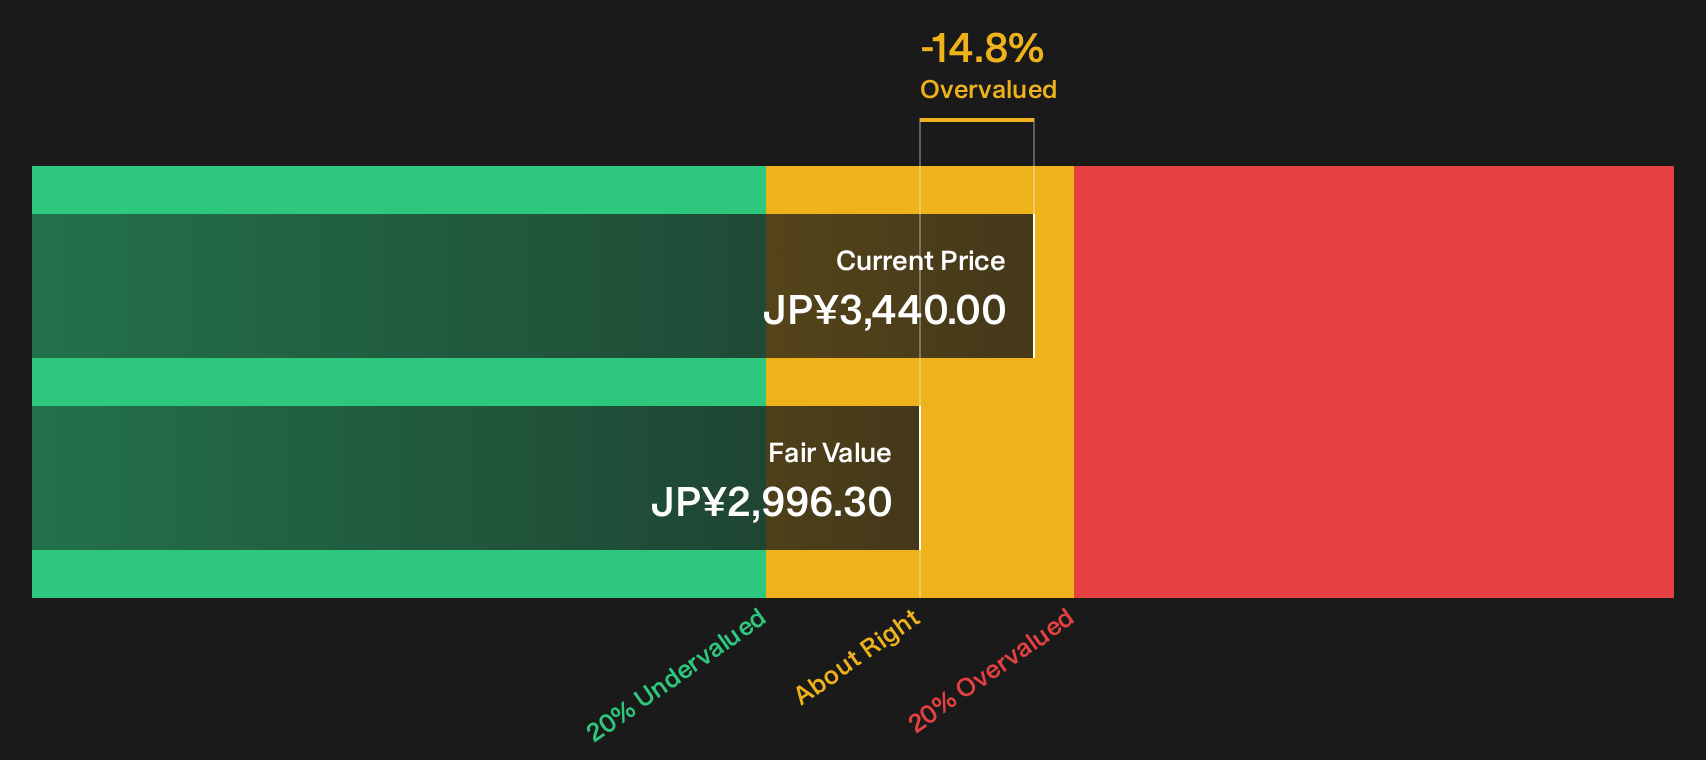
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chugin Financial GroupInc for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Chugin Financial GroupInc can feel confusing, so consider acting promptly, reviewing the data for yourself, and weighing both sides by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Chugin Financial GroupInc?
If Chugin Financial GroupInc has sharpened your focus on opportunity and risk, do not stop here. Broaden your watchlist with targeted stock ideas using the Simply Wall St Screener.
- Target resilient income by reviewing potential high-yield opportunities through the 29 dividend fortresses.
- Hunt for mispriced quality and see which companies screen well on cash flow and valuation using the 16 high quality undervalued stocks.
- Spot potential future leaders early by scanning for strong fundamentals inside the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com