


EN
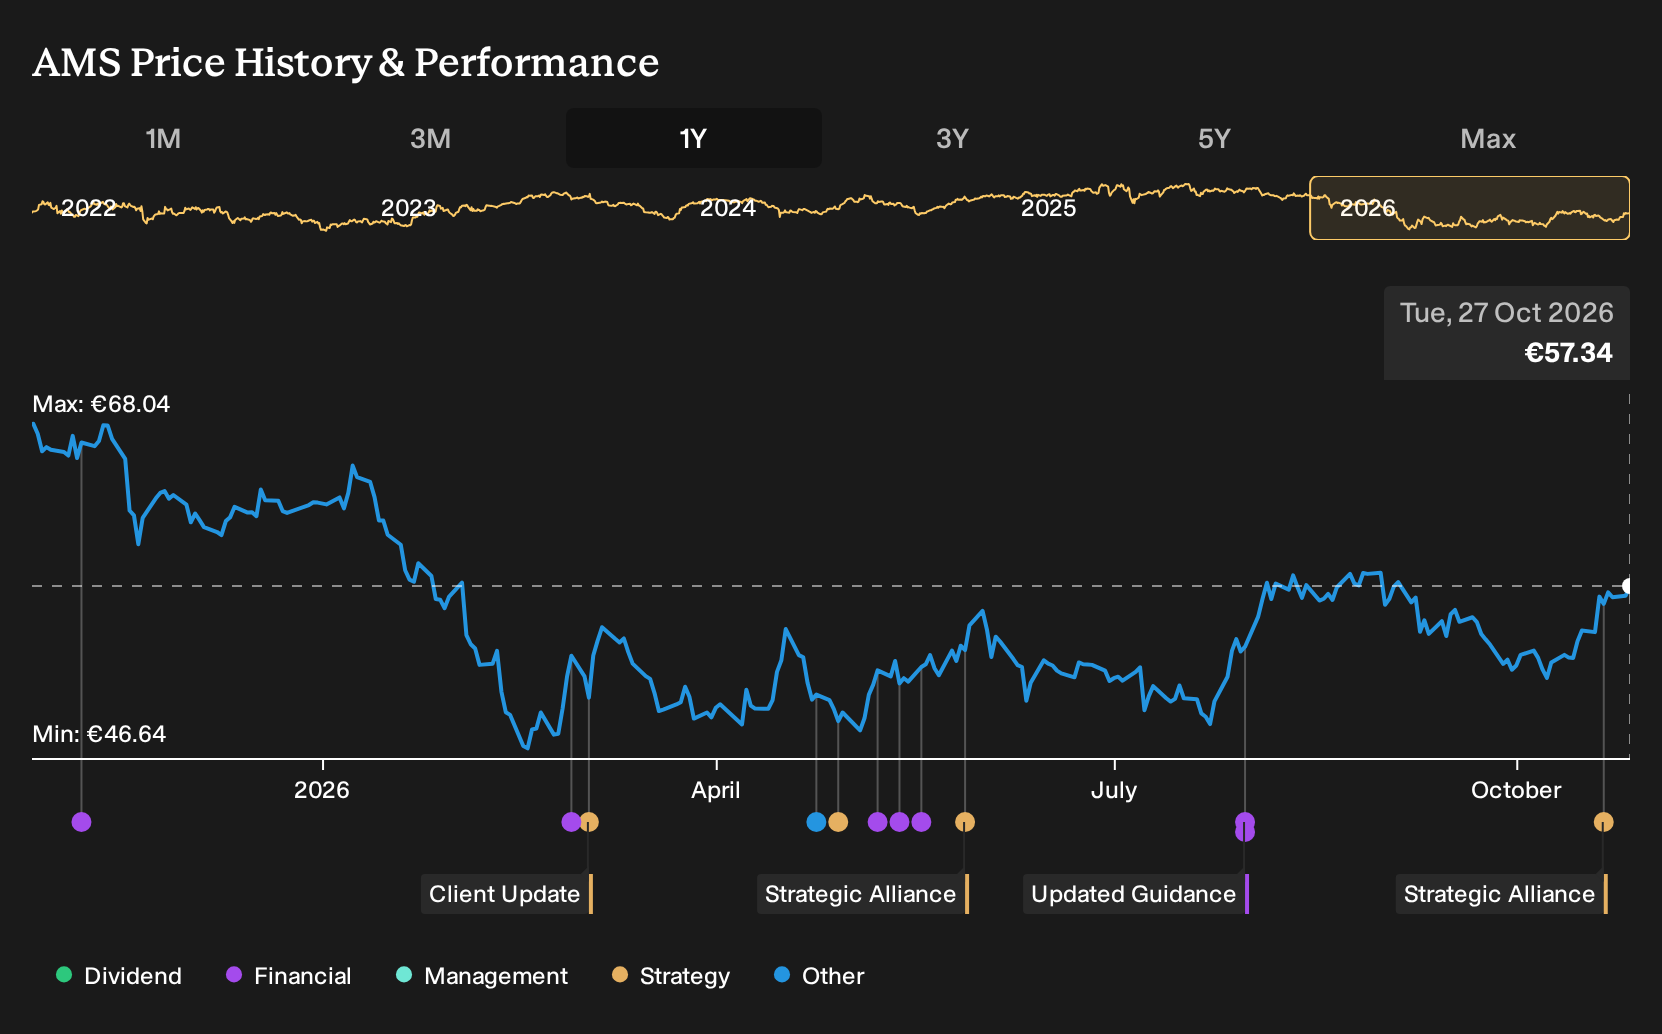
Should Earnings Downgrade Require Action From Amadeus Stock Investors?
- Amadeus IT Group and NVIDIA have expanded their collaboration through a Memorandum of Understanding to test GPUs, travel-specific AI models, and cloud efficiencies aimed at handling more complex, AI-driven flight search at scale, while preserving accuracy and bookability for sellers and travelers.
- In the same period, Amadeus IT Group's earnings outlook was downgraded, with consensus estimates cut by 2% for the current year. This highlights the cost, execution, and demand questions that sit behind its AI-focused investment plans.
- We will examine how Amadeus IT Group's investment narrative aligns with this deeper NVIDIA AI initiative and the softer earnings outlook.
Scan beyond Amadeus IT Group's AI push and earnings downgrade by comparing it with hand-picked peers in our 39 profitable AI stocks that aren't just burning cash that already pair AI exposure with positive profitability metrics.
Amadeus IT Group Investment Narrative Recap
To hold Amadeus IT Group, you need to believe its travel transaction engine stays central as AI reshapes how flights are searched and booked, while air-traffic-linked volumes remain a key swing factor. The MoU with NVIDIA points to heavier AI spend, yet the recent earnings estimate cut keeps execution on monetising that spend as the main near term test.
The biggest short term catalyst remains any clear evidence that AI, cloud and product investments help unit economics, even if bookings stay soft. The key risk is that higher R&D on AI, biometrics and airline IT drags on margins without offsetting revenue, especially with exposure to geopolitical shocks in air traffic.
The extended NVIDIA collaboration is the headline development here. Amadeus IT Group is experimenting with GPUs, CUDA based workloads and travel specific AI models to support faster, more complex search as AI assistants increase query volume and complexity. That work goes straight to the heart of its core processing platforms for airlines and travel sellers.
For you as an investor, the operational question is whether these AI heavy workloads can support better capacity handling and infrastructure efficiency rather than just higher costs. Success would support existing catalysts such as higher revenue per booking, deeper customer integration and more resilient economics when traffic is softer. Failure would amplify the existing risk that elevated AI and product spending weighs on earnings without clear commercial payback.
Amadeus IT Group's narrative projects €8.3b revenue and €1.8b earnings by 2029. This assumes 7.8% yearly revenue growth and an earnings increase of about €0.5b from €1.3b today.
Uncover why Amadeus IT Group's fair value indicates a 21% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Amadeus IT Group’s AI driven products themselves as the key catalyst. Before this NVIDIA MoU, the bullish camp was pencilling in revenue climbing toward €9.1b and earnings of about €1.9b by 2029, compared with consensus nearer €8.3b and €1.8b. That split shows how widely expectations can differ, and it invites you to explore which set of assumptions feels closer to your own view as this new AI partnership beds in.
Explore 2 other Amadeus IT Group fair value estimates, including one that suggests as much as 21% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amadeus IT Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amadeus IT Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amadeus IT Group's overall financial health at a glance.
Looking For More Ideas Beyond Amadeus IT Group?
If the Amadeus IT Group story has sharpened your questions about AI exposure, resilience and earnings quality, it can help to widen the lens across other stocks that fit different risk and return profiles using the Simply Wall St Screener.
- For investors who want potential value with quality fundamentals, scan a curated set of 195 high quality undervalued stocks that combine healthier balance sheets with supportive cash flows.
- If capital preservation is near the top of your list, focus on 223 resilient stocks with low risk scores that score well on financial strength and lower volatility indicators.
- For those hunting for less crowded stories with solid underlying metrics, filter through 610 high quality undiscovered gems that pair fundamental strength with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com